


2026-11-11 01:43:27
If you liked this piece, you should subscribe to my premium newsletter, and you can subscribe on the following links: $70 a year, $18 a quarter, or $7 a month.
In return, you get a weekly premium newsletter that dives deep into the finances of the AI bubble. Over the past few months, I’ve published a two part guide to the world of AI debt, an analysis of the (dubious) impact of generative AI on the global economy, deep analyses of the biggest players in the AI infrastructure space like NVIDIA (part one and two) and Oracle (part one and two), and the role private credit is playing in funding AI data centers, and how private equity, reeling from years of successive failed software acquisitions, is doubling down on the AI bubble.
Friday’s premium newsletter will be a continuation of this story. We’ve got a lot to say about NVIDIA, Megaspeed, and the illicit flow of AI GPUs into China. You won’t want to miss it.
If you want to get in touch — and especially if you have any juicy information about Anthropic, OpenAI, or any other companies in the AI bubble — hit me up on Signal at ezitron.76. I’m also on IB on your Bloomberg Terminal.
'Tis the nature of man, to sеlf-destruct again and again
I've news, the messenger's dead
Drowned in a sea of notes unread
Queens of the Stone Age - Run Away From The Mob
As you’ve probably read by now, Jensen Huang, CEO of NVIDIA, has admitted to having an affair with what appears to be a Chinese spy called Alice Huang (no relation), CEO of a company called Megaspeed, and who also goes by the name of Huang Le.
Though far from a household name (though mentioned in an earlier newsletter), Megaspeed is NVIDIA’s largest Southeast Asian customer, per Culper Research, which announced it had taken out a short position on the company in May of this year, citing its belief that NVIDIA’s indirect sales to Mainland China account for significant proportion of its revenue.
Culper Research’s excellent short report focuses heavily on Megaspeed, a firm with an unusual history and near-empty office in Singapore that, somehow, bought billions of dollars of GPUs in a short amount of time. Said company also has, as I’ll get into, an identical website to a Chinese neocloud that claims to have multiple data centers with advanced NVIDIA chips.
This was all revealed mere days after NVIDIA’s spokespeople dismissed allegations and called the relationship “completely normal and not unusual” after a New York Times article reported that (Jensen) Huang had been targeted by (Alice) Huang. President Trump had been briefed on the matter around a year ago, but had taken no action as he had, and I quote, “...been wary of disrupting Nvidia’s chip sales, which are helping to drive the economy and the stock market.”
The commerce department, per the Wall Street Journal, had been investigating Megaspeed as a potential chip smuggler since late 2024, with the investigation stalling once it was handed to the Justice Department (which I’ll get to later).
It appears, per the Journal, that the goal was to persuade Huang to use his influence with the highest echelons of American political power to get them to loosen chip export restrictions — though I’ll argue today that the other part of the plan was to use him to funnel sanctioned GPUs directly to China, irrespective of any policy changes in Washington.
Per The Journal:
Jensen Huang has long argued that the U.S. should loosen the rules that restrict sales of its chips to China. He has said this would continue Beijing’s dependence on U.S. chips and help Nvidia bring in revenue that benefits Americans, rather than spurring China to become self-sufficient.
Huang has now admitted to the affair, though he left out that he’d hired a PR firm known for handling sex scandals around October 2025 (per WIRED):
In Sunday’s memo, Huang wrote: “To my wife and family: I love you. I know an apology cannot undo what I have done. I hope our family will heal and that, over time, I can earn back your trust.”
Additionally, NVIDIA has launched an “independent investigation with a committee of independent directors, assisted by outside independent counsel,” but has “no reason to believe that either national security or NVIDIA secrets were compromised.”
As I’m about to explain, NVIDIA’s “investigations” don’t carry very much weight.
As I alluded to earlier, regular Where’s Your Ed At readers heard a little about the strange tale of Megaspeed back in March — a Singapore-based outfit that, according to Bloomberg in December 2025, was a “once-obscure spinoff of a Chinese gaming enterprise [that] evolved into the single largest Southeast Asian buyer of NVIDIA chips,” and exhibited odd signs that suggest it might be operating as a front for China.
Per Bloomberg, Megaspeed imported goods “worth more than a thousand times its cash balance in 2023,” with two-thirds of its imports being NVIDIA products.
From what I can piece together — and I’ll get into some detail later in the piece — Megaspeed was originally a Singaporean-registered mobile app developer called 7Road International that rebranded to Megaspeed in March 2023, after it was acquired by Huang Le Limited, making Alice Huang its managing director. At some point it launched a subsidiary called SpeedMatrix which was somehow able to buy about $4.8 billion worth of NVIDIA GPUs.
Sidenote: This is somewhat of a simplification. The actual structure of Megaspeed, Speedmatrix and the web of subsidiaries is complex by design. On Friday, we’ll get deep into the weird (and spectacularly dodgy) history of Megaspeed.
Per the Strait Times, Megaspeed pays for an expensive office space in Singapore where effectively nobody works.
Anyway, the investigation got weirder when Bloomberg tried to track down specific circuit boards that NVIDIA had told the US government were in specific sites, only to find that most of the circuit boards attached to the various GPUs were gone.
While the US government couldn’t account for the boards themselves, an NVIDIA investigation confirmed that they were at a different warehouse that NVIDIA had seen.
Data centers aren’t the only Megaspeed facilities Nvidia visited. The vast majority of Megaspeed’s $2.4 billion worth of Bianca boards, the circuit boards that house Nvidia’s top-end GB200 and GB300 semiconductors, were unaccounted for at the sites Nvidia described to Washington. After Bloomberg asked about those products, the chipmaker went to separate Megaspeed warehouses, an Nvidia official said, and confirmed the Bianca boards are there.
This person declined to specify the number observed in storage, nor where and when the chips — imported more than half a year ago — would be put to use. “Building data centers is a complex process that takes many months and involves many suppliers, contractors and approvals,” an Nvidia spokesperson said.
…
Asked about the rest of the Blackwell chips, an Nvidia official said the company visited separate Megaspeed warehouses, where it saw the hardware imported earlier and confirmed it hadn’t been diverted to China. But this person declined to specify whether the number of components Nvidia cataloged in storage matches the outstanding volume from Bloomberg’s analysis of Malaysian customs records. Megaspeed didn’t answer multiple queries on the location of and plans for those processors, nor on its facilities writ large.
Oh okay, if you say so! Thanks also for specifying that you confirmed the circuit boards — which were removed from the full chip for some reason! — had not been sent to China. No need to give us any further information!
Bloomberg would also identify a Chinese company called “Shanghai Shuoyao” having a near-identical website and investor deck (as mentioned) to Megaspeed. In Megaspeed’s version, the company discussed several “specific area computing clusters” in unnamed locations in “East South Asia”.
In Shanghai Shuoyao’s version of the website, these clusters were in China — specifically, the cities of Beijing, Shanghai, Shenzhen, and Wuhu.
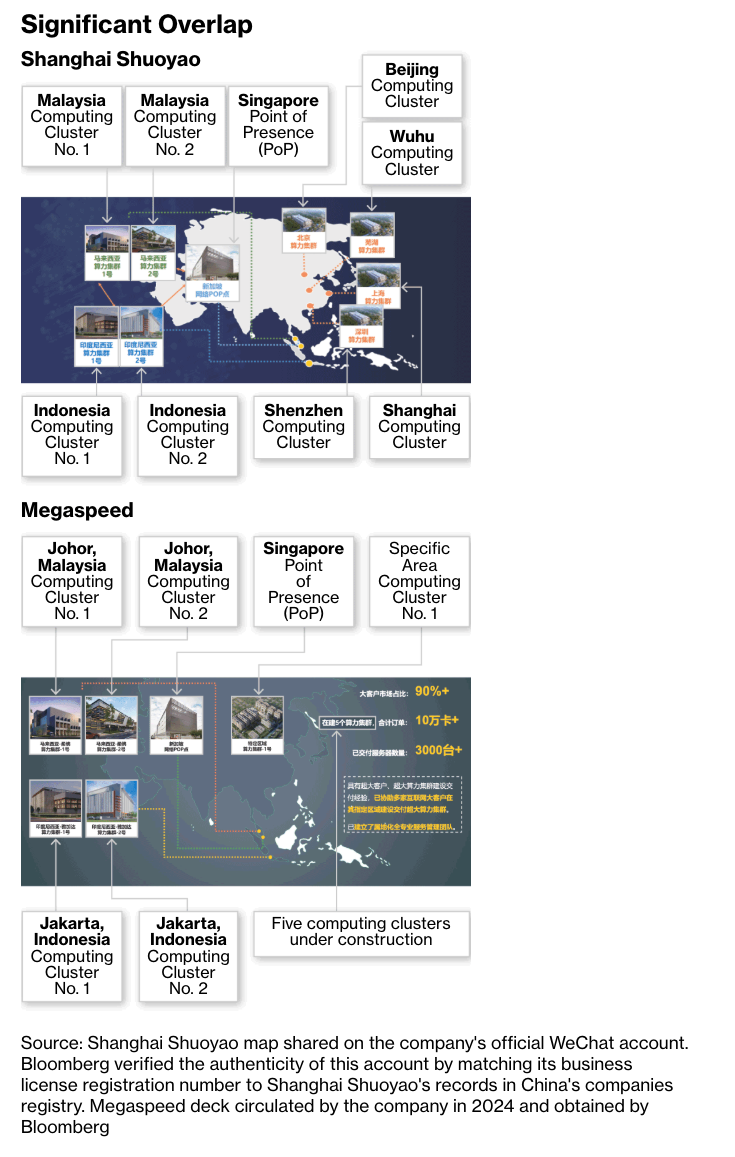
Per Bloomberg:
One of those projects, upon closer inspection, has a substantially different physical layout from the image in Megaspeed’s presentation. The other, a Shanghai data center that state media has said will be China’s largest, is a match. It’s called the Yangtze River Delta Project, and it counts Tencent Holdings Ltd., China’s most valuable company, as a tenant. (“Our data center operations fully comply with all applicable laws and regulations,” a Tencent spokesperson said.)
Shanghai Shuoyao’s website, meanwhile, was almost a carbon copy of Megaspeed’s page for its sub-brand Lumina, down to Megaspeed’s name appearing in Shanghai Shuoyao’s source code. The primary distinction between the two, other than language, was which Nvidia products they displayed. (As of the time of publication, Lumina’s website appears to be down, while Shanghai Shuoyao’s no longer references Nvidia. Shanghai Shuoyao didn’t respond to multiple requests for comment.)
And that’s how we get to the mysterious Ms. Huang — who appears to go by Huang Le, Alice Huang and Huang Xiaole, depending on the company, as I wrote in March:
Things get a lot weirder as Bloomberg digs in, including a woman called “Huang” that may or may not be both the CEO of Megaspeed and an associated company called “Shanghai Hexi,” which is also owned by the Yangtze River Delta project… who was also photographed sitting next to Jensen Huang at an event in Taipei in 2024.
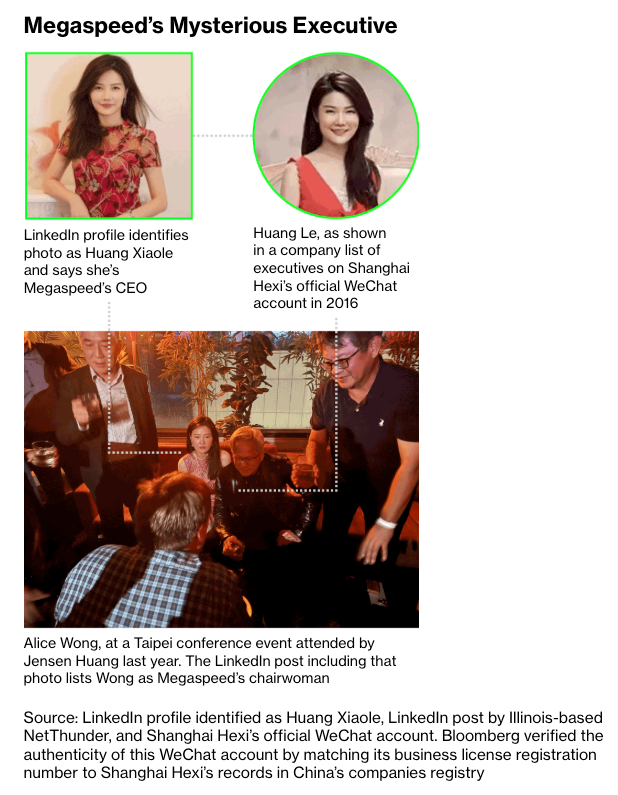
Various Twitter posters have unearthed both photos and videos of Jensen and Alice Huang (again, unrelated), but none of them feel more devastating than this:
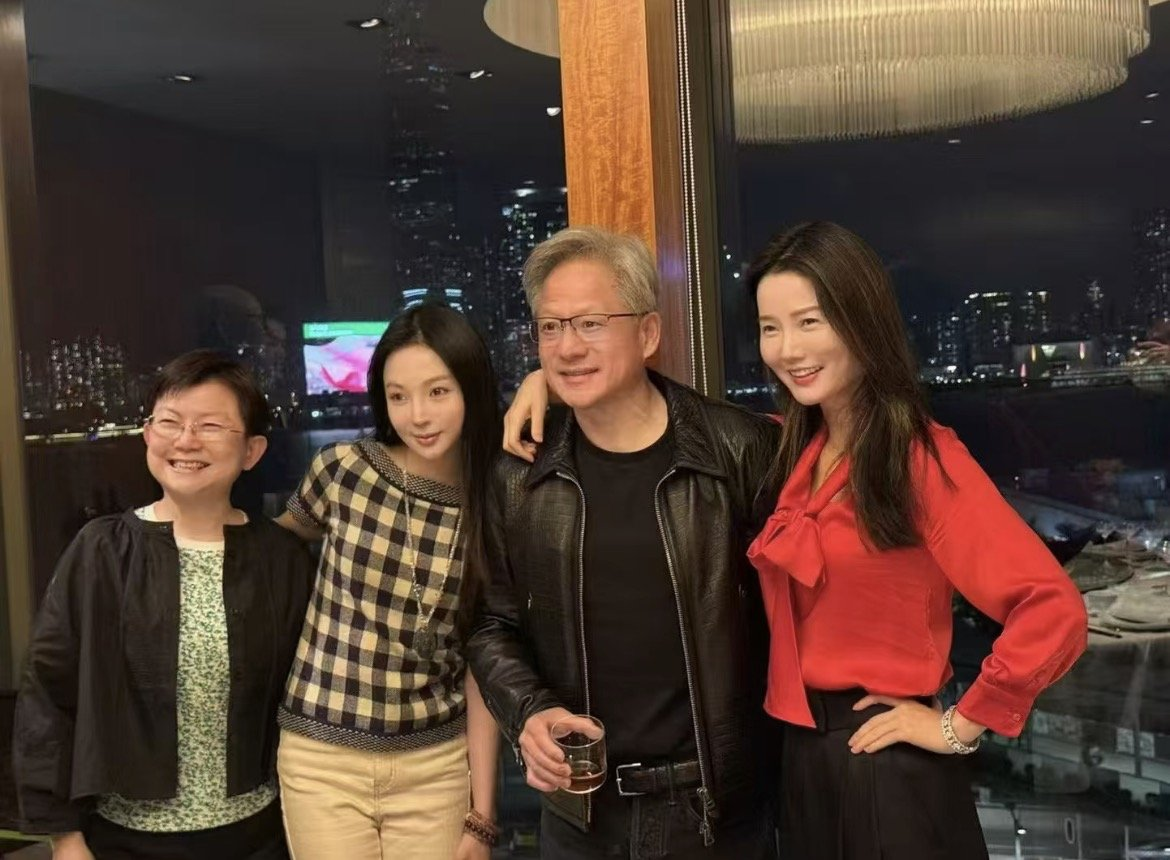
The full arm across the back and around the neck. The confident smile. Oh yeah, they fuckin’!
Seriously, I wish I had seen this photo back in March. Ladies, if you see a photo of another woman with their arm around a guy’s back like this, you are in the danger zone.
While we can’t say for sure, it appears that Ms. Huang was diverting chips to China, possibly to multiple Chinese data centers with at least one paid for by Tencent, and Jensen may have known about it in the literal and biblical sense. Per Trip Mickle of the New York Times on CNN last night, Alice could summon Jensen in the space of a few minutes.
And it appears that NVIDIA was both aware of the Huang tryst and worked diligently to block the US government from investigating Megaspeed further, all to sustain a relationship that was clearly in violation of US Commerce Department export restrictions.
So, from what I can piece together, it appears that Megaspeed ran its operation through a Malaysian subsidiary called Speedmatrix, and there’s very little else out there about the company.
Anyway, in case you needed more proof that something was wrong, Alice Huang was also detained by the Singaporean police in the middle of 2025, seemingly as part of a probe into Megaspeed, Per Bloomberg:
Singapore’s police force several months ago detained the woman who set up Megaspeed, Huang Le, people familiar with the matter said, meaning that she was brought in for questioning — and, one person added, restricted from leaving Singapore. Huang Le is not currently in custody and is assisting the police with their Megaspeed investigation, according to one of the people.
The police declined to comment on their questioning of Huang Le or elaborate on their overall probe into Megaspeed. The company declined to comment on Huang Le’s detention, and Bloomberg was unable to reach Huang Le directly, including after several visits to her registered Hong Kong address in an attempt to secure her contact information from people present there.
And if you’re wondering whether NVIDIA knew about any of this, you’ll be shocked to hear both that it did and hounded the US commerce department about it, eventually killing an investigation into Megaspeed in the process. According to the New York Times, the US commerce department was “deep into a monthslong investigation” of Megaspeed late last year, only to see it “abruptly transferred to the Justice Department” after getting an email from NVIDIA’s general counsel:
It is not necessarily unusual for Commerce Department agents working on a case to speak with a company’s representatives about issues involving their firm. But what was unusual was the content of the message. Tim Teter, Nvidia’s general counsel, said that Jeff Kessler, a top official at the department, had given Nvidia permission to reach out about the case.
The agents were alarmed that Nvidia had invoked the name of Mr. Kessler, their superior, who was nominated to his role by President Trump. Some viewed Mr. Kessler’s interaction with Nvidia as violating government procedure and potentially tainting the case, according to current and former government officials and others familiar with the incident.
Per Bloomberg, NVIDIA used its influence with the Trump administration to “muzzle” Kessler’s team investigating Megaspeed, and specifically wanted to know about Alice Huang’s detainment by the Singaporean authorities.
In late summer 2025, Nvidia’s Tim Teter called Commerce Under Secretary Jeffrey Kessler, who oversees US chip export curbs, to ask about the Megaspeed investigation, according to people familiar with the matter.
Specifically, Teter wanted to know whether Kessler’s Bureau of Industry and Security was involved in the Singapore government’s recent detention of Alice Huang, a Megaspeed executive, according to the people. Singapore police had brought Alice in for questioning and restricted her from leaving the country. BIS was not involved in that action, said the people, who spoke on condition of anonymity owing to the sensitivity of the matter.
Wow! How completely and utterly corrupt. I sure hope that the general counsel of the largest company on the stock market didn’t somehow interfere with an investigation…
It’s unclear whether Teter made any specific requests of Kessler related to his agency’s investigation into Megaspeed, which was separate from Singapore’s. But in the weeks that followed, BIS staff were muzzled in their ability to look into the company, including a mandate that they route all requests of Nvidia through Kessler or seek his approval for outreach — a highly unusual step that remains unique to the chipmaker, the people said. They were also told not to mention Megaspeed or Speedmatrix, the company’s Malaysian subsidiary, in external communications.
Teter, meanwhile, reached out directly to the agency’s staff, including requesting a meeting with one of them, according to some of the people. That BIS employee declined the meeting, and Teter responded that he didn’t understand why his request was spurned, since Kessler had granted him permission to communicate with BIS employees. It’s unclear exactly what Teter wanted to discuss with these individuals.
So, yeah, no problem everyone, nothing weird going on here. All that happened was that NVIDIA used its influence with the US government to suppress an investigation into a company very likely funnelling sanctioned NVIDIA GPUs to China. Very normal.
It should go without saying that the California State Bar should sit down with Tim Teter and have a chat about this whole affair, especially given the following from The Financial Times’ reporting that the FBI was now investigating the Huang Affair.
As recently as last week, Tim Teter, Nvidia’s general counsel, insisted inside the company that claims of an affair were inaccurate, according to people familiar with the situation.
Teter said the sources of information about the US government memo were people who had “an axe to grind with Jensen”.
“They are laundering salacious gossip,” Teter said, according to the people.
The only reason I’m not outright bringing up the California State Bar’s Rule 4.1 around Truthful Statements To Others is that it’s unclear where Teter made these comments. Nevertheless, this is deeply ugly.
In any case, let’s be clear about how blatant this scam was. Per The Financial Times, Alice Huang raised hundreds of millions of dollars in funding for a data center, promising that she had “no problem securing GPUs” in early 2025, and no, she wasn't referring to Huawei’s ascend chips:
The woman at the centre of the Nvidia spying scandal pitched an AI chips deal to China-based investors, touting her ability to secure the US company’s coveted GPUs and her commercial relationship with Chinese tech giant Alibaba.
In early 2025, Alice Huang and her business partner Kang Wei sought investment for a south-east Asia data centre project worth several hundred million dollars, according to two investors pitched on the deal.
The pair said they had “no problem securing GPUs” as a key pillar of the deal and cited Alibaba as a client of the project, according to one investor present.
According to documents viewed by the FT, Megaspeed borrowed money from Alibaba via a subsidiary in Singapore called Apex Enterprise Solutions.
Megaspeed offered its entire business as collateral, and Alibaba became its largest client… which is how NVIDIA got introduced to Megaspeed in the first place:
As part of the agreement, Speedmatrix pledged its entire business as collateral for the loan. Throughout 2024, Megaspeed’s balance sheet grew from $33mn to $3bn, much of which was based on its subsidiaries’ dealings.
Alibaba was Megaspeed’s anchor customer for its south-east Asia cloud service since the beginning and has remained its largest client, according to two people with knowledge of the matter. One added that Nvidia first met Megaspeed to discuss potential procurement because the company had shown their leasing contract with Alibaba.
How strange! The company that appears to have smuggled NVIDIA GPUs also features China’s largest tech conglomerate as its largest client.
This relationship is also discussed in Culper’s short report. Emphasis mine (from page 3):
Nvidia CEO Jensen Huang has not only vouched for Megaspeed, but seems to have quite literally walked alongside Megaspeed at every step, while maintaining an uncomfortably close relationship with Megaspeed’s Alice Huang, a Chinese national. He was first spotted partying with Alice Huang in June 2024 – the same month the Apex/Alibaba pledge was filed. He then dined with Alice Huang in Taiwan in May 2025 – just weeks after the news of U.S. trade restrictions. Finally, per one current Megaspeed employee, Jensen visits Megaspeed-linked data centers “every few months” and “every single time” he visits, he is accompanied by representatives from Alibaba. The Megaspeed employee characterized their relationship with Jensen as “very close”, corroborating another former Nvidia employee’s suggestion to us that many Nvidia employees wondered if there was a special relationship. The same employee added that, in contrast to public reporting suggesting otherwise, Alice Huang is “actually still our boss.”
While I intend to go into much more detail on this in this week’s premium, I need to directly call out one big allegation of Culper Research’s short report on NVIDIA — that 20% of its FY 2026 revenues came from China, or around $43.18 billion. Per Bloomberg, Megaspeed also imported 50,000 more GPUs than NVIDIA originally reported to the US government.
I trust Culper’s reporting, and think everybody needs to truly digest what this means.
This is an extremely bad situation, and I honestly wish I had hammered on it earlier and more emphatically. NVIDIA should be in front of a congressional panel. They should put it on the television. Somebody should be arrested and humiliatingly perp-walked into a courthouse in full display to a waiting throng of reporters and cameramen.
In any case, Culper directly alleges that this revenue is going away:
In March 2026, the DoJ indicted three individuals tied to Supermicro Computer (SMCI), including cofounder Wally Liaw, for allegedly smuggling $2.5 billion of Nvidia-powered servers into China via a Southeast Asian pass-through entity identified only as “Company-1.” Days ago, Bloomberg reported that “Company-1” is OBON Corp. (“OBON” i.e., “One Belt One Network”), a conclusion we agree with. We think there’s far more to the story, however. - We believe OBON is affiliated with Megaspeed, and that, in the words of one former high-level Nvidia employee we spoke with, “Megaspeed is just the tip of the iceberg.” The March 2026 indictment alleged $2.5 billion in smuggling via a single corridor (Supermicro to OBON) – our research suggests this corridor is just one of many in what is a complex and far-flung operation involving multiple additional Nvidia OEMs, partners, and intermediaries.
So, it’s very easy to smush together two parts of this story — the Chinese honeypot and her obvious association with Megaspeed — and miss the most obvious part of the story: that NVIDIA has inflated its earnings by more than $4.8 billion using sales to what appears to be a passthrough entity for customers in Mainland China.
And that’s just for one company. The true scale may be far, far greater — and Culper Research believes, as mentioned, the total volume of kit going to Chinese customers amounts to 20 percent of the company’s revenues for FY 2026.
In addition to getting his shit rocked crazy style, Jensen Huang — along with collaborators at NVIDIA including its general counsel — has deliberately and repeatedly violated US commerce law.
As much fun as it is to laugh at Jensen’s Bizarre Adventure, it’s very clear that both Huangs have collaborated to profit off of breaking the law, all in service of NVIDIA’s perpetual growth.
And it’s also blatantly obvious that this isn’t the only Chinese (or otherwise sanctioned nation) firm acquiring or buying NVIDIA’s Blackwell chips.
Back in November 2023, JustDario collated a list of NVIDIA’s “Elite Partners” — companies that NVIDIA claims “represent the deepest level of partnership with the company” — featuring multiple different “phantom distributors” like FongCon Co Ltd, which appears to be run out of an apartment above a wine shop in Taiwan, and a “preferred partner” in Russia with an address that leads to a creepy shed of some sort.
Sidenote: For some context about how much a "preferred partner" can buy, The Information reports that Century Litong - Chinese company that at some point was run by Alice Huang's sister Huang Yu with direct connections to Megaspeed - was part of a "labyrinth" of companies that helped bring $7.5 billion in chips to China, including the gear sold to Megaspeed.
This story cuts strangely with the New York Times’ recent reporting that the US Commerce Department cleared GPU sales to several firms that may or may not exist:
New Matrix passed that review. Yet recent checks by The New York Times found that, within China, there is little evidence the firm actually exists, raising questions about who in China is behind the company.
Only scant information can be found online about New Matrix, which was created 17 months ago. At the building that New Matrix lists as its address, a company directory does not include the firm. At the nearby property management agency for the industrial park, a receptionist and a manager both said they had no record of the company.
Back in August 2024, The Information reported that an electric appliance company in China managed to buy $120 million of NVIDIA’s H100 GPUs that were explicitly barred from sale using a shell company in Malaysia — much like Megaspeed did with its chips.
In August 2025, Steve Burke of GamersNexus ran an incredible video about the black market for smuggled NVIDIA GPUs, explaining in detail how A) easy it is to get these chips and B) how little NVIDIA appears to be doing to stop it. I love Steve, and think he’s one of the greatest journalists of our generation, but also think it’s impossible to argue based on this video that the US government or NVIDIA is unaware or incapable of solving this problem.
On November 20, 2025 — a day after NVIDIA’s Q3 Fiscal Year 2026 earnings — Reuters reported that the US Justice Department was charging four people “...in a scheme to illegally export NVIDIA AI chips to China.”
Said earnings had an exciting new addition — per Kakashii, Jensen Huang and NVIDIA changed how it reported its earnings, changing from reporting revenue from the location of the sale to the billing location of the company:
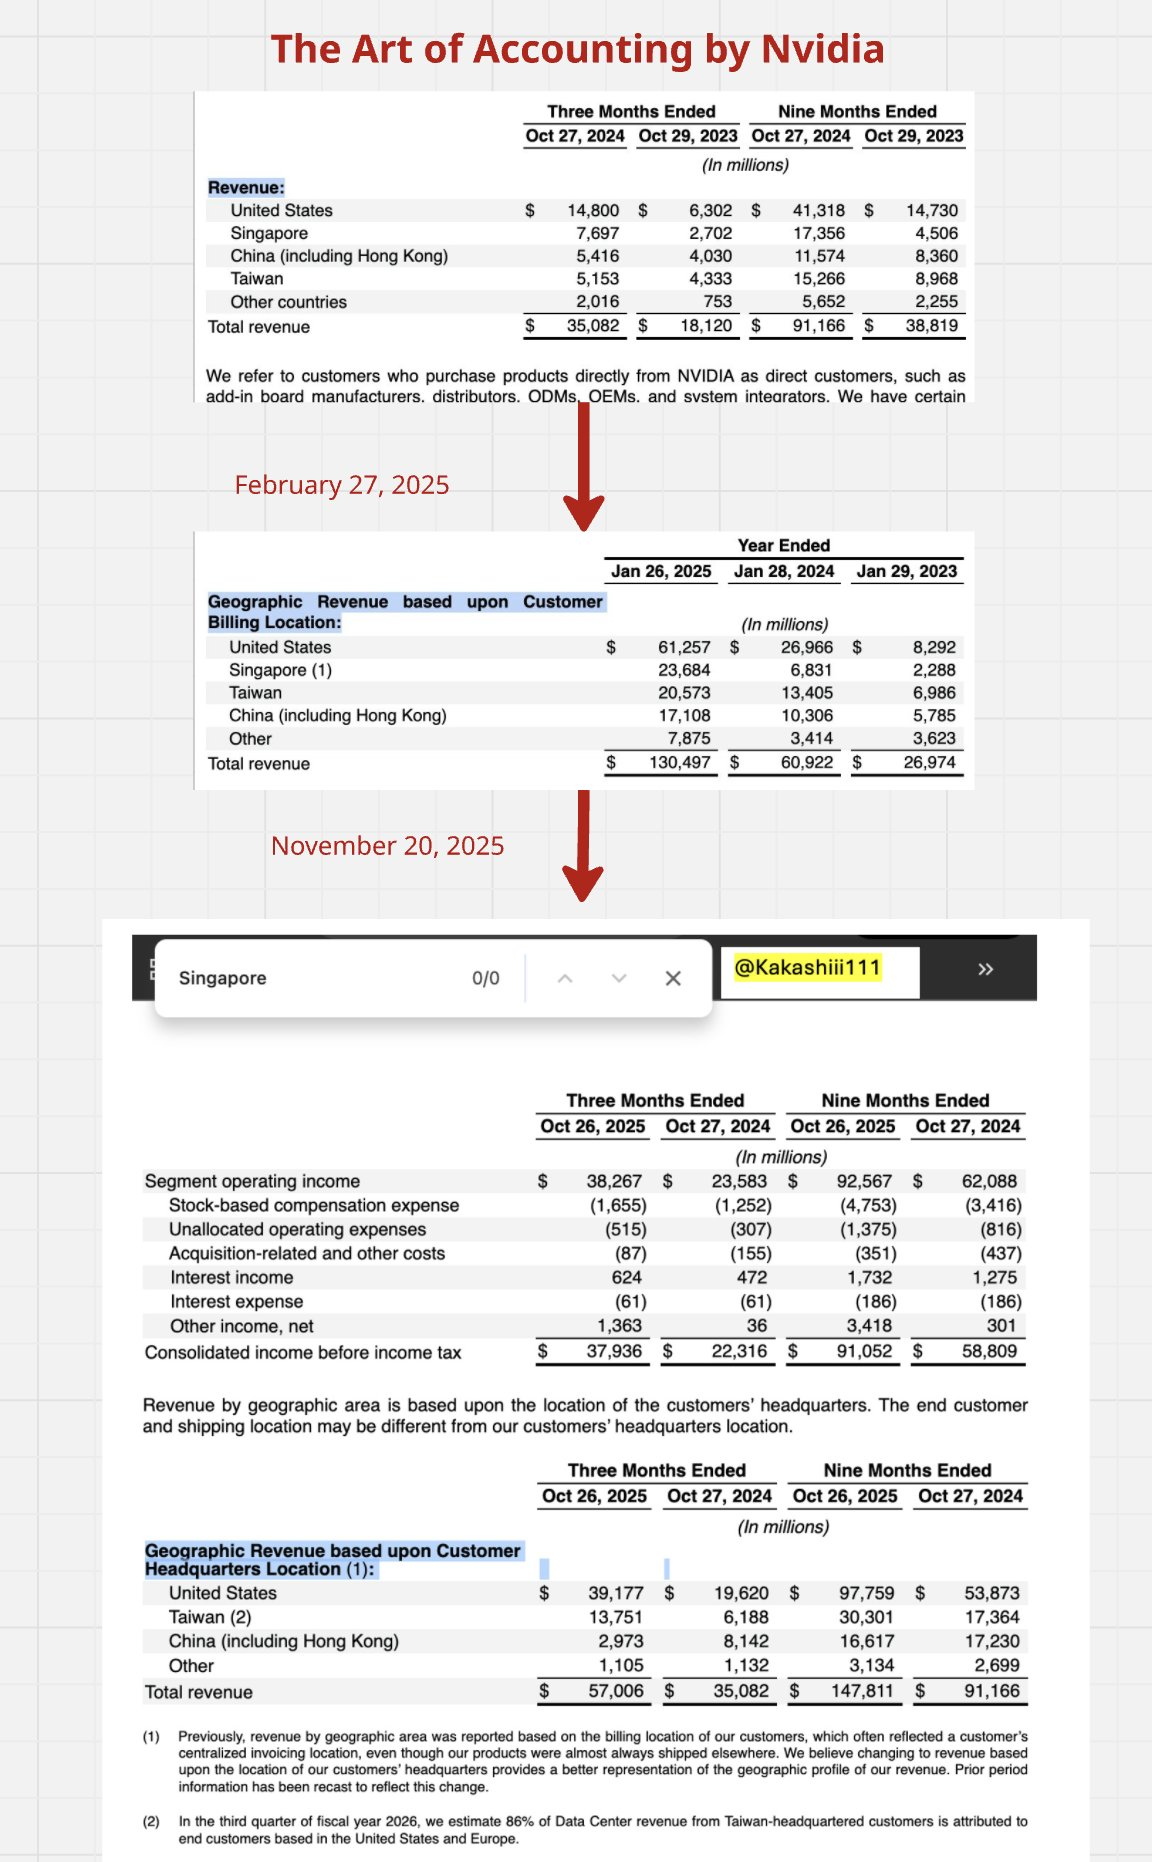
This meant that NVIDIA could now, say, sell GPUs to a company with a billing address in America or Taiwan, only for the chips to actually go to Singapore, or China, or the fucking moon, and basically every business and finance journalist missed it.
Then there’s the obvious, blatant, shameless case of Supermicro (a major vendor for AI servers) founder Wally Liaw, who (as I also discussed in March) was arrested along with several co-conspirators for selling hundreds of millions of dollars’ worth of GPUs to China, using hair dryers (per Tom's Hardware) to transfer serial numbers from real servers to dummy servers to thwart government inspectors.
Liaw was both very, very dodgy and very much connected to NVIDIA, Jensen Huang, and the greater AI industry.
As I wrote back in March:
Liaw, one of Supermicro’s co-founders, previously resigned in a 2018 accounting scandal where Supermicro couldn’t file its annual reports, only to be (per Hindenburg Research’s excellent report) rehired in 2021 as a consultant, and restored to the board in 2023, per a filed 8K.
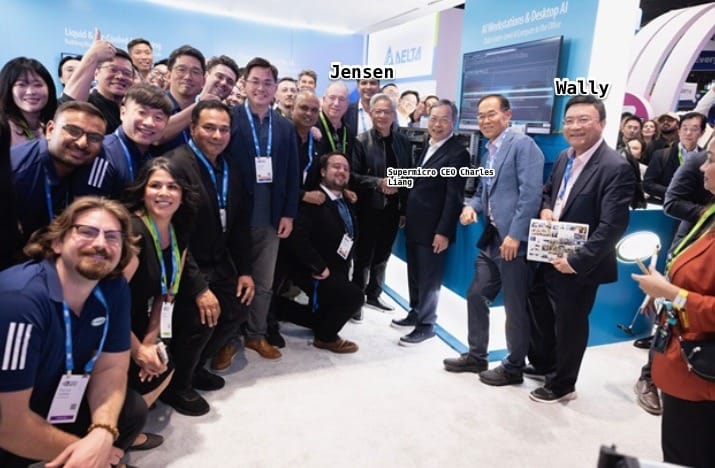
Mere days before his arrest, Liaw was parading around NVIDIA’s GTC conference, pouring unnamed liquids in ice luges and standing two people away from NVIDIA CEO Jensen Huang. Liaw was also seen congratulating the CEO of Lambda on its new CFO appointment on LinkedIn, as well as shaking hands (along with Supermicro CEO Charles Liang, who has not been arrested or indicted) with Crusoe (the company building OpenAI’s Abilene data center) CEO Chase Lochmiller.
Mere days before the arrest, Wally posed for a photo at NVIDIA’s GTC 2026 conference with the Supermicro team as Jensen and CEO Charles Liang shook hands barely two feet away.
It is completely insane that nothing else happened here. Supermicro continued to go about its business despite a cofounder and member of its board of directors being arrested by the Department of Justice for selling chips to the Chinese. Imagine if this happened at Dell! Imagine if former CEO of Accenture Bill Green, a member of Dell’s board, had been secretly using a hair dryer to move serial numbers off of Dell servers to sell to China! We’d have a fucking media blitz about it! It would be a huge scandal!
There’s also a direct connection between the Supermicro scandal and the Megaspeed scandal, per Culper’s short report, emphasis mine:
In March 2026, the DoJ indicted three individuals tied to Supermicro Computer (SMCI), including cofounder Wally Liaw, for allegedly smuggling $2.5 billion of Nvidia-powered servers into China via a Southeast Asian pass-through entity identified only as “Company-1.” Days ago, Bloomberg reported that “Company-1” is OBON Corp. (“OBON” i.e., “One Belt One Network”), a conclusion we agree with.
We think there’s far more to the story, however. - We believe OBON is affiliated with Megaspeed, and that, in the words of one former high-level Nvidia employee we spoke with, “Megaspeed is just the tip of the iceberg.” The March 2026 indictment alleged
$2.5 billion in smuggling via a single corridor (Supermicro to OBON) – our research suggests this corridor is just one of many in what is a complex and far-flung operation involving multiple additional Nvidia OEMs, partners, and intermediaries.
Late last night, Bloomberg also reported that Chinese AI lab Moonshot had rented 32 Supermicro servers equipped with B300 GPUs according to online documents they reviewed, all of which were based in China.
From Bloomberg, emphasis mine:
The online filings valued the servers at 432 million yuan ($64.8 million) and said they were located in China, indicating a possible breach of US rules that forbid sales to the country without an explicit license. Bloomberg News was unable to determine whether a license was obtained. Moonshot disputed the accuracy of the documents. After Bloomberg News contacted the company for comment, there were no longer references to Moonshot in the documents.
How do Supermicro servers keep making it to China? I thought we already arrested Wally Liaw!
These GPU smuggling stories have been around for years, and are left totally-unmentioned in any coverage of NVIDIA’s parabolic growth, despite the fact that it’s very clear that a not-insignificant part of that growth is flowing through illegal sales to China. The New York Times reported on both Megaspeed and Alice Huang in October 2025, including definitive proof of Megaspeed receiving restricted H800 chips.
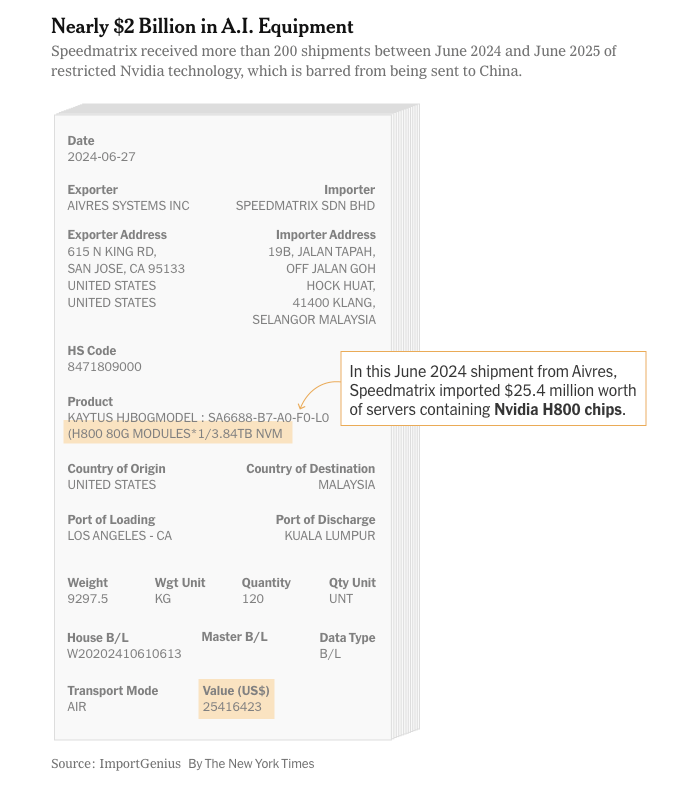
Yet across the Times’ coverage of NVIDIA’s Q4 (Calendar Year) 2025, Q1 2026 and Q2 2026 earnings, the Grey Lady neglects to mention anything about the smuggling story. If anything, it actively counters its own reporting.
And I quote from its coverage of the Q4 2025 earnings, written by Tripp Mickle, who was one of the four reporters on the Megaspeed story:
The company’s sales are growing even as it remains blocked from selling to China. Beijing has discouraged Chinese companies from buying Nvidia’s chips, hindering its access to the world’s largest semiconductor market. Mr. Huang had been appealing to President Trump to approve the sale of Nvidia’s latest line of chips to China and encouraging Beijing to allow companies to buy them.
Apparently a story that convincingly argued that NVIDIA was in fact selling chips to China was irrelevant to a larger discussion of NVIDIA not making any money from selling chips to China.
Sidenote: I am not alleging anything untoward. Tripp is a great reporter, broke the original Megaspeed story, and has been covering NVIDIA for years, including the story this piece leads with. The Times as an organization should have mentioned this story every single earnings cycle as a giant question mark and stormcloud over NVIDIA’s revenues, and its failure to do so is part of a larger glazing of Jensen Huang and NVIDIA, and a continual failure to hold the powerful accountable.
This can only be fixed on an institutional level, and journalists should be both empowered and emboldened by their editors to include these details every single time. Every single business and tech outlet covering NVIDIA should have been mentioning the Chinese smuggling operation, none more so than the Times, which has done such important and historic work reporting on it.
Half-hearted attempts to criticize NVIDIA’s massive circular financing operation have mostly failed to do anything other than provide marketing for what is ultimately a legal con, framing it as a “potential vulnerability” that is otherwise “unusual” without ever really saying “this is bad, and it’s a sign that NVIDIA is desperate to generate more revenue so that it can show investors perpetual growth.”
It is not a problem that NVIDIA funds its customers, its customers’ third party compute partners, its customers’ data center leases, its customers’ customers (and competitors), its customers’ customers’ leases, its customers’ chips, its customers’ landlords, its customers that are on the brink of death, its customers’ customers on the brink of death, and its customers’ customers that can quite literally not afford to pay for compute without its money. As long as it’s “legal,” it’s all “above board,” even when it’s blatantly obvious that NVIDIA has deployed over $100 billion (per The Information) as a means of keeping the industry afloat by making sure that everybody has the justification and means to buy and/or rent out its GPUs.
NVIDIA is an aggressively and unashamedly dodgy company that has done everything and anything necessary to sustain its growth, deploying about half of its Fiscal Year 2026 revenue to plugging holes in an ecosystem to make everybody ignore one horrible detail: that buying NVIDIA GPUs is a shitty deal for anybody other than Jensen Huang. If it wasn’t, hyperscalers would be screaming about the incredible, actual revenues from their $1.4 trillion or so in capital expenditures. If it wasn’t, CoreWeave wouldn’t be an ever-expanding timebomb that requires a few billion dollars every two months or so, nor would it have to hand billions to IREN, Firmus, Nscale, Lambda, and every other neocloud to buy its chips, or have to agree to rent said chips back from Firmus, Lambda, CoreWeave, or have to backstop Nscale’s lease with Anthropic.
These are the actions of a company actively manipulating the marketplace by operating on the fringes of finance law, knowing that the media and the markets will back whatever Jensen Huang says as long as the numbers keep going up and he, well, doesn’t actually break the law.
And remember: NVIDIA also loves lying. Last year the company claimed it had shipped six million Blackwell chips, even though any comparison with its actual revenues would show that wasn’t possible. In the end, it turns out that NVIDIA had changed the definition of what “GPU” meant, per Benzinga:
Notably, the bar chart shown at Nvidia's GTC DC in October reflected 6 million GPU dies shipped in calendar year 2025.
A footnote on the slide noted that the Blackwell and Rubin architectures use two GPU dies per chip. As a result, while 6 million GPU dies were shipped, the total came to 3 million complete GPU packages.
Anybody saying that this “isn’t lying” because “NVIDIA had a footnote somewhere” as if the media wouldn’t report the six million number as gospel, and the company made no effort to correct them, knowing that braindead analysts and gormless retail investors would read the big, huge, beautiful number and say “wow, Jensen Huang is the best!”
And then there’s the outright lies, per Thomas Thornton, about how NVIDIA was making effectively no revenue from China.
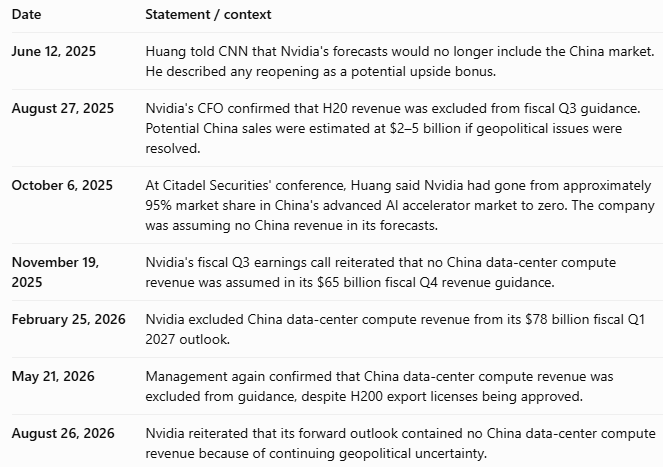
As noted by Shakeel Hashim of Transformer, NVIDIA’s spokespeople have lied repeatedly about the Megaspeed situation, which is par for the course — after all, very few have had the interest or courage to actually push back against their narratives, and the Megaspeed story sat inert for over a year outside of Bloomberg and the New York Times’ reporting, as did Culver’s short sell report that I’ll dig into more in this week’s premium.
This is what happens when you fail to push back on the powerful. Mainstream journalism has failed to hold NVIDIA to account, failed to warn investors of the risks, failed to push the powerful for clarity, failed to speak directly about the manipulative, suspicious and outright crooked way that this company runs, and done so all under the banner of perpetual growth and the larger Rot Economy.
Any defense using the word “objectivity” is utterly cowardly — you can use words like “allegedly” or “or “suspicious” or “obfuscative” for any and all of the things I’ve described — they are objective statements, because NVIDIA has acted suspiciously, and taken great pains to mislead the public about its growth, both in its dealings with Chinese shell corporations and how much of its revenue comes from neoclouds effectively handing it back its own money.
It’s also fucking laughable how much everybody talks about the “dangers of China getting access to powerful AI.” It already happened! China has NVIDIA GPUs! They’ve had them for years!
The Information reported in December 2025 that DeepSeek trained its latest models using Blackwell GPUs! It’s been happening for years, it’s been reported multiple times, in gratuitous detail, and somehow none of it was relevant to NVIDIA’s earnings or the world at large until it turned out that Jensen had had an affair.
When you remove the “Chinese government” and “Whatever Sounds Jensen Makes In The Bedroom,” nearly the entire Megaspeed story has been thoroughly reported! It’s all been out there! And to make matters worse, there were members of the media who said it wasn’t a big deal! Culver’s short report came out in May 2026 and explained in arduous detail — including the Alibaba/Apex deal! — exactly what was going on.
Everybody wants this to be a localized story about a horny CEO and a dastardly Chinese spy, but what it actually is is a coordinated, multi-layered conspiracy to dodgy US export controls that may very well have been totally ignored if it wasn’t for the espionage angle. In writing out everything that happened, it’s become alarmingly clear how badly the entire media missed on this, because most of the information is old.
I also see little to no discussion of how much of NVIDIA’s revenue was generated through these illicit sales. As I mentioned previously:
NVIDIA already has its own revenue concentration problem — 44% of its first half FY2027 revenues came from three customers, and in Q2 FY2027, 70% of its accounts receivables were from three customers, with 16% of its revenues coming from one. One. How is this not more worrying to people?
Could those all be above-board American businesses? Sure! But NVIDIA’s deliberate obfuscation of the final destination of its GPU sales now makes its obfuscative revenue disclosures an issue of national security (depending on how you feel about LLMs). It’s impossible to argue that NVIDIA is not selling GPUs to China through a web of proxies and shell corporations — and now the only real questions are how much, to whom, and when.
I do not expect the Trump administration to do very much about this, though perhaps I’ll be proven wrong given the “China” of it all, and how brazenly NVIDIA has acted.
In any case, one has to ask — why did Jensen Huang blow up his life?
The Wall Street Journal reports that he met Alice Huang sometime in “early 2024” at an NVIDIA event — likely referring to GTC 2024 in March — and then met again in June 2024 at Computex Taipei:
The two later met at Computex Taipei in June 2024. According to a photo posted on LinkedIn by NetThunder, an Nvidia business partner, they appeared at a party together along with senior executives from Gigabyte Technology, which develops and sells servers with Nvidia chips.
In May 2025, during a visit to Taiwan, Alice was seen among a group of tech executives dining with Jensen at a local restaurant. Video footage and photos captured the two pecking each other on the cheek and getting into the same car when leaving.
The fact that Alice Huang — the CEO of a barely-existent “Singaporean” neocloud — was at a party seated next to the CEO of NVIDIA and senior executives from Gigabyte (a huge NVIDIA partner) is in and of itself indicative of their closeness and (I’d guess) an attempt by Jensen to impress her.
Every guy has, at some point, desperately fallen for a girl and overcompensated when trying to impress her, and while everybody will try and frame this as simply business and sex, I suggest something very, very different: Jensen Huang actually liked this woman, and dare I say it, I think she made him happy.
The average Jensen photo has a cold sternness — and, I hate to say it, he doesn’t look particularly happy when photographed with his wife Lori, who is a victim of a horny, greedy man who got taken in by the world’s most obvious honeypot. Even when becoming visibly frustrated with Dwarkesh Patel and saying that he (Jensen) wasn’t “somebody that woke up a loser” — all while emphatically arguing that NVIDIA should ship GPUs to China — Jensen remains relatively stone-faced.
Now, let’s take a look at his face when he’s next to Alice Huang:
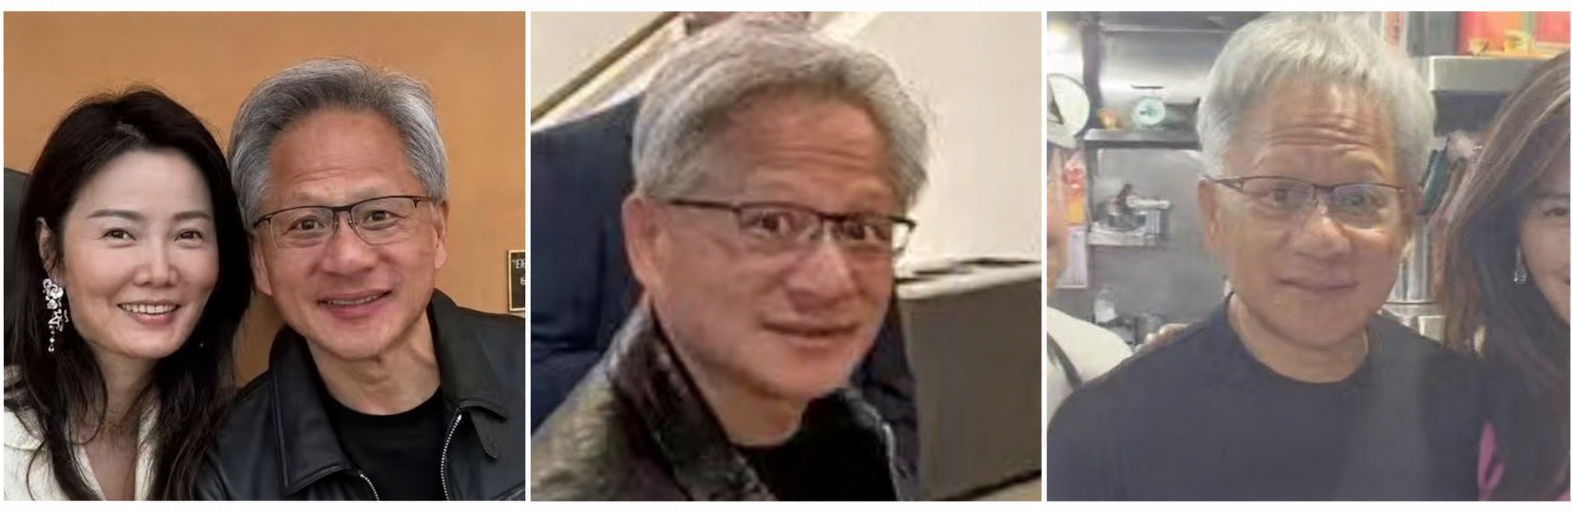
This big, strong, powerful man, dare I say it, being himself after goofily falling for someone that turned out to be a Chinese spy, a fact that Jensen may or may not have been aware of. I have looked at an alarming amount of photos of Jensen Huang for this piece, and I can find no other examples of him looking this happy.
And, like many powerful men, Jensen Huang is too much of a fucking coward to do the work to either cut off the relationship before the cheating, or file for divorce before doing so. I’m not condoning anything he’s done, but time after time guys refuse to make the tough decisions, opting instead for a continually-compounding chain of easy yet dangerous choices that ultimately blew up in their faces.
Most will describe this relationship in terms of sex and a greater con, and they may indeed be right. Perhaps there’s a world where Jensen found a kind of thrill from giving it to a foreign agent “Feynman style,” all while helping her acquire billions of dollars’ worth of GPUs. Perhaps he had no idea, but that would make him one of the stupidest men alive.
I think the reality is a little sadder — Jensen has (or had) genuine feelings for Alice, she made him feel alive, and he, like so many other men, chose to make boneheaded choice after boneheaded choice to impress her, engaging in some of the single-worst examples of OpSec ( by which I mean being repeatedly photographed and videoed with her, and also selling her billions of dollars’ worth of GPUs) in the history of modern society.
This man is worth $150 billion and would have likely been swindled by Bugs Bunny in drag.
Despite claiming he didn’t wake up a loser, all that money and power couldn’t protect the man from his heart or his hog, and apparently Jensen’s parallel processing was insufficient to stop the dastardly Chinese from running the most obvious honeypot in history.
No amount of money or power can stop an insecure man from refusing to take responsibility for his feelings or frustrations. Huang believed that he could have whatever he wanted under whatever terms he wanted, and in walking that line got burned, thinking he was smart enough to outrun consequence. He didn’t care about his wife, his company, national security, or really anything other than what he was doing to or with Ms. (Alice) Huang.
And like every big, stupid dickhead, he assumed that nothing bad would ever happen, that nobody would find out, and that the way that NVIDIA obfuscates its customers’ locations would keep his tryst and Megaspeed’s sales hidden. When Megaspeed came to light, I would bet he assumed the media and the Trump administration would simply leave it alone, which was true right up until Alice Huang was revealed to be a Chinese agent.
In some ways he was correct. As I’ve repeatedly said, the Megaspeed story has been publicly-known for more than a year, explained in exhaustive detail in both Bloomberg and the New York Times in late 2025, my own coverage in March 2026 and Culper’s short report in May — shit, I even mentioned Megaspeed seven minutes into my interview with Jon Stewart on October 28 2026 — and sweet fuck all happened until the news broke of Ms. Huang’s job with the Chinese intelligence services.
The media happily continued reporting on every billion dollar stimulus that NVIDIA issued to random AI companies and neoclouds without a single mention of the obvious, blatant GPU smuggling operation going on in broad daylight, reported at length with pictures and proof, mostly because NVIDIA refused to admit it.
Even now, as Huang’s dirty business is on display for all and sundry, NVIDIA has yet to discuss — or be asked — about Megaspeed itself in any interview I can find. Jim Cramer, Emily Chiang, and anyone else who sat in front of Jensen without asking about this directly should be ashamed of themselves.
Sidenote: I will add that both the Times and Bloomberg have stayed on this story, and Ian King of Bloomberg in particular has a storied history of pushing back against the company.
Nevertheless, I think the vast majority of the mainstream press has actively worked to gussy up NVIDIA’s image, and the only reason that anyone is willing to start asking ugly questions about this company is that it’s now safe to do so.
Anyone attempting to claim that this has “nothing to do” with NVIDIA’s overall business is a fucking mark. We have compelling evidence that NVIDIA has been inflating its revenues using Chinese smuggling operations — and have done so for years — that were likely known at the highest levels of the company.
In a sane society, outside of an AI bubble, this would have led to the immediate resignation of both Jensen Huang and general counsel Tim Teter.
And let’s be clear about something. Jensen Huang is not an “incredible human.” He’s a liar, likely a crook, a manipulator, and based on all the reports I’ve read should already be in handcuffs. Jensen has acted like a coward and a loser, and what he's done outright sucks — for national security reasons, for how brazen it is, and how much embarrassment and humiliation he’s brought his family, especially his wife of 40 years.
It is a tremendously shitty thing to do before you get to how Jensen Huang likely violated US sanctions around selling NVIDIA GPUs to China. He is not a “great guy” or “a good human,” he’s a horrible, avaricious toad that got too horny and greedy. He wanted to have sex, he wanted to sell more GPUs, and he ran them in parallel, “Grace Blackwell style.”
It is not a “mistake” to fuck another woman decades into your marriage, nor is it a “mistake” to sell that woman’s company billions of dollars of GPUs, nor is it a mistake to repeatedly have your comms people lie, nor is it a mistake to use your general counsel to intimidate the commerce department into looking away from your obvious misdeeds.
Jensen Huang is, aside from everything else, a genuinely embarrassing example of what it means to be a man. As the CEO of the largest company on the American stock market and the bedrock of the entire AI bubble, all he had to do was keep selling GPUs and simply sell Alice Huang some GPUs without any of that messy romance — but his worthless, cowardly, weak-willed ass couldn’t help himself.
If you are a guy who feels compelled to defend Jensen Huang because of any allegiance to the AI industry or men in general, you are a colossal loser and have the mindset of a peasant.
The tech industry should outright reject weak-willed and morally-corrupt losers like Jensen Huang. As one of the richest and most-powerful people in the world, we should hold NVIDIA’s CEO to the highest standards imaginable both legally and socially, and that includes crucifying him for embarrassing his wife, his family, his company and his country.
From the circular finance to the infidelity to the lies to the intimidation to the fucking brazen nature of all of the above, everything Huang has done is utterly repulsive, and should be treated as such.
And let’s not forget that he has forced billions of dollars’ worth of GPUs on hyperscalers months before they need them, massively inflating the price of RAM and all consumer electronics as a result, all as a means of creating perpetual growth for NVIDIA — a truly horrifying and immoral act that made billions of people’s lives worse so that a company could hit its quarterly revenue estimates. Those defending this practice too have the minds of peasants, and crave the abusive control of a feudal lord with their entire being.
NVIDIA should fire Jensen Huang immediately, along with its general counsel. The US government should immediately start a criminal investigation into Megaspeed and all connected counterparties, as well as anyone at NVIDIA who oversaw any smuggling operations. The SEC should thoroughly investigate NVIDIA’s revenue recognition standards, and the US government should create regulatory standards that make its tactics illegal.
If you disagree, you are advocating for the corrupt and deceitful to profit at any cost. Men like Jensen Huang are the reason that the tech industry sucks, and until it purges these morally-repugnant oafs, our entire society will suffer.
If you liked this piece, you should subscribe to my premium newsletter, and you can subscribe on the following links: $70 a year, $18 a quarter, or $7 a month.
Friday’s premium newsletter will be a continuation of this story. We’ve got a lot to say about NVIDIA, Megaspeed, and the illicit flow of AI GPUs into China. You won’t want to miss it.
If you want to get in touch — and especially if you have any juicy information about Anthropic, OpenAI, or any other companies in the AI bubble — hit me up on Signal at ezitron.76. I’m also on IB on your Bloomberg Terminal.
2026-11-07 00:44:41
I’ve generally avoided politics here and the few times that I have done so I’ve received a few pissy emails, but Tuesday night was a wonderful, abundant font of hope in what has been an unspeakably grim two years.
We have felt land-locked in a suffocating era defined by an oafish, half-hearted fascism that lashes out in random directions, where the cruelty is the point, creating a sensation that nothing good can ever happen again — something amplified by the fact that cynical malcontents have turned everything into a casino or strip-mining operation.
And we’ve watched as the political and social infrastructure has caved to their every demand, the media has enabled them, and the existing systems have empowered them. It’s felt for most of my life that we’d never escape the weight of the eras of Reagan, Clinton and Obama, every time people have been sold further entrenchment in systemic thinking.
Nothing will ever be perfect, and I do not think every wish gets fulfilled. Tuesday night proved that things can change, for the better, and that seemingly-impossible movements can be kneecapped and nearly-entirely collapse in the space of months.
And yes, the Blue Wave could very much lead to the bubble bursting, per Bloomberg’s aptly-named “Big Tech Soars on Bet Dems Will Save AI Spenders From Themselves”:
“The market is acting like this represents the end of the AI buildout,” said Robert Pavlik, senior portfolio manager at Dakota Wealth Management. “If that means the hyperscalers aren’t spending ridiculous amounts of money to build out compute, that means they could become cash-flow positive again.”
Exit polls showed that voters strongly oppose new data centers in their communities, Keith Parker, UBS’s head of global macro equity strategy and US equity strategy research, wrote in a note to clients on Wednesday. “The blue wave will have implications for equities, with the biggest impact likely coming from an increase in data center regulation at the state level near-term,” he wrote.
A great deal of the “inevitability” of the AI bubble comes from the assumption that the rich and powerful always get what they want, and that anything they say — even the most deranged and unrealistic things in the world — will simply happen. Things like building 190GW of data centers, or, shit, 7.1GW of data centers just for Sam Altman and OpenAI only make sense when you’re under the assumption that everything in the world is at a fixed point derived from the whims and proclivities of untethered capitalism.
While nothing has truly shifted yet, we are no longer in a political (or social) climate that rewards backing everything that the tech industry does. Texas is now a thoroughly blue state outside of the state senate, where Republicans still hold a thin majority and are already desperately trying to undermine the powers of the lieutenant-governor before Vikki Goodwin takes over in January, which spells ill for the 57.7GW of planned IT capacity in the state, more than half of which is being built by first-time developers per Bloomberg. Thirty-three separate ballot measures to restrict data centers were passed by voters or were leading as of writing this sentence per Stateline, with 21 municipalities in Ohio alone (one of the fastest-growing data center buildout geographies in the world) voting to restrict them. According to Bloomberg, “...[the] gubernatorial races from Georgia to Ohio and Pennsylvania could leave half of proposed AI data center additions across the US vulnerable to stricter local scrutiny and pushback.”
In 12 states, the winning or leading candidate for governor has called for a pause on data center development, including Alaska, Georgia, Kansas, Maine, Michigan, New Hampshire, New Mexico, New York, Ohio, Oregon, Texas and Wisconsin. And in even more states, winners have also pledged other restrictions on data centers including ratepayer protections, environmental limits and the elimination of tax incentives for building the facilities.
And of the 24 incoming governors who did not call for a pause, 22 back at least one limit on data centers. Ratepayer protections, which would make sure households don’t shoulder the costs of increased power demand or energy infrastructure buildouts, were nearly universal: 34 of 36 winners support them. And 27 back restrictions relating to water usage or the environment.
It turns out that people hate data centers, are enraged with the tech industry, are tired of Elon Musk, and don’t want to feel like they are under the thumb of billionaires. The AI industry accidentally created the single-easiest bipartisan talking point by force-feeding rural communities giant, expensive monoliths explicitly built to take their jobs, and now face outright opposition in effectively every state other than the Dakotas, with little or no response other than “uhh, having data centers makes America stronger.”
The hubris of the AI bubble is the belief that it could continue to grow unfettered without seeking the consent of those who have to live with its consequences. The AI bubble threatens to take the jobs of working people, to degrade their working conditions, to increase the cost of living, and to force them to live next to noisy, fume-polluting monstrosities — and those most responsible for the existence of that bubble believe that those most keenly affected by the consequences of the technology and the infrastructure must either meekly acquiesce to their will, or will ultimately come to accept the better wisdom of Altman, Musk, Amodei, et al.
Those responsible for the profligate splurge in AI-related spending didn’t anticipate that people — voters — would and could say no. And they absolutely fucking did, and in doing so, exposed a vulnerability in the AI bubble that I (and many others) have failed to cover with the due attention it deserved.
The AI bubble is only made possible in a climate of unrestrained capitalism. NVIDIA’s growth is entirely dependent on an unimpeded data center buildout, and without it, there’s little reason to keep buying tens of billions of dollars of GPUs every quarter. Without more capacity, Anthropic, OpenAI and other AI labs are unable to sell their stories based on infinite growth.
And once that narrative sets in, everything begins to implode.
So, as promised, today’s newsletter is about some of the markets, industries and companies most-exposed to the AI data center capex bubble bursting, the data points to watch closely for signs of collapse, and the things that might cause things to finally fall apart.
2026-11-04 01:16:20
If you haven’t subscribed to Where’s Your Ed At, now’s the best time. I’ve extended the sale — 10% off of the $70-a-year subscription for life (click here!) — for new subscribers for another week. It’s a great way to support my work, and you get an absolute ton of value at a lower price than basically every competing newsletter.
Over the past few months, I’ve published a two part guide to the world of AI debt, an analysis of the (dubious) impact of generative AI on the global economy, deep analyses of the biggest players in the AI infrastructure space like NVIDIA (part one and two) and Oracle (part one and two), how OpenAI will eventually kill Oracle, and how venture capital is killing itself.
Friday's piece is about fault lines - the areas most-exposed to the collapse of the AI bubble, the datapoints to watch to see the industry's deterioration, and what might cause things to fall apart.
If you want to get in touch — and especially if you have any juicy information about Anthropic, OpenAI, Blackstone or any other companies in the AI bubble — hit me up on Signal at ezitron.76. I’m also on IB on your Bloomberg Terminal.
As I’ve said for a while, all of this ends when the money runs out — when seemingly-unlimited data center debt becomes distressingly hard to raise, and when AI startups can’t rely on the perpetual availability of venture capital to keep them alive.
And it appears the well is running dry, just as it dawns on everyone that the underlying economics of AI, for labs and data center operators alike, don’t really make sense.
On September 16, 2026, the New York Times would report that OpenAI was “considering” a new funding round valuing it at $1.5 trillion, a little under three months after it delayed its IPO to 2027. Ten days later on September 29, Bloomberg would report that it was aiming to raise $30 billion at a $1.4 trillion valuation, and on October 5 revealed that it was in talks with BlackRock, a syndicate, and funds from the UAE which had “discussed putting in as much as $10 billion altogether.”
Last week — less than a month later — OpenAI raised $11 billion at a $1.25 trillion valuation “after receiving tepid interest from some large investments,” per the Wall Street Journal, who added that OpenAI had “...told shareholders it expects to try to raise more money…[and hoped] to raise up to $20 billion,” targeting “family offices and high net-worth individuals,” which means that sovereign wealth funds, venture capitalists, and private credit firms have given all they’re willing to.
Per The Information, OpenAI spent a total of $12.1 billion across its cost of revenue and research and development segments in Q1 2026, and per Microsoft’s own earnings, OpenAI’s compute spend and revenue share payments contributed $10 billion in revenue to its latest fiscal quarter.
In other words, that $11 billion round won’t even cover a quarter of OpenAI’s compute costs, and it’s fair to ask both why this round had to close right now and what exactly the company does going forward.
Per the same Information story, OpenAI ended Q1 2026 (so March 31, 2026) with “more than” $73 billion in cash and marketable securities. Revenue grew tepidly from $5.7 billion in Q1 to $6.7 billion in Q2 2026 (per the WSJ), and since then, Amazon has sent OpenAI $35 billion (around July 31, 2026) and SoftBank $30 billion (wired in April, July and October).
If OpenAI needed a paltry $11 billion, it’s likely that it raised it either out of some degree of desperation and/or an attempt to catch up with an Anthropic IPO that investors are now expecting to, per Bloomberg, price at $1.4 trillion to $1.5 trillion, down from less than a month ago when it was expected to price at $2 trillion or more. Anthropic is now, per the WSJ, being “urged by institutional investors to target a lower valuation of $1.5 trillion to $1.6 trillion.”
It is extremely bad that OpenAI raised at a lower valuation than planned, and even worse that it couldn’t raise as much as it wanted (needed?) at said valuation. In the absolute best case scenario, this was an attempt by OpenAI to bump its valuation up from its $852 billion par from March, I imagine to make its investors feel better about Anthropic’s upcoming IPO…potentially? The problem is that at $1.25 trillion, OpenAI would have to eventually go public at a $1.5 trillion or $2 trillion valuation to give its latest investors anything close to a positive return, at a time when Anthropic has already seen its expected market capitalization tank by hundreds of billions of dollars.
I think the answer is probably somewhere in the middle — OpenAI needed this money, needed to feel competitive with Anthropic, and realized that it should raise as much money as possible before the capital markets slam shut.
The question I ask is simple: what the hell does OpenAI do next?
At $1.25 trillion (as mentioned above), OpenAI would need a much better listing price than Anthropic is expected to have, for a company with objectively worse metrics, including slower growth, lower revenue, higher costs, and hundreds of millions of free users that generate, at best, about a billion dollars in “annualized” ad revenue against the billions of dollars it costs to serve their compute. Despite all the buzz around GPT-6 Astra — which was, according to NVIDIA’s Jensen Huang, “AGI” — it’s clear that its effect on revenues was insufficient to excite even the cash-rich and hype-friendly investors in the Gulf.
GPT-6 Astra was, I believe, expected to be the lipstick on an unmistakably feculent pig of a company — something that’ll disguise the horrendous fundamentals of OpenAI’s business and energize investors — and, based on its disappointing latest funding round, it failed. And I believe that things will get worse from here.
OpenAI will absolutely, without a doubt, need more money in the next few months, and will need to raise at some sort of valuation, one calculated based on both that $1.25 trillion valuation and the performance of Anthropic’s IPO.
Making things a little more challenging is the Financial Times’ report that Blackstone has told some investors that Anthropic “may not receive an investment-grade rating immediately after going public,” otherwise known as a junk rating, a point I made about a month ago based on the fact that it’s a negative-EBITDA company.
While we don’t know what the rating will be — as the big three (Moody’s, S&P and Fitch) are yet to rule — Anthropic’s $35 billion Broadcom-backstopped deal to lease TPUs received a BB+ rating from KBRA a few months ago, which is one rung below investment grade, but I must be clear that $30bn of the deal is backstopped by a company with a high investment-grade credit rating.
While inevitable, a below-investment grade rating essentially puts Anthropic’s debt outside the reach of the most prolific bond-buyers, like pension funds and insurers. And again, I couldn’t see this going any other way, but I would argue that this rating represents a psychological cold shower for investors — a reminder that this space is, using the most charitable language at my disposal, inherently speculative and rife with risk. Given that OpenAI’s past and future fundraising is contingent upon an investor class that’s drunk on exuberance and that has lost its senses, cold showers are a very bad thing.
OpenAI is a company with higher expenses, lower revenues, and the stench of an also-ran that got beaten by an aggressive competitor gunning at full speed to beat it to IPO, leaving it with few options outside of increasingly-illogical-yet-existential funding rounds that either scrape the bottom of the VC barrel or force it to take a down round to get cash through the door. Future investors will have to believe, somehow, that OpenAI will both actually go public and one day be worth $2 trillion to $3 trillion, as well as somehow being able to raise hundreds of billions of dollars of debt to keep up with its $750 billion in planned cloud spend through 2030.
And given that junk rating and the grim new data from Anthropic’s newly-amended S1 (called an S1/A), it’s unclear how any of this is actually meant to work.
Let’s be clear about something: it only took a week for Anthropic to file an amended S/1 to include its Q3 numbers, which means (in my opinion) it was absolutely ready to go for the initial filing but chose to intentionally leave those numbers out.
You’re about to find out why.
As I discussed last week, Anthropic’s initial S-1 filing — covering up to Q2 2026 — described a company that effectively no longer exists, with a “profit” driven by discounted SpaceX compute, $2.08 in revenue for every dollar of compute spend, $11.5 billion in revenue, and $430 billion in non-cancellable compute commitments, including a $161.2 billion deal with Broadcom to lease Google’s TPU chips at a remarkable scale.
Though we already knew some of the Q3 numbers thanks to the Financial Times’ reporting around Anthropic’s investor day, boosters and the otherwise cope-poisoned chose to do several consecutive victory laps, claiming that this was proof that A) Anthropic was a “profitable company” and B) that “the economics of generative AI work.”
As I said at the time, this quarter was an anomaly caused by organizations allowing their workers to spend as much as they want on tokens, leading to companies like Uber burning their entire annual token budget in the space of a quarter and much hand-wringing around AI’s ROI:
The era of token-maxxing — when companies like Meta incentivized their employees to burn as many tokens as possible, only to pull back after costs skyrocketed — ended somewhere in Q2 or Q3 2026, which is why Anthropic is so keen to push this company out the door, ideally before you learn too much about its latest quarter or how much its ongoing expenses might be.
In other words, Anthropic deliberately filed less information as a means of misleading the public into believing it was a fast, lean, profitable company with remarkably low compute costs and a large — yet indeterminately-timed — pile of obligations.
Having read the amended filing, I kinda get why it did so.
As part of its original filing, Anthropic included this delightful diagram of its “revenue per dollar of compute” — but left out Q3 numbers that we already know it had (because the Financial Times reported them weeks ago) for the obvious reason that its economics got worse.
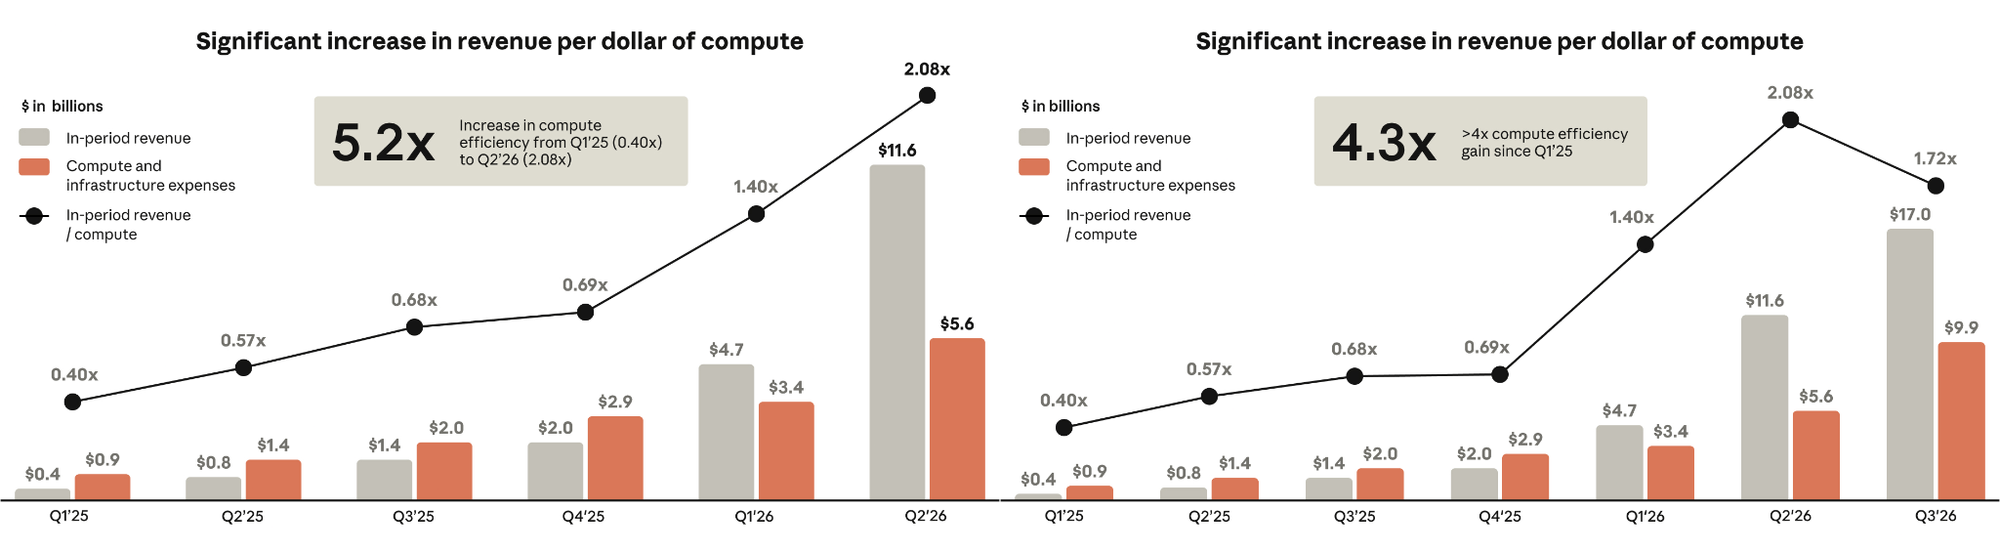
While revenue grew about 46.9% ($11.5 billion to a little under $17 billion) quarter-over-quarter, compute costs nearly doubled from $5.6bn to $9.9bn (about 77.4%). This was partially driven by the fact that, per Bloomberg, Anthropic’s compute spend made up 34.5% — around $5.028 billion — of SpaceX’s Q3 revenue, making it Musk’s largest customer.
Sidenote: I’ll also add that Anthropic’s compute costs still, to this day, do not make sense in comparison to those borne by OpenAI and basically every other company renting GPUs and TPUs. While it still lost $567 million in Q3 (and had a negative 3% operating margin) it only spent $4.9 billion on compute (outside of SpaceX) across Google, and Amazon, despite Amazon opening an entire data center in Indiana for it last year and signing a deal worth “tens of billions of dollars” with Google in October 2025 that would “bring over a gigawatt of capacity online in 2026.”
As I reported a year ago, OpenAI — in a year where it made $13.01 billion in revenue — spent $3.64 billion on inference in Q3 2025. While it still had the burden of the free Sora app at this time, not to mention its free users, I find it hard to understand the significant gap between the companies’ costs, and do not buy that Anthropic has some super secret sauce that makes it significantly more efficient than OpenAI to the extent that we see in the numbers.
Per my own reporting on Anthropic’s Amazon Web Services bills from 2025, Anthropic spent $1.225 billion on AWS alone in Q3 2025, in a quarter that (per the S-1) had a total of $2.047 billion in compute costs, leaving about $1.71 billion in costs in that 9 month period unaccounted for, likely going to Google Cloud.
If I had to guess, Anthropic likely — as it’s mentioned it does — pre-bought capacity at discounted rates from Google and Amazon on sweetheart deals that are either running out or have run out this year. For example, UBS’ Stephen Ju cited in a note from earlier in the year that Anthropic had a deal to pay Google a mere $1.25 billion in annual revenue outside of a $25 billion commitment to TPUs, and another agreement beginning in FY2027 at $6.25 billion a quarter.
I guess we’ll never know, unless one of you wants to share Anthropic’s Google Cloud or Amazon Web Services spend! Ezitron.76 on Signal.
Anyway, Anthropic also filled in that contractual obligations chart, showing a minimum of $319.9 billion in payments through the end of 2030.
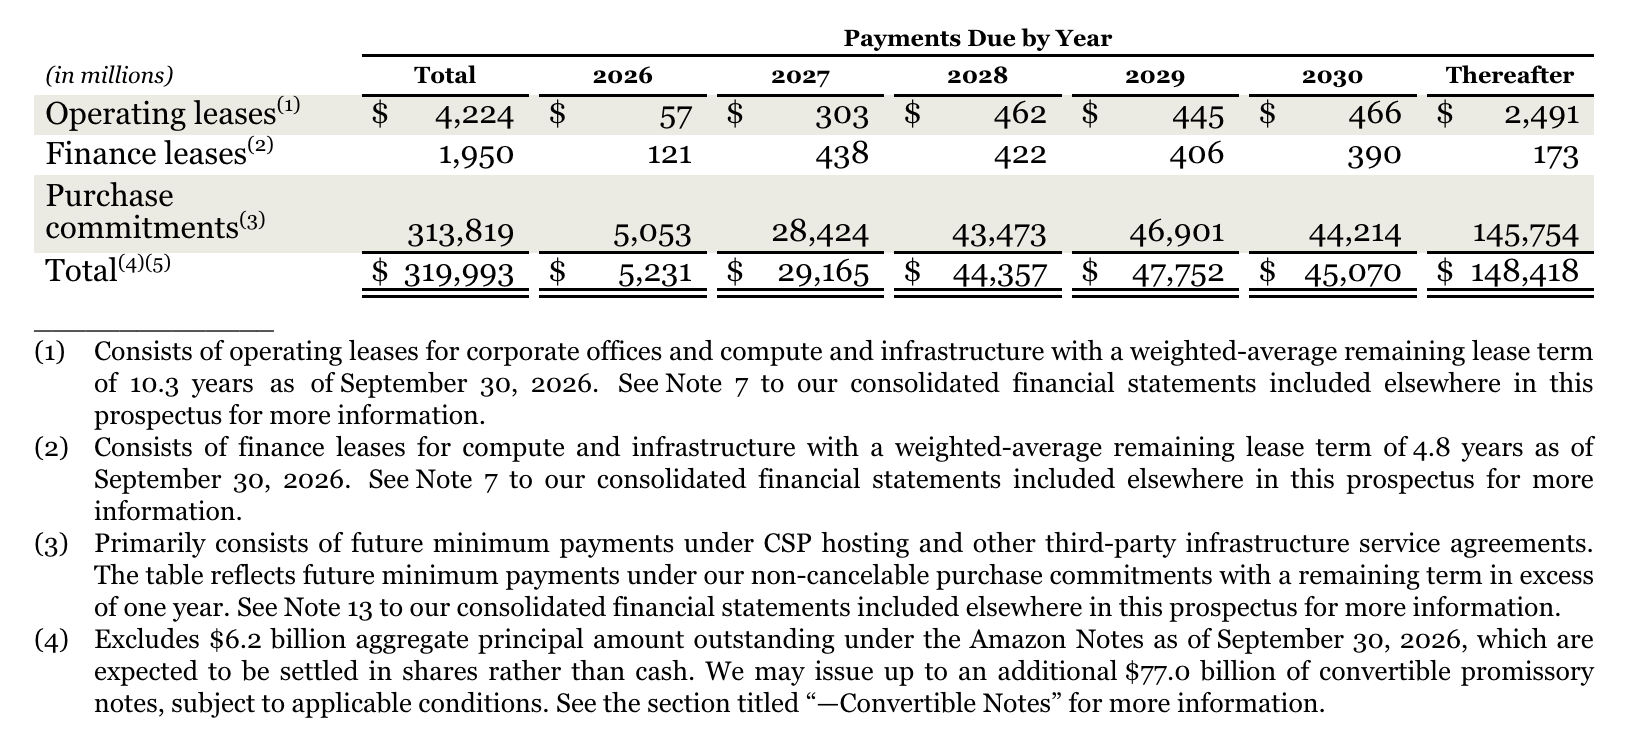
Yet before anyone starts suggesting that Anthropic has fewer obligations than we thought, it immediately goes on to add that there are $451.2 billion in leases yet to commence…
Further, the table above does not include leases executed and not yet commenced as of September 30, 2026, with total estimated future undiscounted lease obligations of approximately $451.2 billion. Generally, these lease obligations are expected to commence between 2026 and 2028, with lease terms ranging from less than one year to 20 years, with a weighted-average term of approximately 10 years.
…and, for whatever reason, leaves out over $100.2 billion in future obligations to hyperscalers and data center lessors, as well as “certain agreements that are short-term in nature” with a minimum spend of $6.6 billion.
In addition, the table above does not reflect commitments entered into after September 30, 2026, with aggregate future minimum payment obligations of approximately $100.2 billion, primarily consisting of data center leases and CSP hosting and other third-party infrastructure service agreements. We also entered into certain agreements after September 30, 2026 that are short-term in nature. Minimum payments under such contracts are approximately $6.6 billion. See Note 17 to our consolidated financial statements included elsewhere in this prospectus for more information on commitments entered into subsequent to September 30, 2026.
Anthropic does add that it expects to pay $69.8 billion of its contractual obligations in the 12 months starting October 1, 2026 — meaning Q4 2026 — which makes that “$29.1 billion in payments due by year” number extremely suspicious, to the point that it almost feels like Anthropic intentionally wants readers to get the wrong idea about the company.
I mean, I get it! Anthropic wants to sell itself as this fast-growing, lean, “profitable” AI lab that has worked out the messy economics of generative AI, when in fact it’s an overweight hog with nearly a trillion dollars’ worth of commitments, $437.4 billion of which are non-cancellable.
Just to review, that’s…
Yet even then, there’s potentially hundreds of billions of dollars more in compute commitments that Anthropic vaguely describes, the first being underneath that chart in a footnote, emphasis mine:
Excludes certain other compute and infrastructure arrangements that do not specify a fixed dollar commitment which are not included in the aggregate above. Payments under these arrangements will depend on the capacity made available and deployed, delivery timing, pricing mechanics, and the satisfaction, or our waiver, of certain other deployment conditions. Because these factors are not yet determinable, the total amount of payments under these arrangements is uncertain, but we currently estimate such payments to be approximately $150 billion to $175 billion. We expect these amounts to be payable over time after the capacity is delivered.
No worries dude! Just $150 billion in compute commitments that might happen at some point or another with no explanation as to who the commitments are to, what they’re for, and when they might begin, other than that they might be part of a deal with a hyperscaler!
Say, talking about hyperscalers, Anthropic also apparently has another massive commitment to lease TPUs — apparently separate to the Broadcom deal! — that may or may not be worth as much as $125 billion to $150 billion, and deliver sometime in the next two to five years:
In addition, we also committed to procure additional TPU compute, without a fixed dollar commitment, via one of various delivery methods, including either a CSP hosting agreement with Google, direct purchase from Google with five-year financing, or direct purchase and/or lease from a third-party TPU provider with five-year financing. Such compute is expected to be delivered between 2028 and 2031 and the associated payment obligations are determined by the capacity made available, the delivery method, and the pricing and financing mechanics. We estimate the aggregate future payments for such additional compute to be approximately $125.0 billion to $150.0 billion, which are not included in the contractual obligations table above.
So, yeah, just another $300 billion or so of commitments on top of the others, disclosed in an opaque — and I’d argue deceptive — way.
But that’s just how Anthropic (and its former Blackstone private equity CFO) rolls. Anthropic wants to con as many retail investors — via the media, of course — into believing that this is a company that will only spend $30 billion on compute in 2027, and will somehow grow to meet its ridiculous, ever-expanding costs.
Underneath the quarterly trends section of the S/1A, Anthropic added an entire paragraph underneath “quarterly revenue trends” on page 161 (158 in the original S-1):
For the three months ended September 30, 2025 to the three months ended December 31, 2025, the increase in revenue due to higher usage was partially offset by a decrease of approximately $70 million from price reductions introduced as part of new model versions and contractual discounts. For the three months ended June 30, 2026 to the three months ended September 30, 2026, the increase in revenue due to higher usage was partially offset by a decrease of approximately $600 million from price reductions introduced as part of new model versions and contractual discounts.
In other words, for every dollar that Anthropic makes, it’s cutting that by 3.4% or so via discounts, a fact it’s only including as a means of key-jingling for boosters to say “actually revenue would be so much higher, if…” even though this number doesn’t really tell us very much about Anthropic’s business. Are these discounts for enterprises buying tokens direct? What were the discounts in Q1 and Q2 2026? Don’t worry about it man, these numbers are not here for you to learn more about Anthropic, they’re about making sure you invest in it.
Anthropic’s cash position is one of the weirdest things I’ve seen in a company, and I’ll explain why with this quote from economist Paul Kedrosky when he dug into its original filing, where he called it “a bank with a money-losing AI side gig”:
Anthropic held $112 billion in cash and equivalents at June 30, plus another $19 billion in short-term investments. It generated $1.1 billion in interest income on that balance in the six months. Granted, this won't get you a gig at PIMCO or Doubleline, but it is massive.
To put in context, Anthropic's interest income is larger than their operating losses of $700m+. It is also larger than many regional U.S. banks. While the interest income provides a cushion beneath operating losses, it doesn't change underlying operating economics. For now, being well-funded is itself a meaningful source of earnings. That benefit will go to zero as the cash gets spent.
In Q3, Anthropic’s cash position is largely left unchanged, with $16.8bn in cash and cash equivalents turning into another $17 billion in short-term investments (US Treasuries and securities), generating $1.248 billion in interest — a savvy move to generate capital for a company destined to burn billions of dollars in increasing intervals.
And the problem for anyone trying to digest this S-1/A is that there’s very little guidance as to how that might actually happen.
Let’s go back to the top of page 6:
These commitments include approximately $447.5 billion expected to be incurred before December 31, 2030, and substantially all of the remainder is expected to be incurred between 2031 and 2045. Approximately $69.8 billion of these commitments are due in the 12 months following September 30, 2026.
Now, that $69.8 billion could, in theory, include some of SpaceX’s $3.1 billion a month in compute costs — which are, of course, “short-term leases” that can be exited with 90 days of notice — but it’s impossible to tell thanks to this insipid company’s weasel wording. There’s also a compelling argument that it only includes a quarter’s worth, which would add another $27.9 billion on top of the $69.8 billion in the event that Anthropic used it for the entire year.
Nevertheless, Anthropic has a remarkable amount of compute commitments, and itself admits that it will have to cough up as much as $447 billion in costs in the next four years, and unlike previous years, it’ll have to pay for it up front in big, ugly chunks.
In Anthropic’s own words, it “expects an increasing portion of [its] compute and infrastructure investment to take the form of capital expenditures and other commitments,,” and that said commitments require “significant upfront payments well in advance of the related compute becoming operational.”
While one might be tempted to say that its current liquidity — about $95.5 billion in cash and $36.2 billion in short-term investments — in addition to potentially raising $100 billion at IPO might be enough to get it by for years, even Anthropic suggests that might not be the case:
We believe our existing available cash and cash equivalents, short-term investments, together with cash generated from sales and amounts available under our A&R Credit Facility, will be sufficient to support working capital, operating and finance lease payments, and capital expenditure requirements for at least the next 12 months from the date of this prospectus.
However, our future capital requirements will depend on many factors, including our revenue growth, the timing and extent of our investments in compute and infrastructure capacity, including additional or expanded CSP, equipment lease, and data center arrangements, the success and expansion of our sales, marketing, and business development strategies.
This suggests that fairly soon Anthropic will have to send a significant amount of cash out the door in the form of pre-payments, on top of the fact that it’ll be spending $9.3 billion a quarter, without fail, on SpaceX’s compute, assuming that that agreement doesn’t expand any further.
This leaves Anthropic in a worrying position where the only guarantees it has are that its costs will expand dramatically, every single year without fail. While revenue growth might continue (though Ramp, which was accurate with its predictions of Anthropic’s Q3 growth, now expects its Q4 numbers to be far more modest, ranging between 15% and 25%), said growth now has to compete with hard, inflexible costs regardless of any seasonal shifts, price increases (or decreases) or product changes that might hamper growth, and with the sheer scale of these costs, any mismatch between compute spend and revenues will cost the company billions of dollars.
And then there’s the problem of that junk rating. While we still don’t know what level of junk rating the agencies might award it, Anthropic is all but certain to have to raise debt in the 8% to 11% range — the kind of interest rate that can veer between harsh and unmanageable when you face rough headwinds, especially when you’re raising debt in the tens of billions.
Anthropic’s current obligations are priced for perfection, requiring the company to, by this time next year, be roughly twice its size and continuing at a similar (or better) growth rate, because the sheer scale of its compute commitments demands Anthropic maintains both perpetual growth and improved margins.
It is not enough for this company to be the fastest growing startup of all time — it must also be attractive enough as a potential debtor to appeal to an already-strained junk debt market, which will require it to become a better, stronger company in stark economic terms unrelated to any hype around AI, especially as Wall Street becomes, to quote the WSJ, “choosier about where to place their bets and are demanding tougher terms.”
To be clear, that’s referring to AI data centers that have physical infrastructure and actual assets rather than a negative-EBITDA software company with a very annoying CEO.
While Anthropic’s cash pile might make lenders a little bit calmer, we still have very little clarity as to the size and velocity of its prepayments, which makes it difficult to tell how big that cash pile might be in three, six or twelve months.
My question is simple: what happens when Anthropic’s revenue growth stalls as its costs naturally increase as capacity comes online? It’s deeply unattractive to lenders to say “well, we made all these commitments to pay hundreds of billions of dollars and it turns out our revenue growth slowed down, can you lend us money to cover the gap?” While in theory that might work, it’s the kind of thing that makes a lender ask “are you concerned about defaults?” or “what happened to all that cash you had?”
As discussed last week, around 80% of OpenAI and Anthropic’s revenues come from venture backed startups that (as I’ll get to at the end) heavily subsidize their userbases, which means that growth is mostly tied to whether VC can continue funding its customers.
And as I discussed a few weeks ago, Anthropic will, outside of the very highest rung of junk, be limited in how much debt it can actually take on, and if it needs (as I estimate) around $50 billion a year, it’s hard to see how it pulls that off.
It’s getting dark outside, whether boosters will admit it or not.
While its rush toward IPO was arguably driven by its anomalous second quarter, Anthropic has also realized that the music is stopping, and everybody is beginning to ask worrying questions about the underlying economics that I was asking years ago.
Everything started to accelerate last week off the back of Anthropic’s S-1. The day before it was filed, Elon Musk closed a $40 billion debt deal to buy NVIDIA chips with interest rates for some parts of it as high as 8.75% per Semafor. A day later, Musk claimed that the markets had begun to shut out neoclouds entirely, per CNBC:
“As of the past few weeks, debt markets have almost entirely shut off access to money for any company that doesn’t have substantial revenue independent of AI data centers,” Musk, CEO of SpaceX and Tesla, said on a post on X on Sunday. “That means the 200+ neoclouds are going to see guppy-level death and consolidation. Some will make it through, but not many,” he added.
A few days later, the Wall Street Journal would report that the markets have begun rejecting neoclouds:
The new terms of trade are visible in every corner of markets. Bonds issued even by big tech companies such as SpaceX and Meta are trading at steep discounts. AI cloud companies such as CoreWeave, Nebius and Nscale that borrow big to build and sell capacity have effectively been shut out of the bond market in recent weeks, people familiar with the matter said.
It’s unclear how CoreWeave, which needs over $100 billion in debt through 2030 per Morgan Stanley, actually survives, let alone the gaggle of yet-to-IPO neoclouds like Firmus or Lambda make it through 2027. Their overstuffed backlogs and highfalutin revenue growth promises are no longer impressing anyone.
More tellingly, the mood around neoclouds have shifted — demonstrated most vividly by a piece published by the BBC’s North America technology correspondent Lily Jamali over the weekend, which essentially talked about the growing skepticism about the long-term health of neoclouds on Wall Street, and noted that many (in particular, Coreweave) have racked up debts that they really shouldn’t have been able to.
Neocloud firms often finance themselves by signing long-term lease contracts with major tech customers who need quick access to computing power.
Firms can then borrow money using those contracts – plus the AI chips they purchase – as collateral, explained analyst Cory Johnson of "The Quiet Period" IPO research outfit.
He said debt is common across neocloud firms because the hardware has to be paid for up front.
Take the industry leader: CoreWeave. It's a fraction of the size of some of the Big Tech companies it serves.
But Johnson believes lenders sometimes consider the creditworthiness of CoreWeave's customers, like Microsoft or Meta, more than the company's when they lend.
"This helps explain how CoreWeave accumulated $35.1bn (£26.3bn) in debt," he said.
I’ll simply note that I raised the alarm on Coreweave in March of last year (nearly 18 months ago), and many of the points that the article makes are ones that I’ve been raising in this newsletter ever since. In short, fears around neoclouds are now mainstream.
And while hyperscalers might still have been able to raise debt this week, last week’s earnings have thoroughly panicked Wall Street.
The same week, Amazon and Google both had double-misses on earnings, with only their cloud businesses — which are inflated by billions of dollars of compute spend from both Anthropic and OpenAI — showing any exciting growth.
Per page F-16 of the amended S-1, 44% of Anthropic’s revenue (around $14.6 billion) for the first three quarters of the year came from Google and Amazon (and Microsoft to a lesser extent) selling its models through Vertex and Bedrock, which means both have seen billions of dollars of extra revenue both from selling Anthropic’s models and providing it with compute to deliver them.
In other words, in 2026, Anthropic got $10 billion in funding from Google, $5 billion in funding from Amazon, then spent billions of dollars on both Google Cloud and AWS to serve compute to sell access to models, which the hyperscalers then booked as revenue, on top of the revenue the hyperscalers booked from selling those models, which (due to the unique way that Anthropic itemizes its revenues) Amazon, Google and Anthropic all book as their own revenue.
While Amazon could explain away a bad quarter as a function of a flailing economy with spiralling inflation, Google had far grimmer news — that its use of AI overviews had led to “lower monetization” of search, meaning that despite spending hundreds of billions of dollars on AI, the only tangible effect appeared to be weakening the core product and creating a dependency on a pair of unsustainable, unprofitable AI labs.
As a result, Google had its single-worst day of trading in history.
While Microsoft beat expectations, it did so at a gruesome cost — as mentioned earlier, OpenAI’s compute spend and revenue share payments contributed $10 billion in revenue to its latest fiscal quarter, or almost 11% of its quarterly revenues.
This is extremely bad in a way that I’m surprised more people aren’t discussing. Per Bloomberg earlier in the year, OpenAI accounted for around 7% of Microsoft’s Fiscal Year 2026 revenues, or around 70% ($24.1 billion) of AI revenues. Within a single quarter, OpenAI has already accounted for nearly half of its last fiscal year contribution to Microsoft, with its concentration of overall revenues growing at an alarming rate at a time when, as discussed, the company is having trouble raising money to pay its bills.
There’s also the messy issue of Microsoft’s new revenue disclosures, announced back in September, that mean that we now know the quarterly revenue of its Azure cloud platform, which was an impressive-seeming $33.2 billion in its latest quarter until you, as nobody appears to have done, compare it to the $29.4 billion it made in Q4 FY2026.
That $3.8 billion in revenue growth is most-assuredly from OpenAI’s increased compute spend, especially given the dramatic jump from the end of the last fiscal year. If that’s the case, Microsoft’s “impressive earnings beat” is far more a function of OpenAI’s cash furnace than any success of its AI plays — especially as Microsoft neglected to update us on paid Copilot licenses outside of claiming that “Copilot daily users grew nearly 50% in the three months to September,” the kind of thing you tell an audience you are convinced is too stupid to see through your bullshit.
And just when we thought we’d escaped the fearmongering of a shitty earnings season, Uncle Elon decided to say the worst thing possible as users complained about their weekly usage of “Grok Bot” suddenly evaporating, per TechCrunch:
SpaceX CEO Elon Musk confirmed in an X post on Sunday that this was not a glitch.
“The cost of serving Grok Bot was unsustainably high relative to revenue,” he wrote in a reply to a question from a user. He has not addressed the issue on his main feed but has continued boasting that Grok Bot can help you buy gifts for your family.
Musk, who had said three days beforehand that saving money for the distant future was pointless with the advent of “super intelligent abundance,” added that these changes (which have yet to be fully defined) are a result of him “just being sensible.”
Sidenote: The cost of running any kind of “agentic” service like Grok Bot is also much, much higher, as on top of the cost of inference, each one of them is given a virtual machine with an allocation of RAM and storage, and can spin up multiple different LLMs at once to work on a problem, with the underlying orchestration of all their actions (EG: connecting to APIs, databases, web searches, using applications) putting a heavy burden on the CPU.
Considering most AI services are billed on a monthly basis — and services like Muse and Instinct are free — these “agentic” features are a brand new infrastructural cost layer above and beyond the regular costs of LLMs. It’s a testament to the stupid amount of compute power necessary to get these things to do anything close to what we were promised with ‘agents’ over the last few years, and even then the results are mediocre.
This freaked out the entire AI industry, because they realized, as I warned two years ago (and revisited again in March), that the vast majority of AI subscriptions are heavily subsidized, letting users burn several dollars’ worth of tokens for every dollar worth of subscription and eating the costs to get them through the door, only to rugpull them the months or years to follow as the company in question tries to pull costs in. This all began in June last year when Anthropic and OpenAI forced AI startups dependent on their models to start paying priority processing fees.
A few hours later, Replit CEO Amjad Masad gave a dire warning: that if you’re enjoying a subsidized AI subscription [you should] get ready to get rug pulled.
After all, Masad would know — shortly following the June 2025 changes to priority processing, Replit introduced “Effort-Based Pricing” that jacked up pricing for users, a problem made worse by the launch of its “Agent 3” product a few months later, per The Register:
Part of the problem might be with Replit's June introduction of "effort-based pricing.Previously, it would charge $0.25 for each checkpoint, and a task with multiple checkpoints would simply be tallied up one by one to arrive at a total cost. But with effort-based pricing, it now bundles complicated tasks into a single more expensive checkpoint. The next month, Replit admitted "can end up being more expensive over the lifetime of a project." But the costs didn't really seem to hit users until Agent 3.
"The effort-based pricing never ran me as much before but Agent 3 has been exceptionally high," explained the user we spoke to.
A short trip to the Replit Subreddit is all it takes to find unhappy customers, but my own thread soliciting experiences about effort-based pricing led to arguably the most damning response that, well, uses exactly the word that Masad chose:
Replit's new pricing is just the latest rug pull in a long line of half-baked rollouts. I’ve spent months building serious infrastructure on their platform—AI-driven automation, multi-role dashboards, recursive agent logic. What I got in return? An unstable, overpriced Agent that breaks more than it builds.
…
And now they’ve changed pricing again—with no warning—making it even less predictable. Their “effort-based” system means you can get charged more for the Agent’s failure loops than if you wrote it yourself. I’ve seen single-line fixes priced higher than full feature requests—and that’s assuming it even finishes.
Masad claimed in another post that Replit was “never subsidized,” something that you’d only say if you had a deep distaste for the truth.
Per The Information from August 2025, emphasis mine:
For Replit and other coding startups, one of the biggest factors weighing on their gross margins is the fees they pay every time their assistants access large language models developed by Anthropic and others. Replit, which targets professionals without coding backgrounds, includes payments for Anthropic’s Claude models and Google Gemini models, as well as cloud computing costs to deliver its products, in the cost of its revenue.
In February, as revenue surged, Replit’s gross margins hit 36%. Then they fell to negative 14% in April when the company launched a new version of its agent product, which was more autonomous and spent more accessing large language models than the prior version.
As a result, the company repriced the product—charging for the amount of time and compute used for the agent to complete a task rather than for each completed request—to account for the additional costs. In July, the margins bounced back to 23%.
Riddle me this, Batman: what do you call it when a company sells a service at a price that does not cover its costs, absorbing said costs to retain the customer? I’m sure he has some sort of mental gymnastics routine where he considers that spend to be “marketing costs,” but we all know what actually happened.
Sidenote: Have you ever noticed how fucking dishonest this entire industry is? Perhaps this’ll be next week’s free newsletter, but it feels like AI is just a series of different scams — the obfuscated economics, the weasel wording around everything from revenues to how much actual capacity companies have, subsidized subscriptions that literally sell customers on a lie, it’s all so fucking grotesque! I hate it! Everyone involved should be ashamed of themselves!
In any case, I 100% believe Masad when he says that rugpulls are coming. A recent update to OpenAI's ChatGPT and Codex usage limits page revealed that starting in December, users’ use of chat and coding functionality will draw from the same rate limits (which had been largely separated to this point) and that said usage will “be measured in tokens,” suggesting that OpenAI’s subsidized subscriptions are coming to an end.
And I imagine this problem will flow throughout the industry as venture capital dries up.
I think I get asked five times a week when this all ends, and I truly cannot answer you and, as some of you have noticed, get criticized for having tried to guess in the past.
What I can tell you is that the bubble bursts when the money runs out.
The signs are already there — OpenAI struggling to raise, Musk tightening rate limits on Grok Bot, debt markets shutting out neoclouds, Anthropic’s lower valuation and increasing scrutiny — and will only get increasingly-louder and more-deranged as things get desperate.
And now I’m even hearing low rumblings of a compute glut, with AI startups buying compute on the off-chance they might need it, assuming wrongheadedly that if they don’t they can sell it at a premium.
You know, kind of like how people said in 2006 that if they’d just refinance their mortgage.
After all, the price of housing never goes down.
If you haven’t subscribed to Where’s Your Ed At, now’s the best time. I’ve extended the sale — 10% off of the $70-a-year subscription for life (click here!) — for new subscribers for another week. It’s a great way to support my work, and you get an absolute ton of value at a lower price than basically every competing newsletter.
If you want to get in touch — and especially if you have any juicy information about Anthropic, OpenAI, Blackstone or any other companies in the AI bubble — hit me up on Signal at ezitron.76. I’m also on IB on your Bloomberg Terminal.
2026-10-29 01:51:00
I’m taking a week off of premium as I’ve had a family situation that has absorbed a lot of my time this week, but I’ll be back with a barnburner next Friday (11/6).
In the interim, I’m running a week-long sale — 10% off of the $70-a-year subscription for life (click here!) — for new subscribers. It’s a great way to support my work, and you get an absolute ton of value at a lower price than basically every competing newsletter.
Over the past few months, I’ve published a two part guide to the world of AI debt, an analysis of the (dubious) impact of generative AI on the global economy, deep analyses of the biggest players in the AI infrastructure space like NVIDIA (part one and two) and Oracle (part one and two), how OpenAI will eventually kill Oracle, and how venture capital is killing itself.
If you want to get in touch — and especially if you have any juicy information about Anthropic, OpenAI, Blackstone or any other companies in the AI bubble — hit me up on Signal at ezitron.76. I’m also on IB on your Bloomberg Terminal.
Last week, I opened my newsletter with a quote from Apollo Chief Economist Torsten Slok, and forgive me, I’m going to have to do so again, emphases his:
Despite massive investments and widespread hype around artificial intelligence, the technology has delivered zero financial payoff to corporate America outside of tech. Revenue per worker is rising for the Mag 7 but is flat for the S&P 493, see the first chart below. Profit margins are rising for the Mag 7 but are flat for the S&P 493, see the second chart below. And there are still no signs of AI boosting productivity growth, see the third chart below. With no impact on the bottom line, mainstream corporate America is pulling back and starting to view token spending not as a source of growth but as a cost center that weighs on margins.
I’ve included the first two charts below, because they’re important and, well, damning.
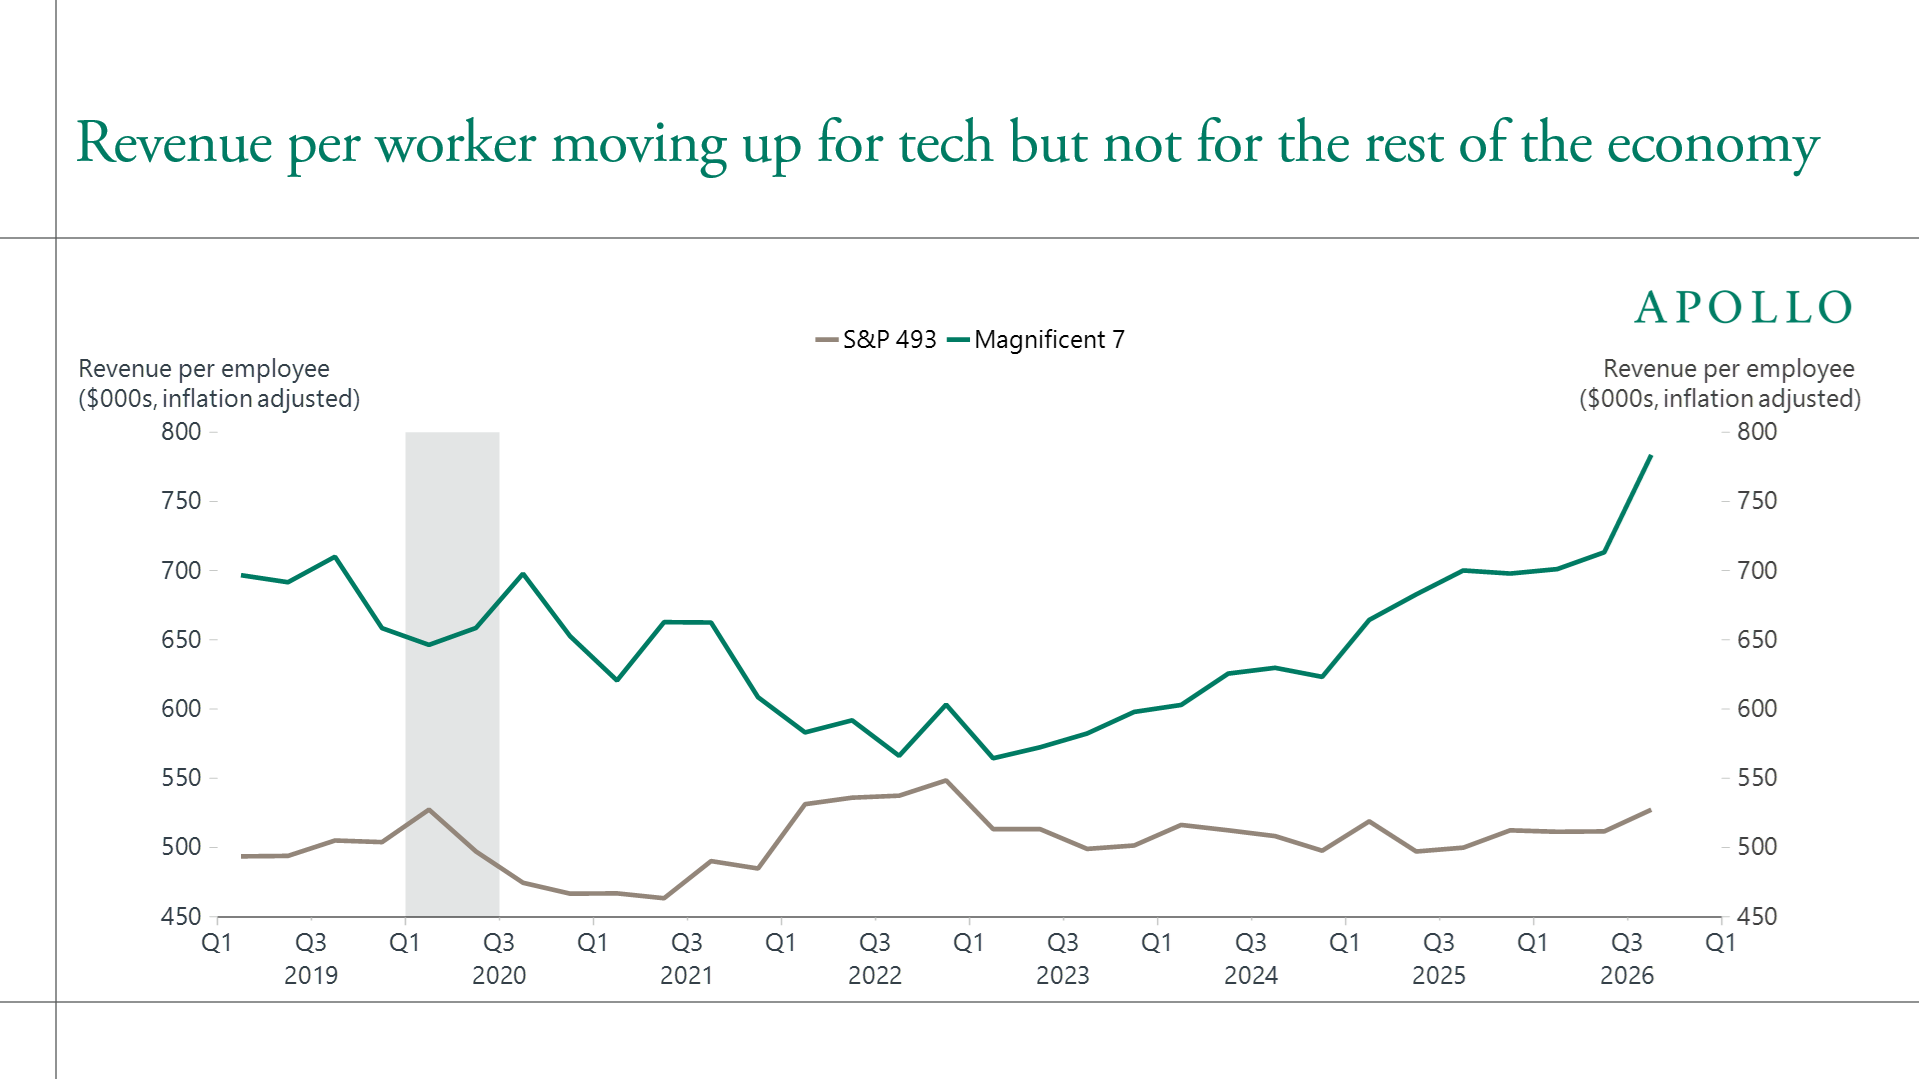
In the grand scheme of things, the whole sales pitch for AI is that it’s an enhancer or a job replacer, by which I mean it makes your current resources more efficient and/or productive or allows you to replace said resources, with “resources” meaning cash, people, software, or other things that you use to run your business.
The reason I’m speaking in such Fisher Price-esque terms is that the AI bubble has been inflated by intentionally escaping the terminology that you’d use to measure the health of a business. Four years into the bubble, AI should, at least in theory, be doing something to the world of business — something measurable, especially given that just about everybody is talking about installing it everywhere and using it all the time.
Yet profit margins appear to have gotten worse across the S&P 500 since the beginning of the AI bubble, with ChatGPT’s November 2022 launch appearing to do sweet fuck all for anybody not called Google, Amazon, Meta, Microsoft, or NVIDIA, with Tesla and Apple having very little to do with the AI bubble as we understand it.
AI boosters and malcontents have spent the best part of four years trying to get everybody to talk about any imaginable statistic other than the ones that matter, mostly because they universally look like this:
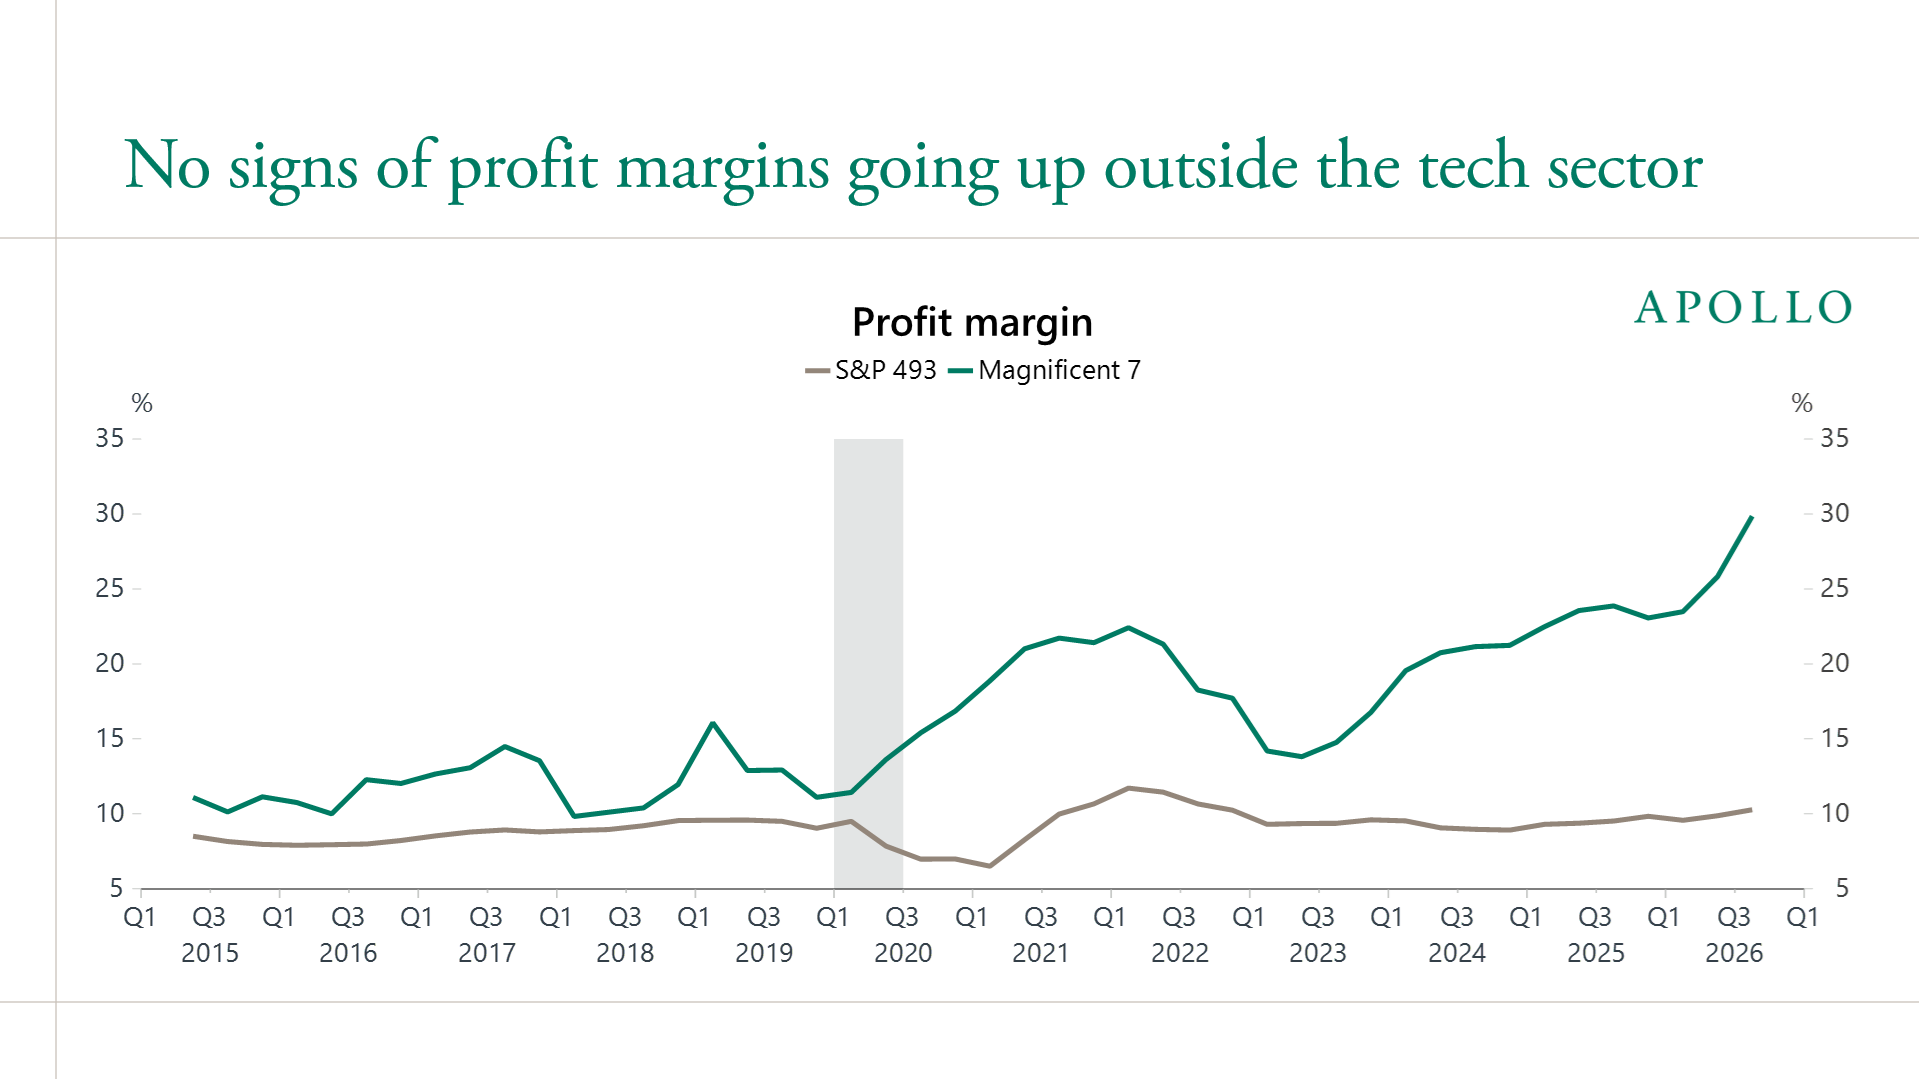
The counterpoint they’re going to give is that “organizations have yet to fully install AI in their workflows” or some such business, not so much moving the goalposts but constantly changing the rules of the game to the point that it’s unclear what it is we’re playing. It isn’t making companies more money, more profits, or improving them in a manner that can be measured by modern science.
And, per Slok last week, it isn’t even improving the ROIC (return on invested capital) for hyperscalers, and that was before Meta announced its plans to raise nearly $100 billion through ongoing equity sales:
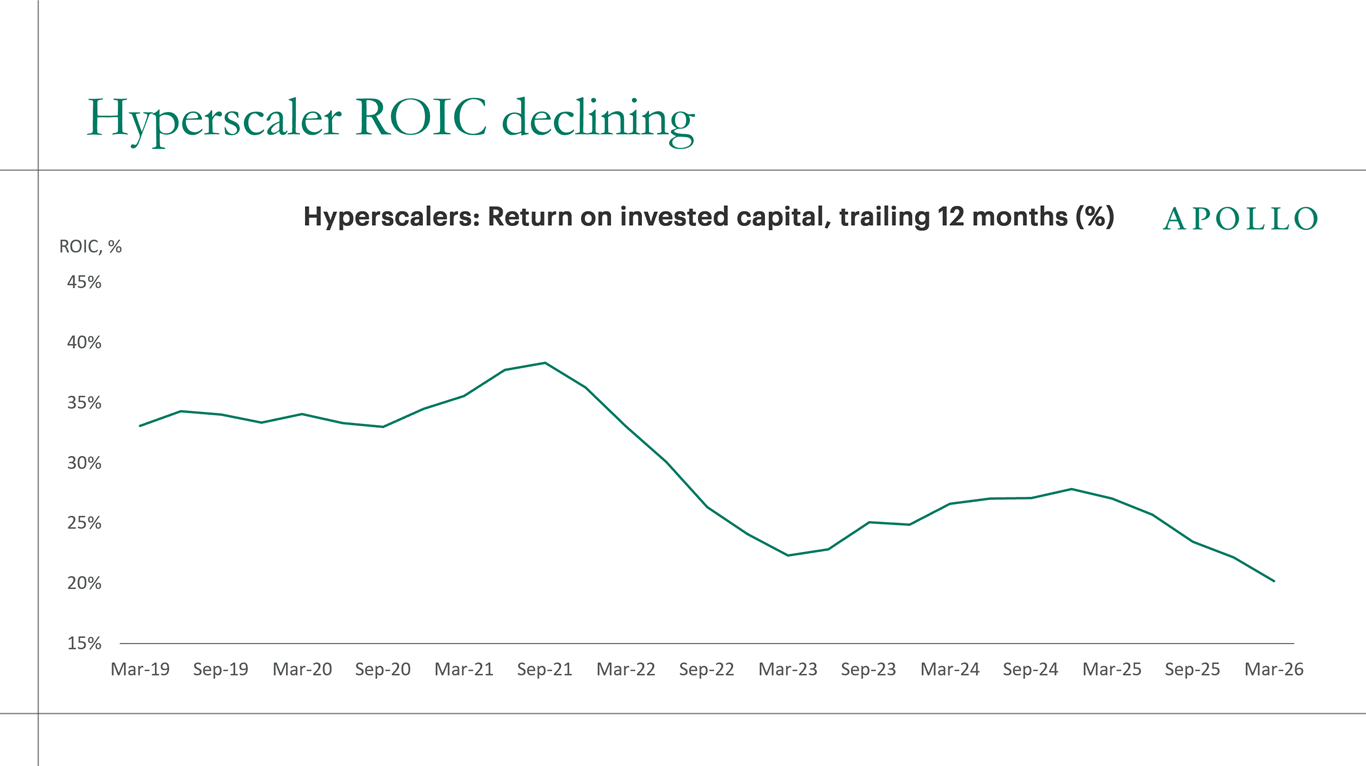
It appears that AI does not appear to be increasing revenue or margin growth across the S&P 500, other than in the magnificent seven, who in return for over a trillion dollars of capital expenditures have seen their return on invested capital drop on a quarterly basis.
Yet every single company building anything AI related will tell you that it’s changing everything and that you have to get on board today, even if the product doesn’t really work the way they say it does, even if there isn’t really tangible evidence that it’s a good investment, and even if it’s clear the companies running the services have deeply questionable economics.
And that’s because this entire industry is sold with a genuine contempt for the end customer or investor.
Including, I should add, the biggest IPO in Silicon Valley history.
To quote economist Paul Kedrosky on the Prof G Markets podcast, “...this [S-1] is as good as it looks from the standpoint of the business as currently structured. And now you go through this inflection that makes it much more capex intensive."
I’m going to be a little more brutal, as I believe that Anthropic is intentionally misleading investors at a scale unseen in the history of IPOs. Whatever excitement anyone might have about cashflows or the stretched definition of “profitability” is irrelevant, as Anthropic is, by its own admission and its unbelievable obligations, a completely different company to the one it was in the second quarter of this year.
So, as you’ve likely read, Anthropic finally dropped its S-1 earlier in the week, a 300+ page megalith of different risk factors and disclosures that also carefully avoided including things that might have been useful to fully analyze it, specifically leaving out anything to do with its third quarter numbers that were disclosed during its investor day.
Sidenote: It seems as though Anthropic’s aligning its financial year with the calendar year. In that case, its third quarter would have ended on September 30.
If we hold Anthropic to the same expectations as publicly-traded companies, there’s nothing inherently dodgy (bear with me) with it failing to disclose its latest figures. The SEC gives public companies 45 days to publish their results after the close of each fiscal quarter.
That said, if we hold Anthropic to the same expectations set by large publicly-traded companies (bear in mind it’s targeting a $1.5 trillion valuation, though investors have reportedly told investors that their target has shifted to potentially as low as $1.4 trillion), it’s a bit lousy. Companies of this size can (and do) publish their audited numbers within a few weeks of the close of their fiscal quarters. SpaceX, for example, published its Q3 results on October 20, with Meta following one day later.
Both of these companies are larger, more diversified, and therefore considerably more complex. And so, it’s hard to ignore or rationalize away this glaring omission.
And despite all the hubbub and booster-cope, the vast majority of the numbers were already known, and many of the new ones make things much, much harder to stomach.
This means that the latest quarter we have — Q2 2026 — is “profitable” (as I discussed back in May) due to the discounts given to it by SpaceX for two out of the three months of the quarter:
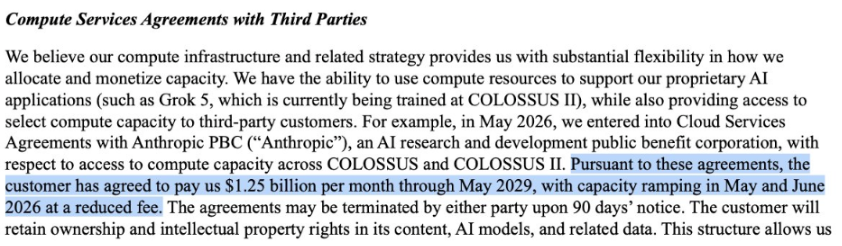
Hence Anthropic’s profitable quarter — a $974 million profit, to be specific — which was largely a result of events that will likely never be repeated.
Sidenote: I should also add that you can see this is an anomaly when you use Anthropic’s own “dollar of revenue per compute” number. For Q2 2026, it brought in $2 of revenue per $1 of compute spend, up from $1.39 in Q1 2026. This number dropped to $1.70 in Q3. I think it’s a stupid number as it doesn’t really say very much about the business, but even based on Amodeiconomics, this quarter feels like the exception rather than the rule.
In fact, the literal opposite is going to take place over the next few quarters, as Anthropic’s massive non-cancellable burdens start weighing on its balance sheet regardless of how well the company does.
You see, this was an opportunistically-timed S-1, as the vast majority of Anthropic’s big compute contracts only got started in or around Q2 2026, with $224.5 billion in non-cancellable agreements with Amazon and Google starting in April and May.
In SpaceX’s case, the compute bill is much, much larger than we thought, going from the $1.25 billion a month that had previously been reported to, as of December 2026, $3.1 billion a month, or around $37.2 billion a year.
In Microsoft’s case, Anthropic is due to start paying it as of November 2026.
That’s around $269.4 billion in non-cancellable compute commitments, the majority of which are yet to be realized on Anthropic’s actual books.
There’s also another curious note:
Who are those with? Who knows! No need to tell us what those are, when they might amortize, the terms of those contracts, or really anything at all. What’s $21 billion between friends?
Anyway, there’s also Broadcom, which builds Google’s TPU chips and has $161.2 billion in non-cancellable leases with Anthropic, with the only out being an outright default. While Anthropic notes that “a portion of” the chips “began to come online in 2026…additional capacity [is] expected to come online starting in 2027.”
Sidenote: You’ll notice I haven’t brought up Anthropic’s obligations with Nscale or Lambda, and that’s because neither of them feel very real to me despite being “worth tens of billions of dollars.” Anthropic signed those deals to help boost the neoclouds’ IPOs, the capacity doesn’t currently exist, and building it will require debt from a market that, if you believe Elon Musk, has stopped lending money.
In other words, Anthropic’s numbers tell the story of a completely different company to the one that will actually go public, and lean heavily on a quarter with discounted compute costs and yet-to-fully-commence agreements that will weigh on the company regardless of its revenue growth.
And because this is a draft and Anthropic knows it doesn’t really have to give this information, the breakdown of its contractual obligations is left…completely blank!
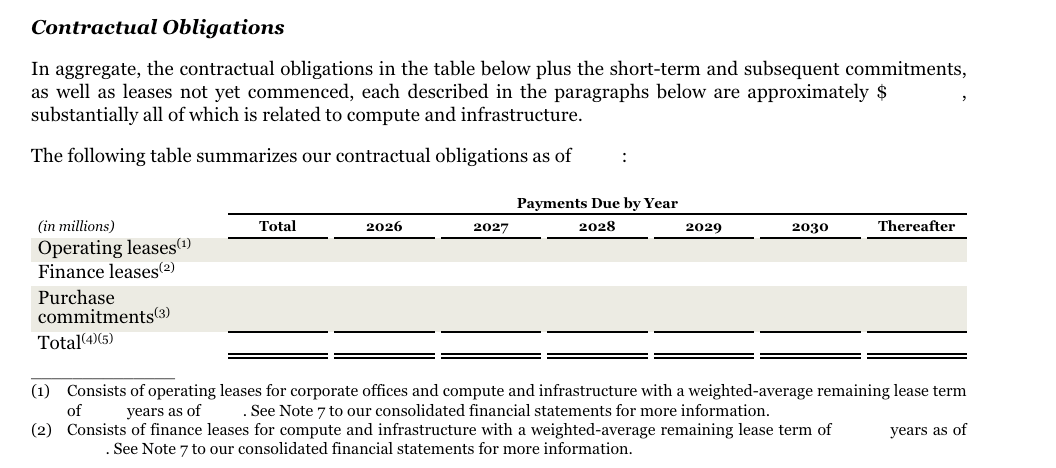
The gaps in this S-1 filing are seemingly custom-built to obfuscate any ability to try and work out anything about its future.
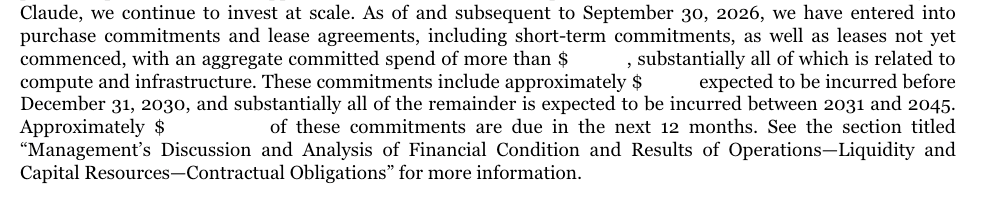
Despite filing more than three hundred pages of information, Anthropic chose to leave out:
I’ll give Anthropic some leniency — this is a draft filing, and thus it’s possible that it adds these numbers before the actual IPO, but nevertheless, this is extremely valuable information given that its revenue growth, per Reuters, slowed to (a still very high) 45% quarter-over-quarter in Q3, growing from $11.5 billion to $16.8 billion. Per TickerTrends, even the bastardized “run rate” metric shows that things have begun to slow down:
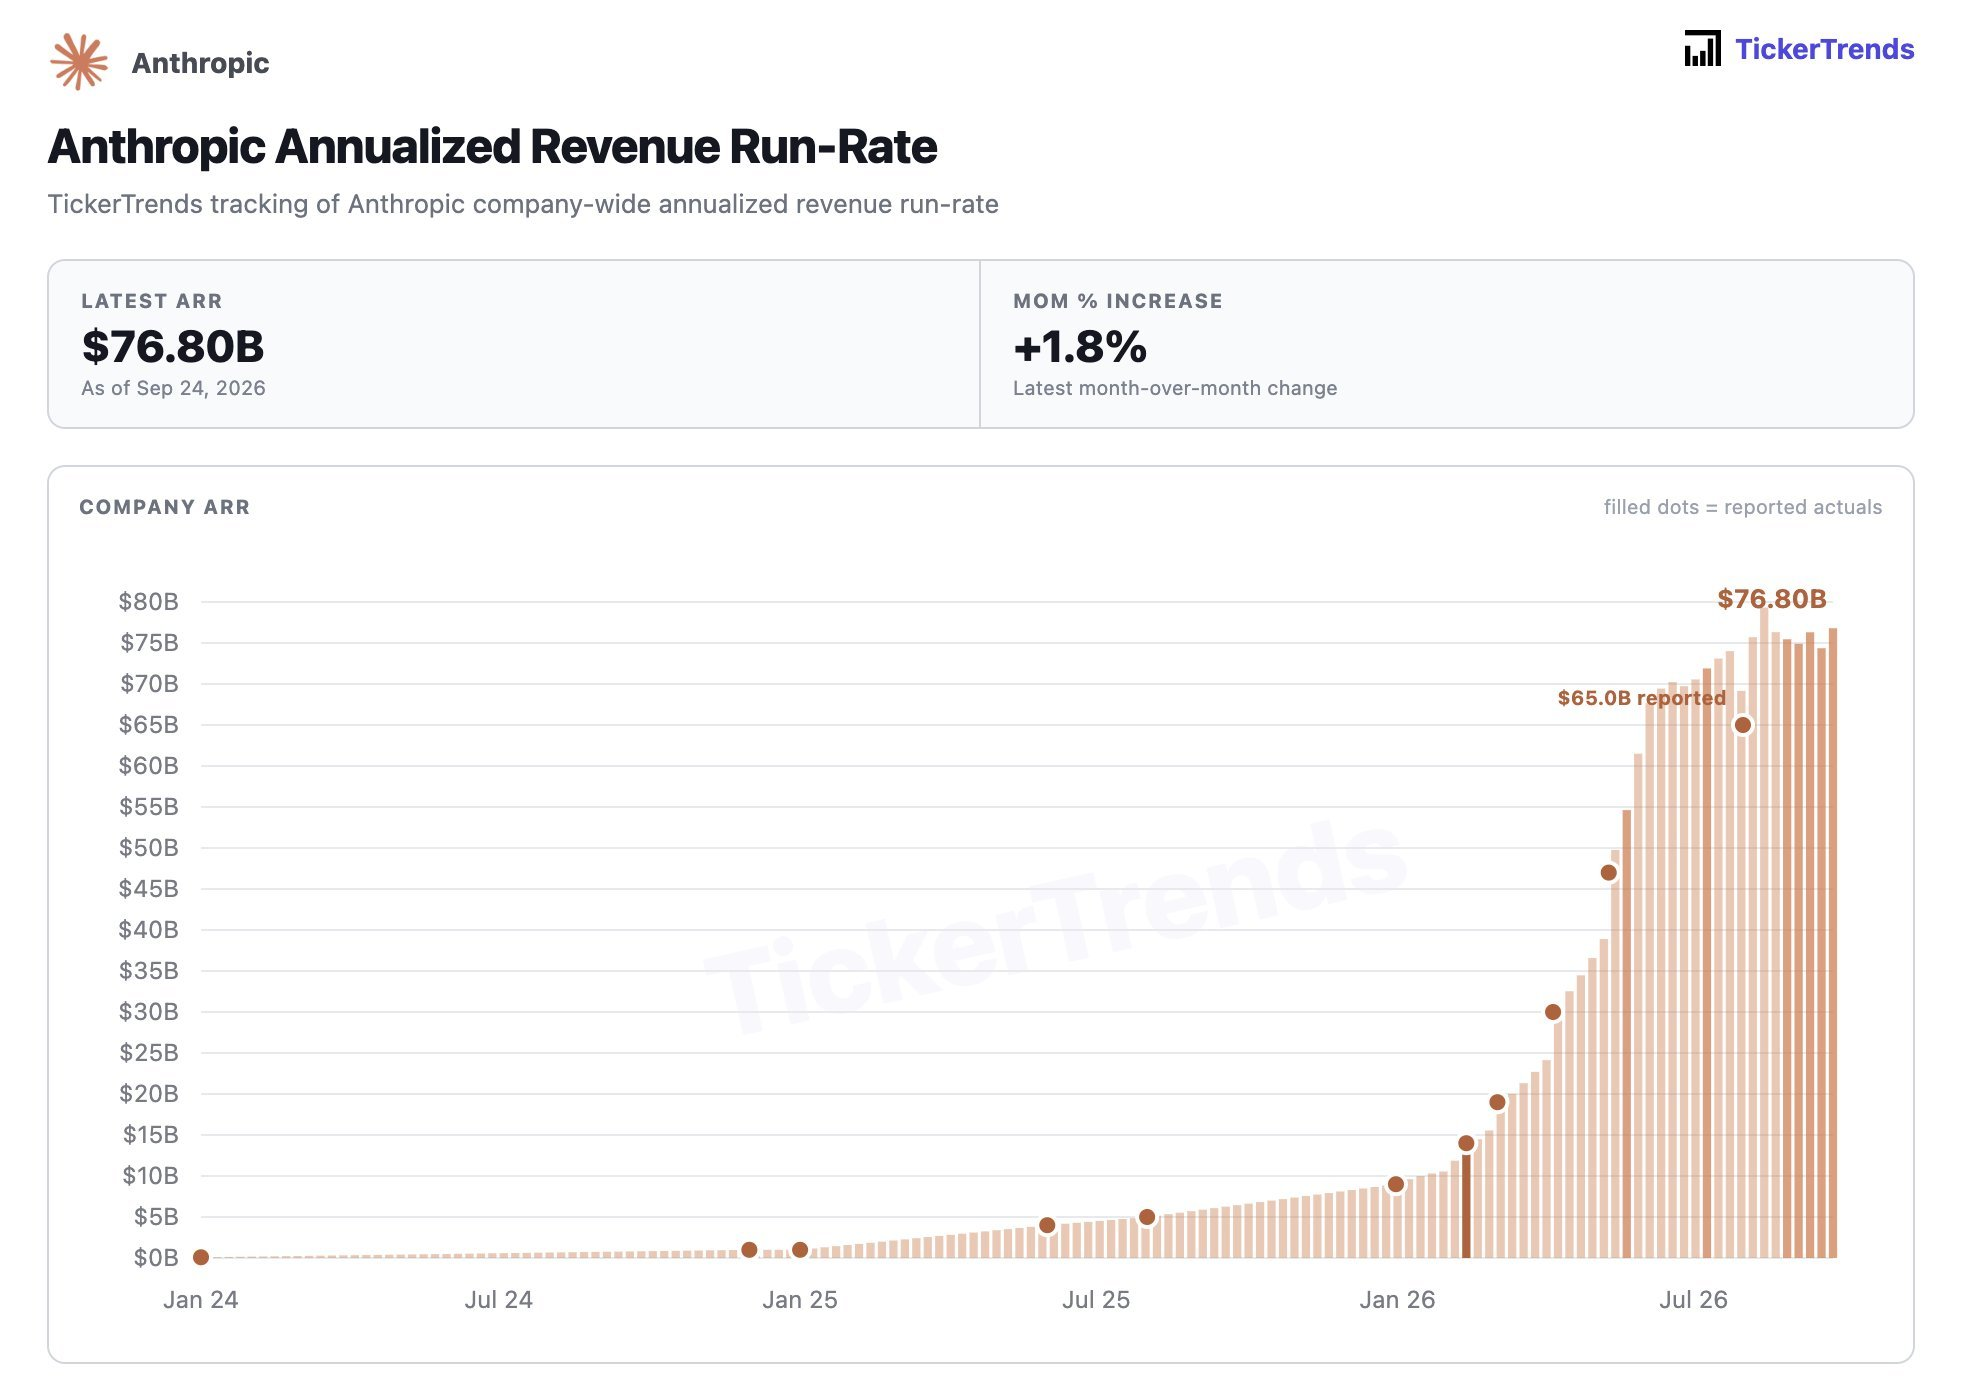
The era of token-maxxing — when companies like Meta incentivized their employees to burn as many tokens as possible, only to pull back after costs skyrocketed — ended somewhere in Q2 or Q3 2026, which is why Anthropic is so keen to push this company out the door, ideally before you learn too much about its latest quarter or how much its ongoing expenses might be.
Nevertheless, Anthropic had a profitable quarter, which proves that it has a more efficient business than OpenAI, even if said efficiency came from contractual shenanigans. The fact that it left out Q3 — a month we already know about — suggests that this is no longer the case, especially given that every article I read has it being profitable “on an adjusted basis,” which means removing stock based compensation (which was $1.261 billion in Q2 2026, and had grown by 36.5% quarter-over-quarter).
What’s also interesting — and frustrating! — is that, as of June 30 ,2026, Anthropic had around $112 billion in cash and cash equivalents, giving us little insight into its current financial position or whether any prepayments have had to go out the door. What’s wrong, Anthropic? Afraid you might tell us something about your liquidity?
Nevertheless, the majority of it — $110.4 billion — came from two funding rounds, one of which was larger than reported:
I’ll admit that Anthropic’s cash position surprised me, especially given what appears to be a drastically lower compute spend than I (and others) had expected…which makes the lack of any payment schedule all the more frustrating.
There’re two reasons I can imagine, and both can be true at once!
Either way, the Anthropic described in this S-1 isn’t really the one that’s hitting the market.
In fact, Anthropic warns investors of exactly that, and has an entire risk factor dedicated to it aptly titled (emphasis theirs) We are at an early stage of our revenue growth, we have experienced rapid growth in recent periods, and our historical growth rates are not indicative of future performance or our ability to sustain or forecast future revenue growth.
We do not expect our revenue will continue to grow at comparable rates, and we cannot assure you that it will continue to grow at all. Our recent growth may reflect early-stage adoption dynamics, the nascency of the AI market, and rapid initial customer expansion that may not be sustainable over time, and it may decline significantly and more rapidly than we anticipate, as our revenue base increases, as the market matures, and as a result of the other factors described below. We expect our revenue growth rate to decline over time. In addition, because the AI industry is very nascent, we have struggled to accurately forecast our revenue in the past and may struggle to do so in the future.
It also names a number of factors that could slow growth, including a slowing or shifting demand for models, an ability to secure sufficient compute or to direct it efficiently, failures or performance limitations on models (including unexpected behavior), increasing competition, safety risks, and my personal favourite…
insufficient growth in the number of users and paying customers of our models, platform, and applications or the failure to increase sales of our models, platform, and applications to existing customers
“Customers” could mean many things, given that 48% of Anthropic’s first half 2026 revenues came from selling its models through Amazon and Google.
There’s also this fascinating note included in discussion of run-rates:
Our recent Run-Rate Revenue growth has also been driven in part by rapid initial customer adoption and expansion often characteristic of an early-adoption period and the nascency of the AI market that may not be sustainable, and we expect our Run-Rate Revenue growth rate to decline over time, and it may decline significantly and more rapidly than we anticipate, as our revenue base increases, as the market matures, and as a result of other factors.
In addition, our Run-Rate Revenue has included, and we expect will continue to include, amounts from customers that we subsequently determine are using our models, platform, and applications in violation of our usage policy or commercial terms.
Which leads me to another problem…
On page 145, Anthropic reveals that 5% to 7% of its revenues came from what appear to be distillation attacks, meaning other model providers using its models or accounts to train theirs:
In addition, our revenue has included, and we expect will continue to include, amounts from customers that we subsequently determine are using our models, platform, and applications in violation of our usage policy or commercial terms. We believe this dynamic is common in our industry. Because detection, investigation, and enforcement take time, we recognize revenue from such customers when the related services are provided, before restricting or terminating their access. Based on our detection and review process, we estimate that revenue from such customers represented approximately 5% to 7% of our revenue for the nine months ended September 30, 2026.
When we factor in that Anthropic’s revenue to date — including the $16.8 billion reported for Q3 2026 — is around $33.08 billion, that means that as much as $2.31 billion of its revenues (7%) has come from other companies distilling its models. Anthropic expects the percentage of revenue from this part of its “business model” to decline, adding that it will have “an uncertain adverse effect on revenue and revenue growth.”
Its five largest customers also accounted for 25% of its revenues through the end of Q3 2026 — you know, the one it didn’t include! — with Anthropic adding that “many of its top customers are not subject to long-term contracts or have contracts with near-term expiration dates and are able to reduce or in some cases cease spending at any time for any reason.”
While it’s unclear who these large customers are, they undoubtedly include Meta and Microsoft, both of whom are reported to reduce their use of the platform, with Microsoft AI CEO Mustafa Suleyman saying back in June that he wanted to eliminate the spend entirely.
Then there’s the rest of them — and these three bullet points that I’ve seen multiple media outlets attempt to frame as a positive for the company.
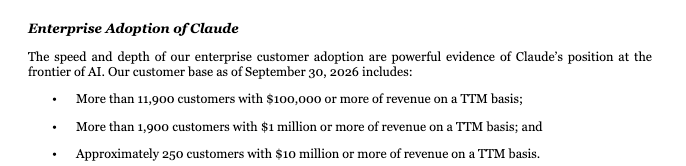
Let’s play around with this.
These figures are on a TTM (trailing twelve month) basis, meaning the previous twelve months before the end of the reporting period — namely, the end of June. If we do the math, Anthropic had revenues of $19.708bn over the period (with H2 2025 bringing in $3,422bn), meaning that, in our most generous (and therefore guaranteed to be wrong) nearly one-quarter of its revenue from that period came from a relatively small group of whales.
If we make those assumptions less generous, even marginally so, then the revenue concentration becomes a lot more bleak. If the lowest possible estimate is wrong by 50%, then nearly one-third of Anthropic’s revenue comes from that small group of whales. If the lowest-possible amount is half the real number, then, in turn, just under half of Anthropic’s revenues from that period came from the same small group.
Again, the most generous estimate is guaranteed to be a fraction of the real number, not least because two customers alone accounted for 23% of Anthropic’s accounts receivable in H1 2026. The above exercise assumed that each whale uniformly spent the least amount possible in their respective bracket — an unrealistic proposition, but one that illustrated a point.
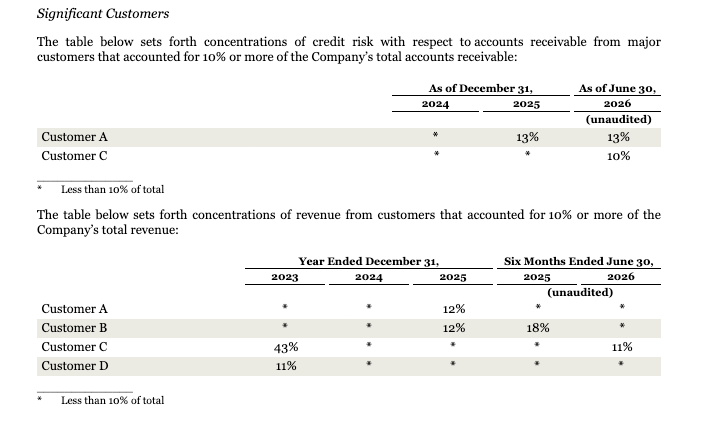
And then there’s the other problem: a large share of these supposed “diverse” customers are, in fact, unprofitable and unsustainable AI startups.
Anthropic also quietly mentions what I believe is its second-largest — behind its compute agreements — existential risk:
…our customers, particularly early-stage and high-growth companies, may depend on venture capital or other external financing to fund their operations, and may reduce or cease spending with us if such funding is delayed, reduced, or unavailable or if their access to capital becomes more costly.
As I’ve discussed previously, per Ramp, 80% of OpenAI and Anthropic’s enterprise revenues — the vast majority of what they make — come from 1% of their customers, with the vast majority of those being venture-backed startups that as I’ve also discussed allow their customers to burn anywhere from $3 to $10 for every dollar of subscription revenue.
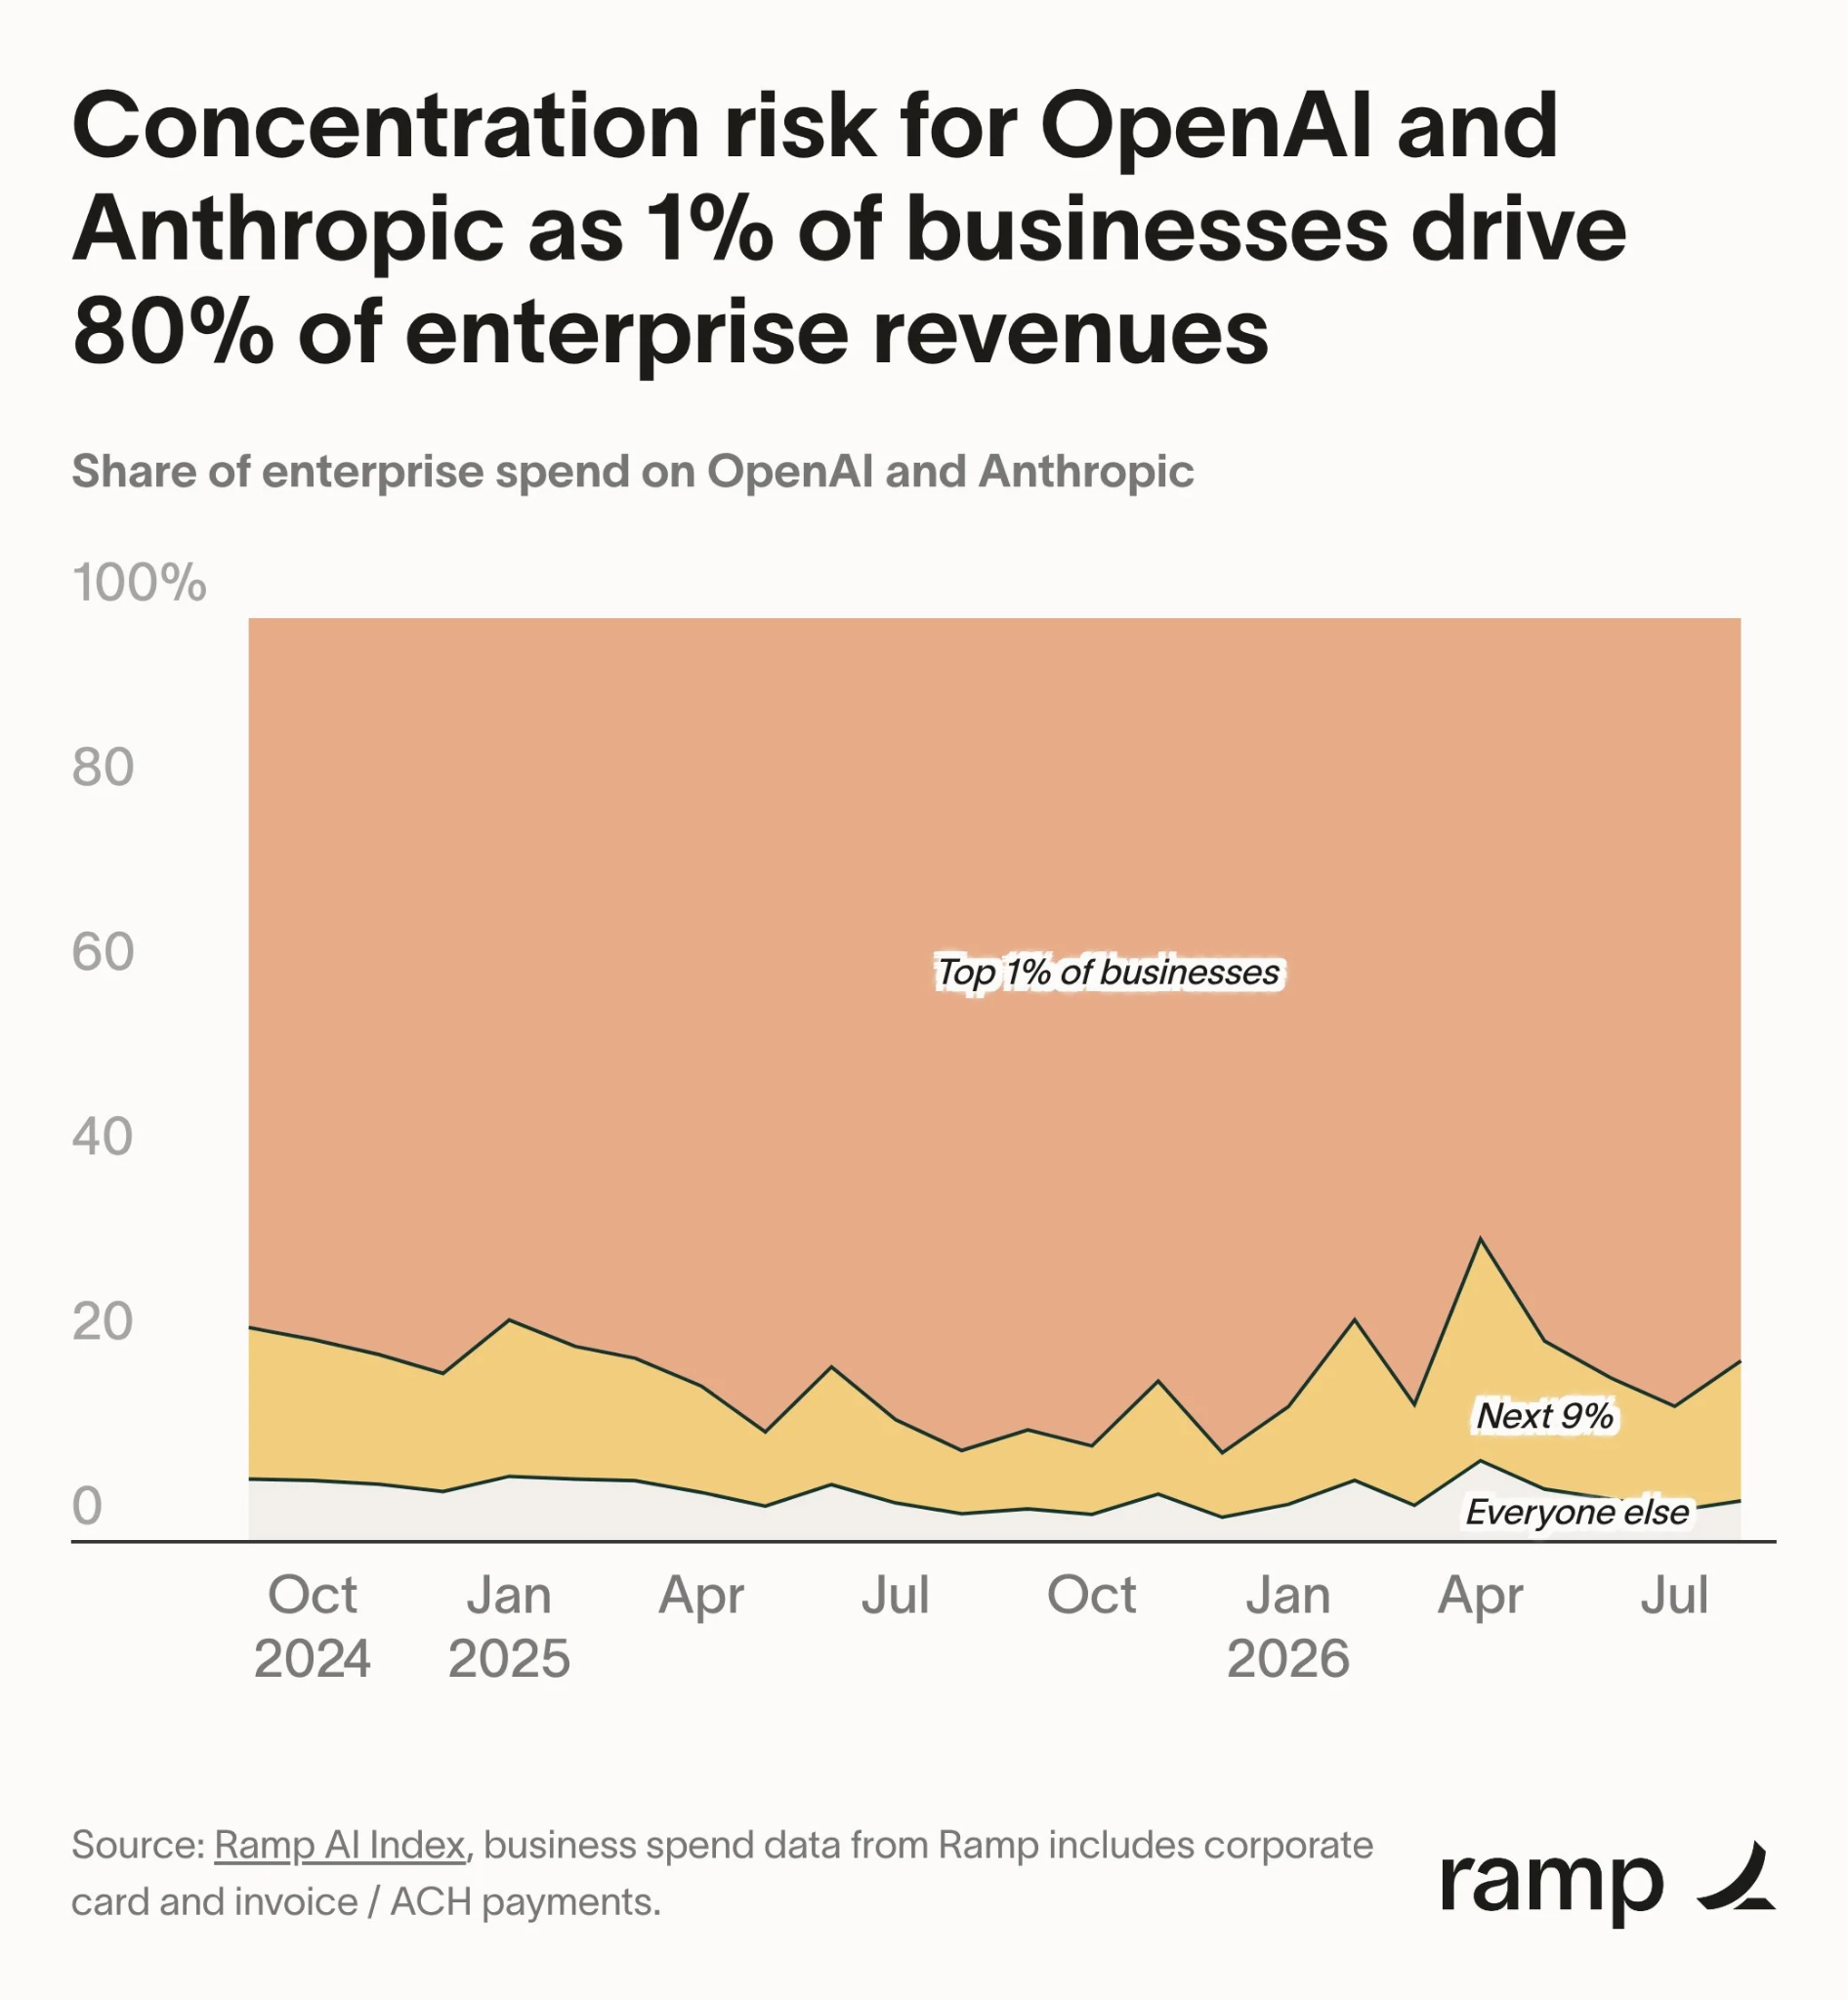
Per my last newsletter:
For example, SemiAnalysis did a deep study into the amount of tokens you could burn on the various different AI subscriptions out there, finding that you could burn anywhere from $83 to $118 a month for $20 and from $1,264 to $1,331 a month for $200 on Cognition, dropping to $46 on a $20-a-month plan and $507 for $200-a-month on Cursor when using Anthropic’s models.
This means that a large chunk of both companies’ revenues are dependent on their customers being able to continually raise capital, which is why companies like Harvey have to raise hundreds of millions of dollars every few months to keep up with their costs.
And it’s clear that Anthropic offered temporary discounts to pump its revenues through IPO, only to discontinue them unless the startup committed to spending more on the platform through tactics I’d describe as a little brutal:
Per The Information, on September 2026:
While both Anthropic and archrival OpenAI provide discounts to customers that commit to spending millions of dollars a year on their products, Anthropic has taken the unusual step of ending customers’ discounts once they hit the usage limits in their contracts, according to managers from three software firms that buy AI from both companies. Customers that reach the cap must negotiate a new agreement or face higher prices, these people said.
“The second you hit the cap, you get phone calls and emails from Anthropic sales teams, saying ‘Hey, we noticed you hit your cap—if we address this today with a new agreement, you can avoid overages,’” one of these people said. “Otherwise you’re on your own.”
Somewhere between a mobster and a drug-pusher, Anthropic assumed its customers would simply capitulate, assuming (incorrectly) that OpenAI wouldn’t compete on cost:
Per The Information last week:
Replit, a coding app, in recent months switched the majority of its AI spending to OpenAI from Anthropic after OpenAI offered a discount of more than 30% on its model prices as part of a contract worth more than $100 million annually, according to a person familiar with the situation. The startup had planned to stick with Anthropic, but Anthropic wouldn’t extend a discount it had previously provided to Replit unless the startup committed to a higher spending level, this person said. (Replit has publicly discussed shifting toward OpenAI but hasn’t disclosed the discount it is receiving nor the size of the contract.)
“In recent months,” eh? Replit had mentioned a few weeks ago that it was no longer working with Anthropic, which makes me wonder if the effect of the dropoff will be realized in, say, Q4 2026, you know, the quarter after it goes public.
Anthropic is playing a dangerous game where it either chooses to alienate some of its largest customers or drain them of what remains of their venture capital by demanding they guarantee a minimum spend on tokens.
And I imagine the reason Anthropic is doing so is that it realizes it’s bitten off more than it can chew with its compute commitments.
Eager beavers reading stories about Anthropic’s Q3 2026 numbers will note that it boasts about generating “$1.70 in revenue for every dollar spent on computing power,” which works out to approximately $9.88 billion in compute spend for $16.8 billion in revenue.
This is likely one of the main reasons that Anthropic didn’t include its Q3 numbers — because Q3 2026 is when its compute spend grew faster than its revenues on a quarter-over-quarter basis, where revenues grew a (still impressive) 45% (from $11.5bn to $16.8bn), but compute costs grew 76.3% (from $5.5bn to $9.88bn).
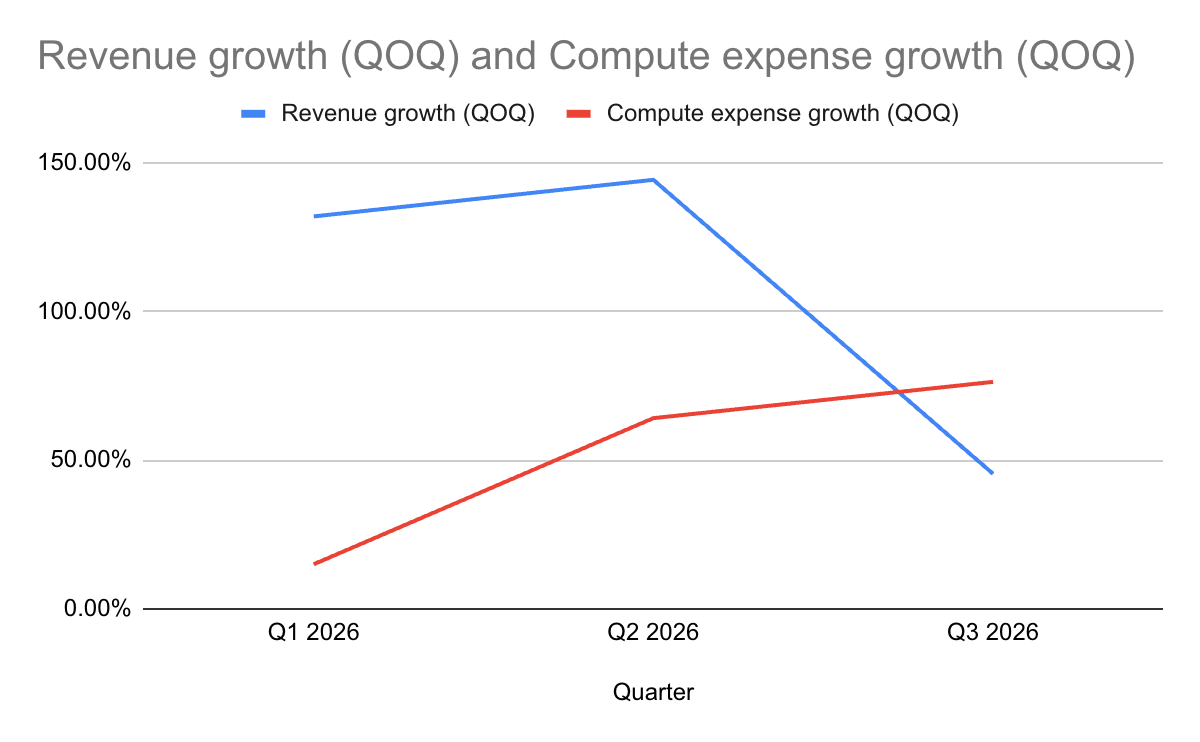
It’s also interesting that Anthropic fell back on that “dollar of revenue per compute” figure, especially considering that said number declined from $2 (Q2 2026) to $1.70 quarter-over-quarter. I imagine it assumed nobody would bother to think about it for two minutes.
In any case, while we don’t know much about Anthropic past Q3 2026, we do know that it has hundreds of billions of compute costs due in the next few years, and that they’re going to increase dramatically:
Then there’s this curious note at the bottom of page 170 following its disclosure of its deal with Google to rent TPUs:
In addition, we also committed to procure additional TPU compute from TPU providers, including Google, to be delivered between 2028 and 2031. The payment obligations for such additional compute are determined by the capacity made available, the manner in which it is deployed, the pricing mechanics, and the satisfaction of certain deployment conditions. We estimate the aggregate future payments for such additional compute to be approximately $125.0 billion to $150.0 billion, which are not included in the contractual commitments table above.
So yeah, just another $125 billion or $150 billion in commitments. No big deal! Don’t worry about it.
As far as its non-cancellable commitments go, this all works out to around $75.6 billion in annual compute commitments, with each deal having the crucial phrase “at least.” The fact that Anthropic doesn’t include the exact breakdowns is an insult to basically every investor putting money in this IPO.
Yet if we (sigh) annualize Anthropic’s Q3 2026 compute spend, this means that Anthropic is likely on the hook to nearly double how much it’s spending on chip rentals at precisely the moment it’s slowing down.
Anthropic is telling us in no uncertain terms that the company you see before you is not the one that will actually go public. This is not my personal opinion, but an objective explanation of the S-1.
In its S-1, Anthropic is telling you that “...historical growth rates are not indicative of future performance or our ability to sustain or forecast future revenue growth” (page 16), and specifically that “...results for the six months ended June 30, 2026 are not necessarily indicative of the results that may be expected for the full year ending December 31, 2026 or any other period” (page 22). It reminds us again on page 62 that it does “...not expect [its] revenue will continue to grow at comparable rates,” that it can “not assure you that it will continue to grow at all,” and that "recent growth may reflect early-stage adoption dynamics, the nascency of the AI market, and rapid initial customer expansion that may not be sustainable over time, and may decline significantly.”
On page 64, it tells you that Anthropic “...expects [its] costs will increase over time and [its] losses will continue as we expect to invest significant resources towards growing our business and operating as a public company.”
On page 67, Anthropic explicitly states that its run-rate revenue growth was driven by “expansion often characteristic of early adoption periods” and “may decline more rapidly than it anticipates”:
On page 133, Anthropic says that its margins will get worse as compute comes online:
As significant incremental compute is brought online in future periods, the associated expense will be recognized in advance of the full revenue that the compute will ultimately support, and we expect operating margin and Adjusted Operating Margin may compress in those periods.
…and that’s before factoring in short term compute costs (page 134).
In addition, the majority of our compute is contracted under multi-year commitments that we typically procure 12 to 18 months in advance of availability. When customer demand or research needs exceed this long-term capacity, we procure short-term compute, which typically carries a higher cost per unit of compute. We expect our use of short-term compute to increase in the near term and to in turn compress our operating margin and Adjusted Operating Margin as a result.
On page 161, Anthropic explicitly states that its “increasing efforts to build out our compute and infrastructure require substantial capital expenditures and are changing the cash flow profile of [its] business, and that the underlying economics of its compute payments are set to change, including larger prepayments and “substantial” capex:
Our increasing efforts to build out our compute and infrastructure require substantial capital expenditures and are changing the cash flow profile of our business. Whereas the compute purchased through our CSP arrangements is generally paid as the compute becomes available to us, we expect an increasing portion of our compute and infrastructure investment to take the form of capital expenditures and other commitments, including lease obligations, that require significant upfront payments well in advance of the related compute becoming operational. We expect our capital expenditures to increase significantly as we expand our build-out, and we expect these investments to result in significant net cash used in operating and investing activities for the foreseeable future. Our net cash used in these activities may increase regardless of whether our financial performance improves.
In other words, the Anthropic of Q2 2026 — the so-called “profitable,” compute-light firm that’s got boosters hot under the collar — is a moment in time specifically chosen so that people come away with a vision of a very, very different company to the one they’d be investing in.
Anthropic is guaranteed — in its own words! — to have slower growth, worse margins and higher costs going forward, and by putting out just the Q2 numbers, it’s engaged in a truly offensive bait-and-switch with an investor class buoyed by a media ecosystem incapable of seeing when it’s being duped.
What makes this all the more offensive is that Anthropic shared some of its Q3 numbers with investors only a couple of weeks ago! It clearly has them, and considering its other 2026 numbers are unaudited, I see no excuse to not include at least its cash position and operating expenses outside of “we don’t want investors to compare them to Q2.”
Is there a version of Anthropic that could be truly economically viable? It’s unlikely given that so much of its revenue is dependent on venture capital. With the vast majority of its revenue coming from venture backed startups, it’s reasonable to question whether there’s fundamental demand for AI writ large — and while boosters may respond that “it’s just the early days,” I think that’s fucking laughable when you’ve made nearly half a trillion in commitments and are claiming a total addressable market of $30 trillion.
You can do whatever mental gymnastics you want — “oh, it could just stop training and be profitable” — but all that matters is what Anthropic is actually doing, which is making $430 billion in non-cancellable commitments and explicitly stating that its economics will get worse.
Anthropic’s largest customers are also explicitly building competitors and/or actively discussing dropping their services. SpaceX (which owns Cursor) has Grok and just took on $40 billion in debt to buy more GPUs to train it (and will potentially kick Anthropic off of its infrastructure to do so), Meta has Muse, and both Meta and Microsoft have explicitly discussed dropping their Anthropic use.
Then there’s the threat from open source LLMs, which appeal naturally to Anthropic’s largest customers. While it might be impractical for an AI startup to spend tens or hundreds of millions training its own models when its users demand access to the latest from Anthropic and OpenAI, a large, established business with any real interest in AI would see far more value in — and have the resources to execute on — training their own off of one of the many open source options, like Meta’s open weight Muse model.
I should also be clear, as I discussed two weeks ago in my premium newsletter, that the only objective of this IPO is to dump Anthropic onto the public markets.
At a $1.4 trillion to $1.75 trillion valuation, Anthropic is long past the point at which there’s really any room for this to grow like, say, investing in Amazon (which went public at $438 million), Microsoft ($777 million or so), Google ($23 billion), or Meta ($104 billion).
Sidenote: Should Anthropic debut at $1.4 trillion, it would no doubt be a massive disappointment for those that invested when the company was targeting a paper valuation of $960 billion.
For some context, Meta’s current market capitalization as of writing this sentence is about $1.6 trillion, and that’s for a company with an effective monopoly on social media. How, exactly, does Anthropic warrant such a high valuation? And if it actually lists — which it sadly might, given how brainless everybody is — how does it retain that valuation?
In any case, all the proof you need that this is about dumping shares comes from Anthropic’s lock-up schedule, which allows non-founder insiders to dump 10% of their shares on the first day of trading, and a total of 45% of their shares the second trading day after Anthropic’s Fiscal Year 2026 earnings results.
Approximately 180 days — or earlier, if it reports its Q1 2027 earnings before then — after it goes public, Anthropic’s non-founder insiders can sell all of their shares, and founders can sell 29% of their shares. On the second trading day after its Q3 2027 earnings (or 365 days after its final IPO prospectus date, whichever happens first), everyone can sell everything, assuming their agreements don’t preclude them from doing so.
Those holders subject to a 180 day lockup period (which does not actually mean they have to wait 180 days) are allowed to sell 6% of their shares 27 days after the prospectus is filed, 6% more after 48 days, and by the second full trading day after its Fiscal Year 2026 earnings, can sell up to 38.5% of them. 69 days after those earnings, that jumps to 86%.
While some of this is fairly standard, the sheer speed at which insiders and shareholders can exit this company is remarkable, purpose-built to allow insiders to use retail investors to financialize their early bets in a company that’s been drained of any opportunity or value.
To quote Peter B. Parker in Spiderman: Into The Spiderverse, don’t watch the mouth, watch the hands.
If CoreWeave believed it would actually grow to meet its $100 billion in revenue backlogs — something that would undoubtedly send its share price to the moon — its three co-founders wouldn’t have sold $3.3 billion in shares since it went public in March 2025. If former Oracle CEO Safra Catz believed that Oracle would actually make anything out of its $300 billion, five-year-long deal with OpenAI, she wouldn’t have sold $1.8 billion in shares in the second quarter of 2025, let alone step down as CEO two weeks after the deal was announced. The same goes for NVIDIA CEO Jensen Huang, who sold $1 billion of his shares by October 2025 in a plan put in action in March 2025 — the month that DeepSeek panicked the markets about the threat of open source — and board member Mark Stevens, who sold $946 million in share sales in Q2 2026.
To quote Bloomberg in July 2026, US executives are selling shares at the second-fastest pace in more than 20 years, beaten only by the opulence of 2021. Meanwhile, corporate buying sat at $6.9 billion, a little above the seven-year-low of $6.7 billion, per Bloomberg.
In other words, while everybody in tech and AI is telling you to buy now and get in on the ground floor, their actual actions suggest an unwillingness to stick around and find out what might happen next.
The same goes for the massive, rushed AI debt deals you’re starting to see happen. Broadcom’s Hock Tan reportedly held (per the WSJ) “11th-hour talks with bank executives over the weekend” to finalize their $40 billion contribution to a $63 billion chip deal for Anthropic to lease back TPUs from the company, or put another way, for bankers to buy $63 billion in TPUs from Broadcom.
While Tan had to pay an indeterminately-higher interest rate on the deal, his urgency tells me that he’s well aware that the party is winding down and he needs to get as much money out of the system as possible. The same goes for Musk and his $40 billion chips deal (which is expected to close by year-end, per Bloomberg), with Semafor reporting that some parts of the debt could have as much as an 8.75% interest rate.
That’s an abominable interest rate you take only when you’re convinced that the money is running out.
Per the Washington Post, the AI industry is already admitting it behind closed doors:
How to summarize the sentiment among AI firms right now? “Take it when you can,” Matt Orton, chief market strategist of investment firm Raymond James Investment Management, said about the AI companies’ cash grabs. “Everyone is going to need more.”
Per MarketWatch, RBC’s Head of Fixed Income Andrzej Skiba thinks that “the funding market is about - or close to - shutting [the door on AI investments].”
Yet the worst of all of these strange attempts to absorb the world’s liquidity — other than Anthropic’s IPO, which I believe is an egregious swindle of retail investors — is Meta’s $97.5 billion at-the-market stock dump, where a company with little or no AI strategy dilutes its shareholders and cons retail by claiming it’s funding “futuristic AI” based on the brief yet collapsing growth of its Muse assistant.
That $97.5 billion number rivals the $50 billion to $100 billion Anthropic wants to raise in its IPO, and in both cases investors will be left holding the bag for two companies with little tangible proof that they can live up to their egregious promises.
And in the end, everybody else suffers.
Organizations are questioning the ROI. Apollo’s Chief Economist says there’s no payoff. Data centers are not getting built, and are requiring endless high-interest debt to fund them.
The two biggest companies — OpenAI and Anthropic — have over $1.3 trillion in obligations, many of them non-cancellable, and are looking to take their companies public before most of them kick in, tricking retail investors into believing they’re in a much better place just before the anvil drops on their head.
Anthropic is so confident in its growth trajectory that it left out the majority of its third quarter 2026 numbers from its S-1, reporting a second quarter before over $430 billion in non-cancellable compute commitments begin to kick in and its growth begins to slow.
46.5% of the NASDAQ 100 is wrapped in AI chipmakers like NVIDIA, AMD and Broadcom, hyperscalers Google, Amazon, Meta, and Microsoft, the memory company Micron, and the debt-ridden “neocloud” CoreWeave. The value of these stocks is tied to a very simple idea — that AI will grow in perpetuity, creating trillions of dollars a year in new revenues for both hardware and software companies alike. Per Gartner, data center owners will need to generate $8.5 trillion dollars in new AI revenues by 2030 to justify their planned expenditures, and they’re at least five trillion dollars short.
More than 37% of all US household wealth is tied up in a US stock market pumped full of hot air, and if you try and point this out, you’re often framed as a skeptic, a cynic or somehow ignorant of the bigger picture.
And to make matters worse, pension and insurance funds are increasingly being used to fund the buildout, per Jen Harris writing in the New York Times:
Take annuities, which are often relied on by retirees. Because many Americans rely on such insurance products, their policies are usually guaranteed by the state should an insurer go bankrupt. Right now, private creditors like Apollo are funding the debt boom in part by tapping the money sitting in companies like Athene, the $470 billion insurer Apollo controls. Should the A.I. boom go bad and Athene go under, Apollo knows the state (i.e. taxpayers) will be on the hook for much of what it owes policyholders. (Athene’s opaque disclosures make it hard to know how much of its assets are in data centers.)
Private-capital-backed firms now own nearly 20 percent of the entire U.S. life insurance industry, with assets of nearly $1.5 trillion.
There is something very, very wrong here, both in the events taking place and the coordinated efforts to attack anyone who would suggest otherwise.
At some point the money runs out — the funds behind the venture-backed customers of OpenAI and Anthropic, the debt underlying AI data centers, and the willingness of investors to tolerate endless quarters of eleven-digit capital expenditures — and once it does, everything I’ve been saying will become consensus.
And if we’re all being honest, it kind of already has — just not to the scale that can stop Anthropic using retail investors as exit liquidity.
If you liked this piece, you should subscribe to my premium newsletter. Right now I’m running a week-long sale — 10% off of the $70-a-year subscription for life (click here!) — for new subscribers. It’s a great way to support my work, and you get an absolute ton of value at a lower price than basically every competing newsletter.
If you want to get in touch — and especially if you have any juicy information about Anthropic, OpenAI, or any other companies in the AI bubble — hit me up on Signal at ezitron.76. I’m also on IB on The Terminal.
2026-10-24 00:28:34
For whatever reason, Blackstone founder and CEO Stephen A. Schwarzman has a thirty-chapter-long series called “My Personal History” that is, well, exactly what it sounds like — a financial hagiography that frames him as a noble, sensible man with strong values, like when he sent a letter to “distinguished skull and bones alumni” Averell Harriman, whose father Edward Harriman had crashed the stock market in 1901 in his dogged attempt to monopolize the post-bubble railroad industry. Averell himself had co-founded a bank with Fritz Thyssen, who banked the nazis.
Anyway, seven chapters in, Schwarzman makes a bold claim while telling the story of his first job on Wall Street in 1969, where he saw the oncoming collapse of a nearby student fridge rental and life insurance business (no, really):
I knew at once that the business could not last. Students kick refrigerators, throw them around and break them in no time. And a 20-year-old believes he will live forever; he has no interest in life insurance.
A visit to the company confirmed my suspicions. No one there seemed to know who was sitting in the next room. It looked like a growth company only because the number of students kept rising. Internally, it was out of control. I went back to the office and wrote a report concluding that the company would, in time, go bankrupt. Soon after, it did.
You may not be able to read a financial statement, but you can still recognize madness and folly. When weighing an investment, there are questions one must ask. Does the company have a real reason for being? Are people going to get excited about its products? Are the people running it authentic and focused, or are they merely salespeople trying to persuade you of something that is not real?
Good question, Steve!
While we’re on the subject, why is it that you invested $275 billion of Blackstone’s roughly $1.4 trillion in assets under management into data center and digital infrastructure investments? While people might get excited about their products, I have it on good authority that the $2.3 billion debt financing deal you did for CoreWeave (back when, per The Information, it only had $16 million in revenue) closed despite everybody having serious misgivings about the financial health, ongoing returns and actual viability of the business.
Based on everything I’ve learned about Blackstone, it appears that the only people you do business with are “salespeople trying to persuade you of something that is not real”!
Let’s go down the list:
Blackstone is the world’s largest commercial landlord, the world’s largest private equity firm, and the largest investor in data center infrastructure. It has invested in and/or loaned money at least once to OpenAI, Anthropic, CoreWeave, Google TPUs, Firmus, a private equity vehicle to sell Anthropic’s software, Lambda, and innumerable amounts of random AI startups and AI infrastructure companies at a scale that is hard to quantify for reasons I covered in both the Hater’s Guides to Private Equity and Private Credit, which mostly stem from the word “private.”
Nevertheless, even from the outside, Blackstone’s exposure to AI — and the greater software industry — is distressingly large, and thanks to that privacy, it’s very, very hard to tell where the money is coming from, both in the case of where Blackstone gets its funds and what specific vehicle it’s deploying them from.
Put another way, you can find Blackstone’s fingerprints on almost every big AI deal, yet more often than not have no way of saying what specific fund sunk in the cash.
Blackstone, as the Ur-Private Equitor, is not one company but a labyrinth of different investment funds, each funded by a combination of corporate pension funds, sovereign wealth funds, horrifyingly, public pension funds, which Bloomberg Intelligence estimates accounts for 32% or so of Blackstone’s overall funding.
Today, I’m going to dig into how credit, insurance and big bets on AI have changed one of the most evil companies in the world.
2026-10-21 00:12:06
If you liked this piece, you should subscribe to my premium newsletter, and you can subscribe on the following links: $70 a year, $18 a quarter, or $7 a month.
In return, you get a weekly premium newsletter that dives deep into the finances of the AI bubble. Over the past few months, I’ve published a two part guide to the world of AI debt, an analysis of the (dubious) impact of generative AI on the global economy, deep analyses of the biggest players in the AI infrastructure space like NVIDIA (part one and two) and Oracle (part one and two), how OpenAI will eventually kill Oracle, and how venture capital is killing itself.
Friday’s piece will be the Hater's Guide to Blackstone — one of the most loathsome companies in existence, and one that’s staked its entire existence on the AI bubble.
If you want to get in touch — and especially if you have any juicy information about Anthropic, OpenAI, Blackstone or any other companies in the AI bubble — hit me up on Signal at ezitron.76. I’m also on IB on your Bloomberg Terminal.
Soundtrack: Royal Blood — Pull Me Through
At the end of July, Apollo Chief Economist Torsten Slok gave a blunt warning to the Washington Post:
“This AI thing better work out because if it doesn’t ... we’re going to have a problem,” said Torsten Slok, chief economist at investment firm Apollo Global Management.
Today, I’m going to quantify exactly how difficult it will be for the “AI thing” to “work out.”
…everybody wants to make the AI bubble really complex, it’s actually super simple: hundreds of billions of dollars are being invested to make single-digit billions of dollars maybe, some day, if AI data centers actually get built at scale and OpenAI and Anthropic can afford to pay for their compute.
The theoreticals and hypotheticals of this industry are so powerful that they’ve created one of the (if not the) largest equities bubbles in modern history, all heavily-centralized around the valuations of a handful of names related to the so-called AI trade, which translates to “buying or selling stuff to do with AI GPUs.”
This has led to the single-highest inflow of foreign investments into US equities in history — larger than the Dot-Com Bubble, the leadup to the Great Financial Crisis, and even the dying gasps of the Zero Interest Free Era in 2021, per Apollo:
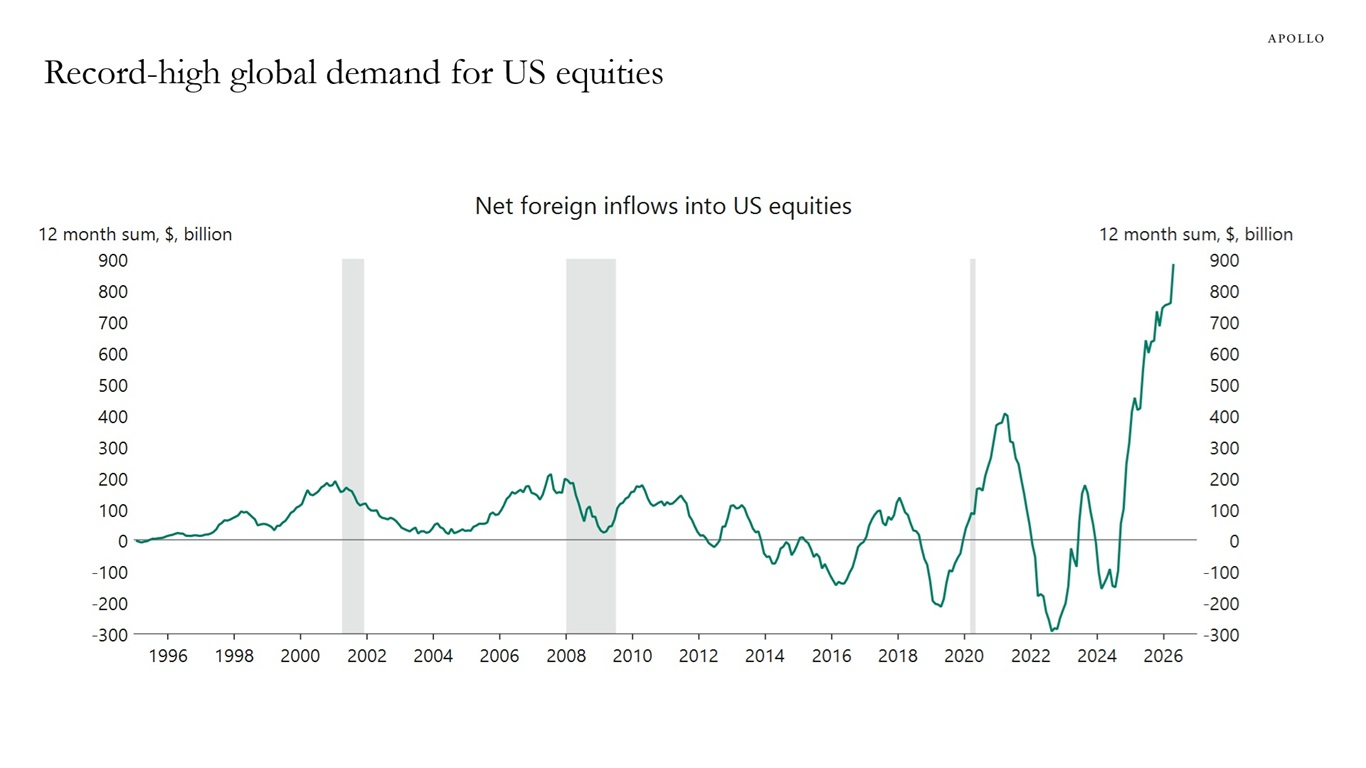
However you might hand-wave away the AI bubble’s economic issues by saying it’s “just like the Dot-Com Bubble” — when the NASDAQ 100 fell 77% from its peak — the consequences are now global, at a scale unseen in history, flowing into both direct stocks and indices.
As of typing this sentence, NVIDIA alone makes up 11.31% of the NASDAQ 100, with the combined weight of NVIDIA, Google, Amazon, Meta, Microsoft, Broadcom, Micron, AMD and CoreWeave representing about 46.5% of the index’s value, or 39.3% of the entire 3000-company NASDAQ composite.
These same names — replacing CoreWeave with Oracle — represent around 28.9% of the value of the S&P 500.
To sustain the valuation of these stocks — let alone continue growing — will require every company involved to either spend or make hundreds of billions of dollars in perpetuity, increasing every single quarter, without fail. This will come from either selling ever-increasing amounts of AI chips and related hardware, or buying and using them to generate revenue either through rentals or building their own software products.
While the centralization was more severe at the top of the Dot-Com era NASDAQ — with Cisco, Intel and Microsoft accounting for roughly 74% — the total value of the index was a mere $1.82 trillion ($3.58 trillion adjusted for inflation).
Today’s top three — NVIDIA, Google and Microsoft — account for around 29% of the NASDAQ 100, for a total market capitalization of $13.5 trillion.
I’m afraid things only get worse.
Per Goldman Sachs (via Reuters), "...equity gains have been the dominant driver of household wealth accumulation and the main contributor to a positive wealth effect on consumer spending," and per data from the Fed, corporate equities accounted for 37.9% of all household wealth in Q2 2026, the highest number on record since Q4 2000.
Economist Paul Kedrosky told me it might actually be higher:
Americans are near records in terms of equity exposure, over 50% [as in number of Americans holding stocks], ahead of real estate for the first time since WWII — and Americans are at record levels in terms of equities as a percentage of their liquid net worth — over 60%.
While the Fed’s data only goes back to Q4 2000, corporate equities as a share of household wealth only sat at 25.9% ($11.5 trillion, or $22.7 trillion adjusted for inflation), back at a time when total household wealth sat at $44.4 trillion, or about $85.2 trillion in today’s money. In Q2 2026, total household wealth sits at about $195.8 trillion, with corporate equities sitting at roughly $74 trillion, or roughly 86.8% of the entire US household wealth 26 years ago.
Retails are also making up an historically-large amount of the volume of trades on the market, per Bloomberg Intelligence, making up 20.3% of trading in 2026 to date, approaching the dangerous heights of the worst excesses of the end of the Zero Interest Rate Policy era.
Retail investors also directly own about 29% of Amazon’s, 26.2% of NVIDIA’s, 22.6% of AMD’s, 21.8% of Microsoft’s, and 18.6% of Meta’s stocks, though these numbers are not inclusive of index funds like SPY or QQQ (a fund tied to the NASDAQ). In totality, retail investors own equity assets (at least as of May) equivalent to about 10% of the market.
In fact, Goldman Sachs had retail volumes significantly higher:
In a note to clients, analyst Daniel Chavez explained that Goldman Sachs trading desk data shows retail volumes have risen 28% since mid-April, with a basket of retail-favorite stocks tracked by the firm gaining 29% over the same period.
By comparison, Dot-Com era retail trading was much, much lower — less than 2% of the NYSE’s trading volume according to the University of Michigan’s Alicia J. Davis in a paper that begins with the phrase “the American retail investor is dying.”
When all of this is over, I think retail investors might wish they were dead, as they directly own somewhere in the region of $4.65 trillion worth of NVIDIA, Amazon, Microsoft, Google, Meta, Broadcom, AMD, Micron, Oracle, and CoreWeave stocks. The number is likely much smaller than the true exposure retail investors have, as it isn’t inclusive of investments in index funds.
Sidenote: For some comparison, the total market capitalization of Microsoft, Cisco and Intel on March 10, 2000 (the peak of the market) was around $1.36 trillion.
Another point is that, unlike 2000, retail investors have easy access to exotic securities contracts that weren’t previously available (or, if they were available, were expensive or otherwise obscured from the casual view of most retail investors), and that have the potential to amplify any potential losses.
RobinHood, for example, allows retail investors to buy event contracts (where “investors” speculate on an event with a yes/no outcome), to trade futures, to short stock, and to invest on margin, or with borrowed money. All of this can be done (assuming the investor meets the criteria to access these products) with a few taps on a phone, effectively eliminating the friction associated with making a potentially life-altering financial decision.
Sidenote: CoreWeave isn’t on the S&P 500 and Oracle isn’t on the NASDAQ, just for comprehensiveness.
On April 14, 2000, the NASDAQ composite dropped 9.67% and the S&P 500 5.78%, with a little under 97% of the S&P 500 constituents falling on the day, per TIME and The Washington Post, led by hot inflation numbers and overall anxiety over the tech sector’s valuations:
There were virtually no exceptions to the decline. The correction, analysts said, was taking no prisoners. The crash came at the end of an extraordinary week, where volatility and huge drops were the rule rather than the exception. And market analysts said they expect the declines to continue next week--and possibly in the coming weeks and months--as overvalued stocks come down to earth.
Yet the Post had one telling quote, emphasis mine:
Market momentum--which has trended up for the longest bull market in history for much of the past decade--has now turned down. The recognition that many technology stocks can't possibly grow quickly enough to merit the heights they achieved through momentum investing may have pierced the bubble of overvaluation in recent weeks, analysts said, as momentum changed direction. That turnaround has sent the Nasdaq composite index down 35 percent since its high on March 10.
While it seems unlikely, a drop of around 20% across NVIDIA, Amazon, Google, Meta, Broadcom, AMD, Oracle, Micron, and CoreWeave would have the same effect as the entire market downturn on the worst day of the Dot-Com Bubble crash.
In truth, it wouldn’t even have to be that bad.
Per CNN Moneyline News Hour transcript from April 14, 2000, Qualcomm fell 21%, Yahoo fell 20%, Intel a little over 10%, and Microsoft a mere 5% — and that’s all it took to make the market bottom out.
Brief NVIDIA selloffs have already caused big market declines:
Anyway, remember that quote about momentum investing, overvaluations and growth? Here’s a quote from Bloomberg from last week (October 14), emphasis mine:
Chipmakers fell for an eighth straight day, the longest slide since 2008, on worries over whether the AI infrastructure buildout has outrun the ability of firms to get a return on their investments. CoreWeave Inc., a cloud-computing services provider whose bonds recently hit levels that typically signal distress, sank 12%. The S&P 500 lost 1.1%. Oil climbed, weighing on Treasuries.
And here’s another quote from CNN from a day later, emphasis mine:
The global retreat in chip stocks followed a sharp sell-off on Wall Street on Wednesday, after a strong US inflation report bolstered worries that rising interest rates will make it more expensive for companies to fund AI investments. Many AI companies are already heavily indebted.
History may not repeat, but it rhymes. Every problem that burst the Dot-Com Bubble is here, but it’s worse, bigger and uglier, with global contagion risk that I basically never see discussed.
For example, the ongoing equity price of TSMC on the Taiwanese Stock Exchange makes up about 40% of the entire market, with the ODMs that have seen booming earnings making AI servers for hyperscalers representing another 3% or so. On The Tokyo Stock Exchange, the combined weight of SoftBank, RAM maker Kioxia, and the two major banks (SMBC and MUFG) backing AI data centers make up approximately 11.24% of the TOPIX Index. Samsung and SK Hynix, both of whom have seen remarkable RAM sales (see my Hater’s Guide To The Memory Crisis for more), make up more than 50% of the entire value of Korea’s KOSPI.
Their elevated valuations come from a belief that they’ll grow in perpetuity, much like the American markets.
And let’s be clear about something: all it takes is the vibe souring to the point that people lose faith in the AI trade for everything to start to collapse.
So, what will it take to keep the party going?
The answer is simple: perpetual, parabolic growth in both AI revenues and AI capex.
Per CNBC, well, exactly what I’ve been saying, emphasis mine:
“At the moment, we have more compute capacity than we have demand, and we have a lot of the tokens and processing power being given away in freemium solutions,” [Gartner’s John Lovelock] told CNBC. “Everyone in the AI race is running for a last-man standing position. Pretty much every market that Gartner is tracking in our AI race is likely to collapse down to a duopoly.”
Neoclouds would not be going out of business en masse, Lovelock reiterated, but could be subject to consolidation, such as takeovers and mergers.
As a result of their profitability analysis, Gartner predicted last week that 80% of neoclouds, which are AI-dedicated computing power providers, could cease functioning as independent companies.
Oh!
Are…are you sure about that? Isn’t AI the biggest, most hugest thing ever? It’s transformative! It’ll change everything! Aren’t we all excited-
Lovelock also said Monday that AI is a technology as opposed to a market, comparing it to table salt that will be sprinkled into existing commercial operations rather than creating an inherently new field in which companies will sell differentiated and competing products.
Okay, well, check out Doctor Doom over here, I bet he’s gonna be so surprised when those profitable returns come in-
In their Wednesday report, Gartner researchers found that overall “AI revenue will be insufficient to support profitable returns on all planned AI capital expenditures” between 2027 and 2030.
Well, at least there’s a diverse revenue base for GPU sales-OH MY GOD!
NVIDIA has guided to a 70% increase in its next fiscal year — I assume FY2028, starting February 2027 — or over $670 billion in annual revenue, over three times its FY 2026 sales, with said sales dependent on whether Microsoft, Google, Amazon, Oracle, Meta, SpaceX (who collectively make up 50% to 60% of NVIDIA’s data center revenues), and the various neoclouds like CoreWeave, Nebius, and Nscale keep buying more of them every quarter, or at the very least that a willing vessel can step in to pick up the slack if they stop. If demand wavers, NVIDIA, Broadcom, Micron, AMD, and any associated silicon or hardware counterparties will see their revenue growth stumble, which will have a brutal knock-on effect on their stocks.
NVIDIA already has its own revenue concentration problem — 44% of its first half FY2027 revenues came from three customers, and in Q2 FY2027, 70% of its accounts receivables were from three customers, with 16% of its revenues coming from one. One. How is this not more worrying to people?
Anyway, to buy those GPUs (or TPUs, in Broadcom’s case), everyone outside of Microsoft will have to raise tens of billions of dollars of debt at a time when underlying interest rates are growing and the overall debt markets have chilled around AI data center debt.
Said chill comes from the world finally waking up to what I said in March 2025 — that CoreWeave is a time bomb of expensive debt that’s now selling off as people realize that making any of its supposed $104 billion in backlog (at least 50% of which is OpenAI and Anthropic) will require, per UBS, about $102 billion in debt in the next three years. CoreWeave’s long-dated bonds (by which I mean maturing in 2031) had an effective yield of as much as 16% in the last week.
With endless delays and hundreds of billions of dollars of chips sitting in storage, AI data centers have dramatically turned from the panacea for all infrastructure investment to fixed-income nightmare fuel. For whatever reason, nobody thought that lending hundreds of billions of dollars to a selection of different dodgy SPVs and neoclouds to build the world’s most ambitious infrastructure projects was a problem until, well, everybody, per the WSJ:
There has been a surge in issuance of bonds to finance the construction of data centers for AI computing. This year through Oct. 16, data-center issuers have raised more than $100 billion in the U.S.-dollar bond market, or about 25% of AI-related gross issuance in U.S. currency, according to data from Dealogic and Goldman Sachs credit research analysts. That is up from around 16% the prior year.
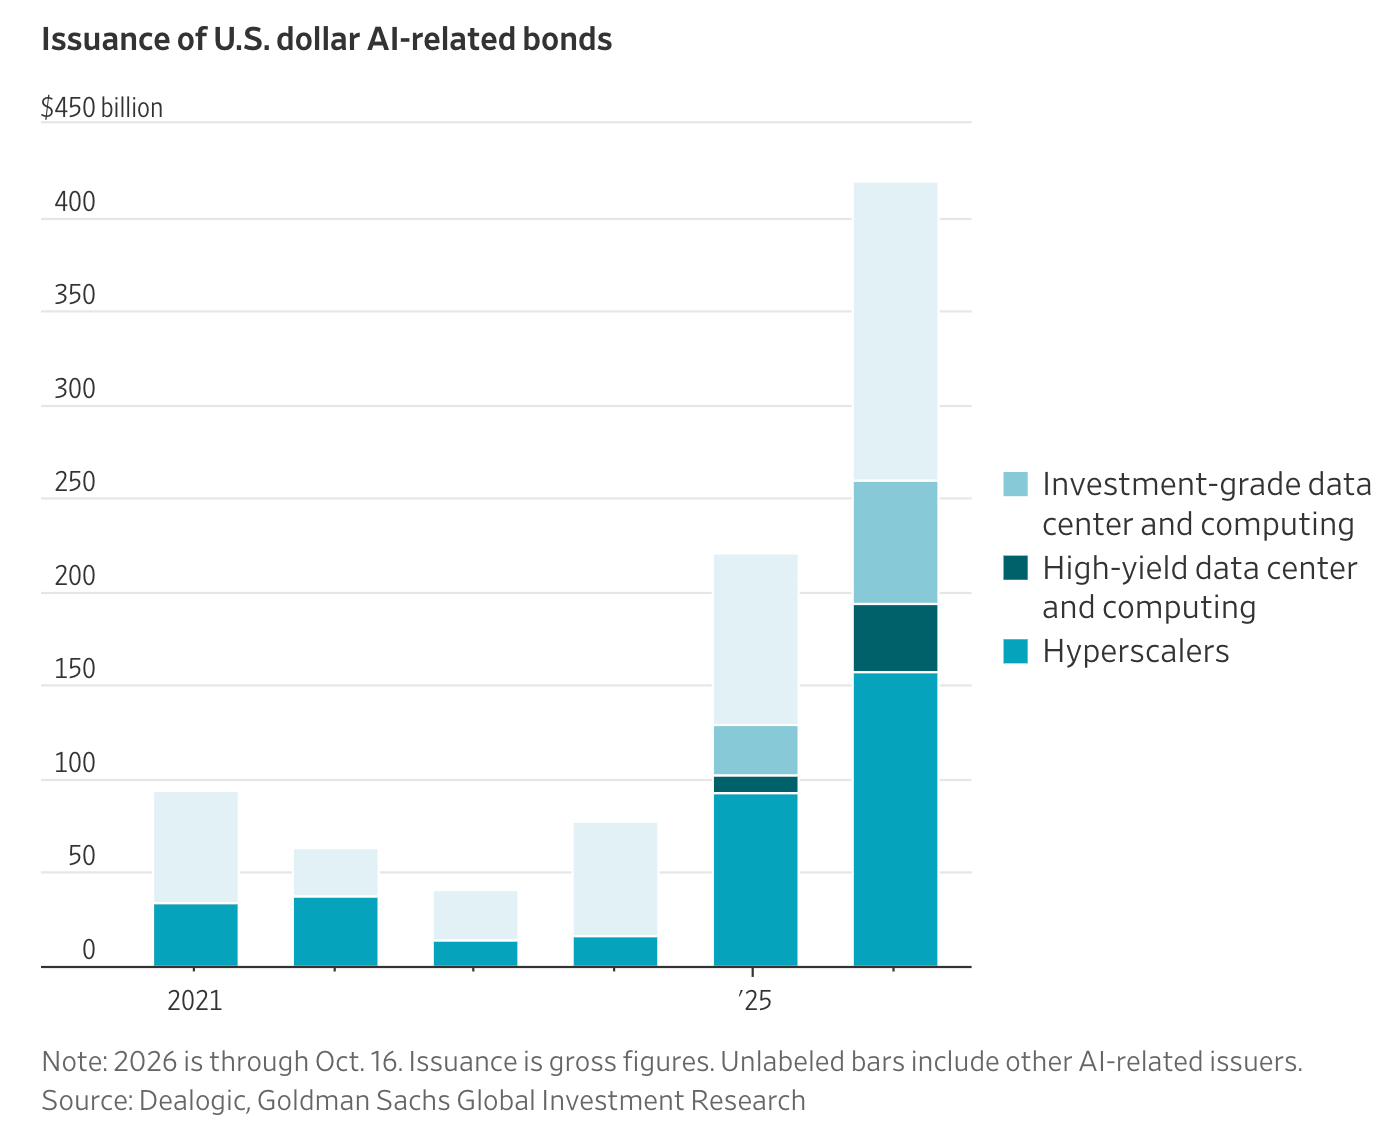
Per the Journal, this debt heavily relies on both the continued value of the data center and critical IT gear and whether the bloody thing actually gets built:
The recent AI data center bonds typically have structures that are different from a company’s bonds. They can be secured by the data center being built, while corporate debt is unsecured. How much security that provides, though, also rests on the completion of the data center, and on the value of the data center to another tenant. Effectively, investors are betting that overall demand for data infrastructure means the data center will be of use to someone, even if the current tenant runs into trouble.
In other words, the value of that data center debt is heavily contingent on whether the underlying assets retain their value, which in turn is contingent on whether there are customers that exist. For whatever reason, nobody wants to consider the most obvious problem: that if one customer can’t pay, other customers can’t pay, and if other customers can’t pay, there’s going to be less demand for AI data centers in general, which means there will be a glut of data center infrastructure, which will mean those assets you intend to resell if everything goes poorly won’t be worth as much.
I sure hope that financial institutions have a plan…
“With a data-center bond, you’re underwriting assets, and our view has been that when it gets completed, that can be a meaningful catalyst for spreads to compress,” says Andrew Keches, who is tech, media and telecom credit analyst and head of high-yield research at Barclays.
Oh okay, the problem with overly-expensive AI data center debt is simply that the markets will feel better when the underlying data centers (which are overwhelmingly delayed) get built? Awesome! It’s just that simple! I’m sure somebody out there will deal with the massive delays for the talent, materials and power connections necessary to complete them!
As of writing this sentence, CoreWeave’s bonds are trading somewhere between 14.1% and 15.1%, and the only way it can calm investor anxiety will be building AI data centers at a rate that has proven next to impossible.
Part of the problem is that recent pushes by smaller and somehow-dodgier neoclouds like Firmus (which just pulled its IPO) and Nscale (whose investors are pushing for it to nearly halve its IPO float to $16 billion and just lost Microsoft as a client due to power delays) have made investors intimately aware of the overpromises of AI data center companies.
Both Nscale and Firmus have the same customer concentration problems as CoreWeave, with 85% of Nscale’s backlog coming from Anthropic and Microsoft, and 90% of Firmus’ coming from Meta and OpenAI. Again, these are problems that CoreWeave, IREN and Nebius have had for years, but for whatever reason everybody has decided to wake up. Everybody has the same backlog customers — Microsoft (for OpenAI), Meta, OpenAI, Google (for Anthropic and OpenAI), Amazon (for Anthropic), and, of course, Anthropic.
All this ire towards AI data centers means that the price of borrowing for them is skyrocketing on top of ten-year-dated Treasuries stubbornly sitting above 5%, which makes the overall economics of AI data centers increasingly problematic, as nobody can seem to measure A) how much they make and B) how much they cost.
Or, indeed, how any of this will pay off.
Congratulations to Eugene Kim of Business Insider for getting one of the biggest scoops of the AI bubble, confirming my estimate that billions of dollars of NVIDIA GPUs were being warehoused in this incredible story, emphasis mine:
Some AWS data center sites had room for more racks but not enough available power to turn them on, people familiar with the effort said, leaving the equipment to be staged at intermediary warehouses until the facilities were ready. These people asked not to be identified discussing sensitive matters.
Usually, Amazon doesn't pay for racks until the gear is put into a data center, leaving suppliers to carry the cost of the equipment in transit, according to the internal documents obtained by Business Insider. This helps the company conserve cash.
However, the intensity of the AI data center building boom has made this type of coordination harder. Amazon has to compete more for scarce resources as it jockeys with rivals for access to Nvidia GPUs and other AI components.
Under the new "Early Rack Receipt" process, Amazon now takes ownership of these racks earlier in the supply chain, rather than waiting until the equipment reaches a data center.
That means spending cash sooner. And any delays getting the racks installed and plugged into a reliable power source potentially pushes back the moment when revenue starts flowing from these assets.
At least one AWS supply chain team did not have "a clear forecasted path" for getting racks into data centers, according to one of the emails reviewed by Business Insider.
If you’re wondering exactly how much it’s warehousing…
One Amazon email projected the company would take delivery of about $5 billion of Nvidia GB300 racks in August, followed by another roughly $3 billion each month "for the foreseeable future."
That’s right folks — Amazon, which spent $54 billion in capex last quarter — is taking $3 billion worth of GPU deliveries every month “for the foreseeable future,” despite having such a supply glut that it cannot install them, and in some cases lacks an idea of when it may do so.
As I discussed a few weeks ago, neoclouds and hyperscalers have over $374 billion in “construction in progress” assets, and I estimate that $200 billion or more of them are GPUs, primarily from NVIDIA. One quote from the piece stood out to me, emphasis mine:
Usually, Amazon doesn't pay for racks until the gear is put into a data center, leaving suppliers to carry the cost of the equipment in transit, according to the internal documents obtained by Business Insider. This helps the company conserve cash.
However, the intensity of the AI data center building boom has made this type of coordination harder. Amazon has to compete more for scarce resources as it jockeys with rivals for access to Nvidia GPUs and other AI components.
It appears that NVIDIA is channel stuffing. The phrase “compete more for scarce resources” doesn’t make sense in the context of GPUs that you don’t have enough power or space to install…unless, of course, NVIDIA is saying that if you don’t order and take delivery right now, the GPUs won’t be available by the time you actually build that data center.
The booster counter-argument will be that “Amazon is just planning ahead,” but riddle me this — if Amazon, Google, Microsoft (CEO Satya Nadella said he had chips “sitting in inventory he couldn’t plug in) and many other companies do not have the power to plug in the chips…why are they scarce? What’s making them scarce? If companies cannot install the chips (or, put another way, do not need them yet) what is creating the scarcity, other than something that NVIDIA itself is demanding its partners do?
Then there’s that curious matter of the whole “Amazon doesn't pay for racks until the gear is put into a data center.” How long has that been the case?
Let’s get specific about the verbiage — “...suppliers…carry the cost of the equipment in transit…” heavily suggests that these racks (which had GPUs in them, by the way!) were not actually shipped to customers until the customers needed them…until some indeterminate point at which the “Early Rack Receipt” program took place.
This, if anything, proves that the “demand for AI chips” is far more a result of NVIDIA’s deliberate channel stuffing and antagonistic approach to doing business than anything about how many chips the world needs right now.
Sidenote: Fuck Jensen Huang, man. This means that the increased price of RAM and consumer electronics was a result of an artificial "supply chain crisis" created by Jensen Huang pushing NVIDIA's customers to take early delivery of GPUs. Jensen Huang is responsible for making life worse for everyone. What a greedy, joyless, soulless oaf of a man. Doing this requires you to be a certain kind of low that no money or status can ever fix.
Jensen Huang is a piece of shit. Every hyperscaler CEO is too. These scumbags drove the price of everything up so that they could all help Jensen Huang make more money. We did not need him to build all these GPUs. He just wanted to sell them to boost earnings. Everyone who participated in the early shipment of GPUs is a scumbag.
I would like to take this opportunity to apologize for taking a break from calling these people what they were. I decided to temper some of my more acerbic tendencies because I figured it should take a back-seat to my financial analysis. I won’t make that mistake again.
What these people have done is morally reprehensible, on top of the already-vast damage done by the very existence of generative AI. This destructive, pointless void of an industry has made everything it touches worse, all to prop up the vague dreams and excesses of the wealthiest, most powerful and utterly fucking dull pieces of shit I’ve ever had the misfortune of witnessing. Everything is more annoying, expensive and worse on some level because of generative AI, down to the price of fucking US treasuries. Everyone who aided in the ascent of generative AI should know they have profited off of making the world worse.
A divide has emerged that is much, much larger than data centers. How into AI were you? How defensive of the industry were you? Were you normal about LLMs, or did you act strangely defensive of them? Why did you do that? How gullible were you about the financial or technical promises of AI? These questions will likely be asked of you in the next few years, and I believe your answers will be illuminating. Even if LLMs somehow survive in an open source form, the industry as it exists today is held together through cultism and private equity excess and is rigged to blow. The world will be different afterwards, eventually for the better.
Anyway, even if hyperscalers installed all the fucking things, it’s unclear who would actually pay for them at a volume that would match analyst expectations.
Per Slok at Apollo, financial analysts covering the tech sector seem to be pricing in cash flows that do not match with reality, emphasis mine:
The analysts covering tech expect the sector's operating cash flow to more than double to roughly $2.4 trillion by 2028, an increase of over $1.2 trillion, see chart below. Meanwhile, the analysts covering the other sectors in the S&P 500, which are tech's customers, expect those companies to add much less operating cash flow.
In other words, the tech silo is betting on a future in which demand for AI and tech services explodes, while the silos covering the companies that would pay for those services see a much more modest outlook. Both cannot be right at the same time.
The bottom line is that either tech's customers will generate a lot more cash than their analysts expect, or tech's cash flow forecasts are too optimistic, which raises the question of who exactly will be writing all those checks to buy AI services.
So, in case you didn’t know, every time a company reports earnings, financial analysts at big financial institutions set expectations — sometimes years in advance — of their expected revenues and cashflows. Right now, the analysts covering tech companies are guiding towards them adding $1.2 trillion in operating cash flows, all as the rest of the S&P 500 (ostensibly its customer base) doesn’t add anywhere near that much money.
This is one of those very simple points that nobody seems to be able to answer about AI: where will all the money come from to pay for those revenues?
As Torsten said, tech analysts are expecting a parabolic surge of revenues across the entire tech stack, but the analysts covering them are saying the cash won’t be there.
What’s the plan, exactly?
The answer, it appears, is “Anthropic and OpenAI,” and maybe “open source” sales of indeterminate value.
Sadly, there’s another wrinkle in the plan.
Japanese financial services firm Nomura put out a worrying take a few days ago, emphases mine and from the poster I found it from:
Anthropic hosted a presentation for investors on 15 October. The Financial Times reported sales at Anthropic of $16.8bn in Jul–Sep, versus $11.5bn in Apr–Jun and $4.8bn in Jan–Mar. We have not verified this. We regard ARR at Anthropic as a useful barometer of data center capex, as we think it is currently able to monetize data center capacity better than any other frontier AI lab. For example, (1) assuming that Anthropic has data center capacity of 5GW and ARR of $120bn at end-2026, we estimate that 1GW in compute resources translates into annual sales of $20bn. In addition, (2) if 60% of this revenue is spent on purchasing computing resources, we estimate that it will be able to spend $12bn a year on 1GW of data center capacity, and (3) if data center equipment is depreciated over five years, $60bn per GW represents about the most that can be allocated to data center construction (while noting that data centers also incur operating costs, and that the depreciation scheduled for power infrastructure depreciation is longer than five years). Increased ARR per GW is likely to boost data center spending, and the opposite is likely to hold true too. Assuming that growth in ARR at Anthropic slowed q-q in Jul–Sep, as the Financial Times article suggested, we think this might encourage a slightly more cautious outlook towards data center investment. Moreover, even if rivals were to lose market share to Anthropic, we note that revenues per GW could come under downward pressure across the industry as a whole.
We expect uptake of multi-agent systems (MAS), in which agents collaborate among themselves to execute prompts, and think demand for computing resources will rise once cost-effectiveness has been demonstrated. We think it makes sense to gauge whether the current cost of data center construction is commensurate with the economic benefits that AI models generate by looking at ARR generated by Anthropic and other frontier AI labs, as well as at new services and inventions.
To simmer it down, Nomura is saying based on how much a data center costs both to build and operate, you shouldn’t spend more than $60 billion given the amount of revenue you could hope to generate.
It’s hard to get a precise measurement of how much one costs. The CEO of IBM said $80 billion a gigawatt at the end of 2025. Foxconn said $47 billion per gigawatt in September 2026. Back in June, Jensen Huang said future data centers could cost $80 billion to $100 billion a gigawatt. It is completely insane we do not have a consensus here.
Nomura also throws cold water on the many people excitedly suggesting that Anthropic could make $50 billion to $75 billion a gigawatt, suggesting instead that the number is around $20 billion. In other words, if Anthropic is paying anything more than $20 million a megawatt, it’s losing money hand over fist just on the compute alone.
Anyway, I sure hope that the people building these data centers aren’t dependent on Anthropic’s revenues…
More-importantly, outside of the companies selling the hardware, we know very little about the actual revenue generated from renting AI GPUs. Amazon, Google, Microsoft, and Meta refuse to disclose their actual AI revenues — but analysts estimate that more than 70% of Amazon, Google and Microsoft’s AI revenues come from Anthropic and OpenAI’s compute spend, which is contingent on their continued ability to raise tens of billions of dollars.
As I’ve discussed in the past, I see around $22 billion in non-OpenAI/Anthropic compute spend globally, with an indeterminate amount of that coming from AI startups that, well…
Said billions are contingent on the AI labs’ continued revenue growth, and considering that 80% of Anthropic and OpenAI’s enterprise revenues come from loss-making AI startups allowing their customers to burn many times their subscription price in AI tokens (as much as $1,300 on Cognition’s $200-a-month plan, for example), meaning that Anthropic and OpenAI’s revenue growth is contingent on venture capital’s continued ability to fund their customers.
This is one of the core issues with measuring AI demand — that the vast majority of it comes from selling services that do not make any economic sense.
And their spend is contingent on their backers funding them in perpetuity.
That won’t be easy.
This, in turn, is contingent on venture capital’s continued ability to fund raise, and as I discussed in last week’s premium, VC has been on an historic losing streak since 2017, with the median net TVPI (total value put in, as how much you get in return on a per-dollar basis) sitting between 92 cents and a dollar, with 2025 fundraising dropping by 35%, and 2026 fundraising for first-time funds at its lowest rate in over a decade, per Murph Capital, which adds that despite representing only 6% of funds closed, funds of $500 million or more took 78.1% of all capital raised in 2026 to date.
AI startups, which are predominantly unprofitable, unsustainable, and require near-constant flow of venture capital, represented 64% of all venture capital investment in Q3 2026, with 50% of all global venture flowing into AI in 2025.
As discussed both last year in the Enshittifinancial Crisis and last week’s premium, AI startups represent a devil’s deal for venture — by virtue of being buzzy “AI” companies, their valuations are naturally high, and by virtue of their capital-intensive businesses, they require more rounds of venture capital, with each round increasing valuations to unsustainable heights that make their IP-light, EBITDA-negative businesses impossible for either an IPO or potential acquisition.
In fact, both venture capital and private equity are having real problems selling their investments, with IPOs becoming effectively non-existent as a share of exits for PE, per S&P Global.
Meanwhile, per DealRoom, venture-backed from 2026 seem high, but are inflated by SpaceX’s IPO ($75 billion), the PE-backed take-private of gaming company Electronic Arts ($55 billion), SpaceX’s acquisition of Cursor (all stock, $60 billion), NVIDIA’s acquisition of Hugging Face ($13 billion), and Google’s acquisition of Wiz ($29 billion).
And since 2015, the $2.7 trillion in venture capital invested has only managed to increase its value by about 1.6x — to around $4.4 trillion in value (not returns), or around a third of what you’d get if you’d have invested in the S&P 500.
In other words, venture capital is not particularly good at creating value, and has, in a period of poor value creation, centralized the majority of its investments in a single industry, with the majority of those investments going to companies related to or powered by Large Language Models that have yet to prove their economic worth.
And in this historically-low period of fundraising and exits, venture capital has invested a historically large amount of money, with the vast majority of it going into one bet: AI.
What’s that phrase? “You should always keep your eggs in one basket, so that you know where they all are”? I think that’s it, right?
At this point, the sheer scale of the AI bubble is too large and unwieldy for things, to quote Mr. Slok, “work out,” and yes, I believe we “have a problem.” I say this with no sarcasm, as I think Torsten has done fantastic work posing reasonable, logical questions that nobody seems to want to answer, like “how does this work out?” and “where does the money come from?” even as most media outlets and analysts nod and smile at basically any statement said by an AI lab, hyperscaler, or neocloud.
For everything to “work out,” the current equities surge will have to continue in perpetuity, which requires both hyperscaler AI revenues — which are already depressingly small — and hyperscaler capex to expand infinitely, along with neoclouds, sovereign clouds and AI labs’ vague infrastructure plans to also expand infinitely.
All the while, there can be no perceptual shift against generative AI, because any further souring of the debt markets will have neoclouds and would-be data center operators paying 12% to 15% in interest to build data centers sometime three years in the future for a customer base that’s pretty much entirely made up of Anthropic and OpenAI.
As we’ve seen in the last few weeks, AI debt markets can quickly sour even without any bad news, and conditions will only improve in connection to an incredible earnings season for CoreWeave and other AI infrastructure players.
Said “incredible” earnings would require A) data centers to be built and B) said customers to actually pay for them, which roughly translates to “OpenAI and Anthropic’s continued ability to spend more and more money.” Anthropic’s 47% quarter-over-quarter growth rattled the markets because this company has to grow fast enough to cover $413 billion of non-cancellable compute contracts over the next few years, and everybody kind of knows deep down that the bubble can only continue with parabolic growth, which is why everybody freaked out when OpenAI reported a lower annualized run rate (a made up number) than expected, because growth is the only thing keeping this going.
And said growth rate is predominantly based on whether AI startups continue to let their customers spend anywhere from $2 to $10 in tokens per dollar of subscription, which in turn is dependent on venture capitalists’ continued status as the world’s most braggadocious paypigs, and at some point that venture money will run out, much like it did during the Dot Com Bubble.
I didn’t expect this piece to be so sobering, but when I sat down to write it it just kinda flowed out of me how profoundly difficult the AI industry’s future has become. The fundamental disconnection between the perception of AI growth inflating the value of hyperscaler stocks and the worrying fact that we don’t really know exactly how much AI revenue they make means that the S&P 500 and NASDAQ are held up by a kind of childish excitement that will, at some point, turn to existential fear.
Those reflexively responding with “they’ll get bailed out!” neither understand the markets nor the situation at hand. The AI bubble was inflated by hyperscaler revenue growth (without any disclosure of AI revenue) and NVIDIA’s GPU sales, meaning that the moment one of those slows, everybody freaks out. The US government cannot bail out NVIDIA, Microsoft, Google, Amazon, CoreWeave or Meta’s future misses of analyst expectations, nor can it cover every single bankrupt data center, nor can it bail out investor sentiment when it realizes the AI “boom” was yet another tech-based bust. I went into significantly more detail about it in my premium piece about how AI Isn’t Too Big To Fail.
Remember: even with the bank bailout in 2008, the market still crumbled, and that was before we had over $40 trillion in debt, stubborn inflation, and a stock market that has fundamentally disconnected from reality.
The underlying weakness of the AI trade is that it isn’t really related to anything other than NVIDIA and the hyperscalers’ earnings.
We don’t know how many GPUs are in operation, we don’t know how much money the hyperscalers make from using them or renting them, we don’t know how many active gigawatts of AI capacity they have, we don’t know their actual customer concentration outside of analyst estimates, we don’t really know how much people pay to rent GPUs, and we don’t even know how much it costs to run a GPU on an hourly basis.
OpenAI and Anthropic are horrifyingly unprofitable, deeply unstable, and as I’ve discussed, 80% of their revenues come from companies that literally can’t afford to pay them, and yet the markets never react, because this information doesn’t really matter as long as the right numbers keep going up.
This is why Anthropic’s IPO travails are so profoundly dangerous for the AI trade. Investors are now suggesting that it prices its IPO at $1.5 trillion, meaning a significantly lower payoff for investors and much less capital raised on listing, meaning that it will have to take on more and more debt — like its 10% interest chip financing deal with Broadcom and Blackstone — that will provide a brutal education in what a high-burn-rate, negative-EBITDA company really looks like when you remove the layers of annualized run rates and hype.
And, per Irrational Analysis, Anthropic’s investor day didn’t go particularly well:
Broadly speaking, coding ARR has plateaued, or at least slowed significantly.
OpenAI seems to have no plan, as Sam struggles to raise a new private round at $1.4T valuation. Middle East investors (of all people lol) are pushing back on the valuation.
Anthropic apparently thinks bio (drug discovery) is the next big market for them. Yes, the most regulated and slow-to-revenue industry is what will fund all those "compute commitments”.
I know several people who were at the private Antrhopic (sic) buyside investor day last week. It was apparently a shitshow. Nobody asked an intelligent question. Anthropic was vague and gave little information. Original valuation plan was $2T, dropped to $1.6-$1.8T, and has been dropped again to $1.5T allegedly… in less than 10 days.
Any further delays to Anthropic’s IPO will be somewhere between catastrophic and fatal, and at this point I think it’s fair to question whether it ever makes it to the public markets.
If it does, a $1.5 trillion valuation would spell disaster for OpenAI, which has (as mentioned above) been trying to raise $30 billion at a $1.4 trillion valuation. Closing that round will be difficult to impossible at that price even without Anthropic’s drooping numbers, and if it somehow IPOs at something approaching $1 trillion, I have no idea how Clammy Sammy and OpenAI make it out of this one alive.
And really, does any of this look like the future? Does any of this feel like the next industrial revolution?
Or does it feel like the run-up to another burst bubble and resulting financial crisis?
The difference here is that AI has, for the most part, been sold as a panacea for the rich and powerful — a way to control, to steal, to acquire and to expand, to take and take and take as they always have, occasionally vaguely muttering something about “abundance” as both the media and financial institutions help force through yet another doomed cycle of “innovation.”
The people to blame are the tech CEOs — Sam Altman, Dario Amodei, Sundar Pichai, Andy Jassy, Elon Musk, Hock Tan, Jensen Huang, Sanjay Mehrotra to name a few — and the financiers that have helped them pump this bubble, with the worst of them being that rat fuck Stephen A. Schwarzman, CEO of Blackstone, a private equity (or “alternative asset”) firm that has funded basically every name I just wrote down on some level, funded by everyone from the Saudis to the California state pension system.
This week’s premium will be the Hater’s Guide To Blackstone, a company that vibrates with evil, and has staked its entire future on whether AI works out.
It’s a stupid fucking bet from an evil fucking company, and I can’t wait to tell you all about it on Friday.
If you liked this piece, you should subscribe to my premium newsletter. It’s $70 a year, $18 a quarter, or $7 a month, and in return you get a weekly newsletter that’s usually anywhere from 10,000 to 18,000 words and provides vast, detailed analyses of the biggest events and companies in the AI bubble.
If you want to get in touch — and especially if you have any juicy information about Anthropic, OpenAI, or any other companies in the AI bubble — hit me up on Signal at ezitron.76. I’m also on IB on The Terminal.


